


FIR illegal sans determining tax liability thru assessment, adjudication: SC
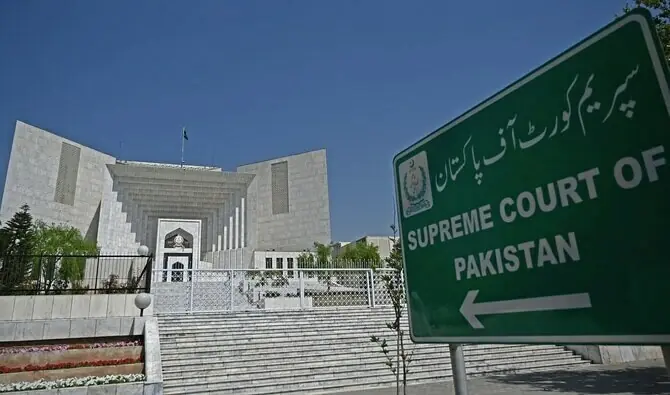

ISLAMABAD: The Supreme Court has held that in the absence of determination of tax liability through the process of assessment or adjudication, the registration of an FIR or initiation of criminal proceedings is illegal.
A two-member bench comprising Justice Malik Shahzad Ahmad Khan and Justice Aqeel Ahmed Abbasi granted pre-arrest bail to the petitioner, observing that it is yet to be determined whether the assets acquired by him constitute proceeds of crime.
According to the facts of the case, the petitioner maintained various personal and business bank accounts with different banks during the period relevant to Tax Years 2017 and 2018. He filed income tax returns for the said tax years, declaring total income of Rs7,313,500 for Tax Year 2017 and Rs6,985,000 for Tax Year 2018.
However, scrutiny of his bank accounts revealed total credits amounting to Rs153,415,348 for the period July 1, 2016 to June 30, 2017, and Rs246,106,305 for the period July 1, 2017 to June 30, 2018.
READ ALSO: Word ‘tax’ in ITO, Article 260: SC judge seeks accurate definition
The scrutiny showed that the petitioner deliberately concealed income totalling Rs. 385,223,153/- during the relevant period and converted the same into assets and business concerns. The tax sought to be evaded was calculated at Rs. 50,670,848/- for Tax Year 2017 and Rs. 83,343,506/- for Tax Year 2018.
In light of that an FIR was registered against the petitioner on 10.02.2022 for offences under Sections 3,4,2 (xxvi), 2(xxviii) of the Anti-Money Laundering Act, 2010 read with Section XIIA of Schedule-I to the Anti-Money Laundering Act, 2010 (AMLA, 2010) and Sections 192, 192 A and 199 of the Income Tax Ordinance, 2001,
The SC judgment, authored by Justice Aqeel Ahmed Abbasi, said that in the instant case the registration of FIR and initiation of criminal proceedings against the petitioner under the facts and circumstances of the instant case are in violation of a recent judgment of this Court in the case of Taj International (Pvt) Ltd case (PLD 2025 SC 633).
The judgment said that the cases pertaining to financial disputes, or allegations of concealment of income and evasion of tax or duty are primarily dealt by Civil Courts or the Specialised forums provided under the Tax laws for the purposes of determination of tax liability through the process of assessment or adjudication through the process of judicial determination of claims of litigant parties after recording evidence in accordance with law.
The Court noted that in the instant matter, the petitioner has been charged with offence of concealment of income and evasion of tax, which requires to be assessed and recovered through process of assessment under the ITO, 2001, whereas, the charge of Money Laundering is also dependent upon the amount of tax sought to be evaded by fraud or wilful mis-declaration and also to determine that any asset acquired through such amount with dishonest intention is proceeds of crime and constitutes a predicate offence in terms of Section 2 (xxvi) of AMLA, 2010, the cognizance of which can be taken under Section 3 of AMLA, 2010 provided pre-trial steps have been exhausted and commission of a cognizable offence is made out. However, no such exercise appears to have been taken, in this case, it added.
The judgment said that the Courts have held that if case is primarily based on documents, custodial interrogation is deemed unnecessary.
Copyright Business Recorder, 2026




















Comments
Comments are closed for this article.