


Millat Tractors Limited: performance and outlook
Millat Tractors Limited (MTL) manufactures and sells agricultural machinery in Pakistan. This article details MTL's fluctuating financial performance and shareholding patterns from 2021-2026, influenced by economic conditions.
- Millat Tractors Limited's diverse shareholding structure.
- MTL's fluctuating financial performance and margins (2021-2026).
- Macroeconomic factors impacting MTL's sales and profitability.
- Future growth strategies, including new distribution agreements.
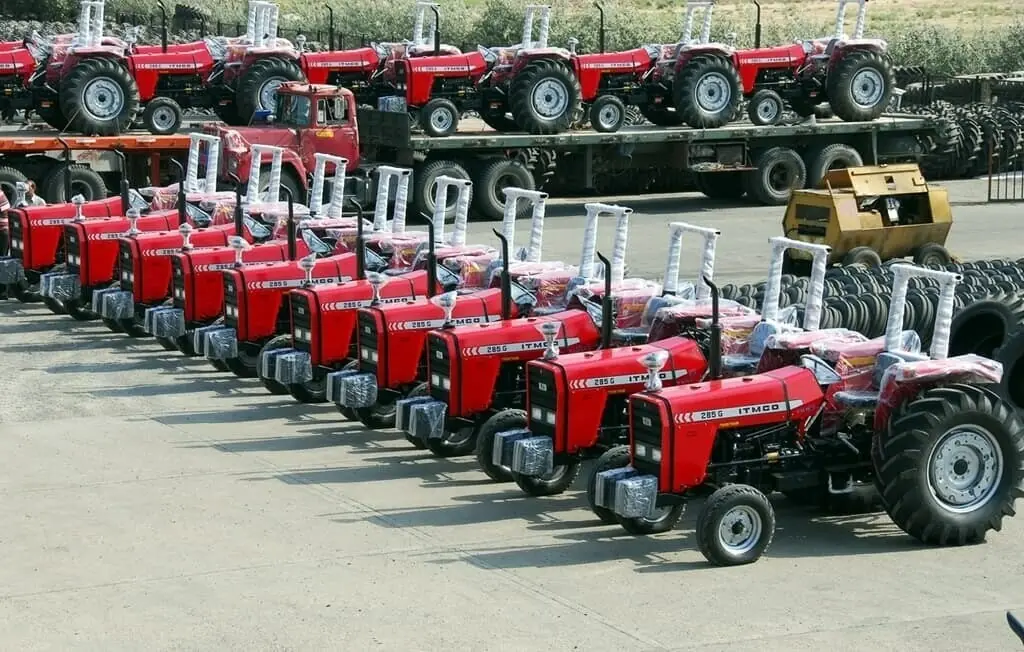

Millat Tractors Limited (PSX: MTL) is a public limited company incorporated in Pakistan in 1964. MTL is engaged in the manufacturing and sale of internationally acclaimed tractors, diesel generating sets and prime movers, diesel engines and forklift trucks.
MTL is also involved in the sale, implementation and support of Industrial and Financial System (IFS) applications locally and abroad. As of June 30, 2024, the company has an annual capacity of 30,000 tractors per annum on a double-shift basis.
Pattern of Shareholding
As of June 30, 2025, MTL has a total of 199,515,947 shares outstanding which are held by 15,461 shareholders. Local general public has the majority stake of 37.02 percent in the company followed by Directors, CEO, their spouse and minor children holding 31.59 percent shares. Associated companies, undertakings and related parties account for 11.37 percent shares of MTL.
Around 10.64 percent of the company’s shares are held by Insurance companies and 3.50 percent by trusts. Banks, DFIs, NBFIs and Pension funds account for 2.65 percent shares of MTL while joint stock companies hold 1.15 percent shares and NIT & ICP hold 1.07 percent shares. The remaining ownership is distributed among other categories of shareholders.
Historical Performance (2021-26)
MTL’s topline tells a mixed tale of ups and downs over the period under consideration. While it plunged in 2020, it rebounded for the next two years, only to nosedive again in 2023. In 2024, MTL’s topline registered a staggering growth which was followed by a drastic fall in 2025 and a decent growth in 2026. Conversely, MTL’s bottomline posted year-on-year growth only in 2021, 2024 and 2026 during the period under consideration. Its margins which were waning until 2020 revived in 2021 and then slipped again in 2022. In 2023, while gross margin inched up, operating and net margins continued their downhill journey.
In 2024 and 2025, gross and net the margins posted reasonable growth while operating margin grew in 2024 and stayed largely intact in 2025. In 2026, all the margins strengthened.
The detailed performance review of the period under consideration is given below.
After two ruthless years, MTL’s top line posted an impressive year-on-year growth of 91.58 percent in 2021 to clock in at Rs.43,953.78 million. This was backed 71.5 percent growth in volumes translating into an off-take of 35,515 units in 2021. The economy started showing signs of recovery post pandemic with agriculture sector growing at the rate of 2.8 percent in 2021.
Wheat bumper crop coupled with increase in minimum support price for various crops by the government resulted in vigorous cash flows and improved liquidity position for the farmers.
The company also achieved the highest ever export sales volume of 2000 tractors in 2021. Due to favorable exchange rate for most part of the year, gross profit enhanced by 118.37 percent year-on-year in 2021 with GP margin jumping up to 21.09 percent from 18.51 percent in 2020.
Carriage and freight charges increased significantly on account of export sales. This coupled with the trademark fee paid to Massey Ferguson played a major role in enlarging the distribution cost by 50.51 percent in 2021.
Administrative expense also escalated by 29.27 percent in 2021 on account of higher payroll expense despite reduction in employee count to 346 in 2021. Other expense grew by 108.27 percent year-on-year in 2021 on account of increased provisioning done for WWF and WPPF.
However, it was offset by a splendid growth of 163 percent in other income driven by robust dividend income from Millat Equipment Limited, gain on sale of short-term investments and return on bank deposits and TDRs. This resulted in a staggering 147.48 percent year-on-year rebound in operating profit with OP margin reaching 17.95 percent in 2021 from 13.89 percent in 2020. 95.75 percent year-on-year drop in finance cost was due to significantly lesser short-term borrowings during the year coupled with monetary easing.
Net profit of MTL measured up by 168.81 percent year-on-year in 2021 to clock in at Rs.5780.93 million with EPS of Rs.59.68 and NP margin of 13.15 percent. This was against the EPS of Rs.38.36 and NP margin of 9.37 percent registered in 2020.
In 2022, MTL’s net sales followed the growth trajectory despite bleak macroeconomic and political backdrop. High energy cost, rise in discount rate and sharp depreciation in currency played tricks on the company’s performance. The off-take was marginally reduced by 510 units in 2022; however, the top line grew by 21.43 percent to clock in at Rs. 53,374.42 million on account of increase in tractor prices.
The rise in the cost of raw materials as well as high fuel and power charges wreaked havoc on company’s cost and squeezed its GP margin to 19.11 percent in 2022.
In absolute terms, gross profit grew by 10 percent in 2022. Selling and administrative expense hiked by 8.60 percent and 11.92 percent respectively in 2022 on account of high inflation which drove the payroll expense up despite reduction in employee count to 334 in 2022. Higher trademark fee was also a key driving force of elevated operating expense in 2020.
MTL recorded net other income of Rs.271.67 million in 2020, up 430.17 percent year-on-year which was the consequence of handsome dividend income. This resulted in 12.73 percent bigger operating profit recorded in 2022, albeit, OP margin marched down to 16.66 percent. Finance cost increased by 2354.87 percent in 2022. This came on the back of several hikes in discount rate during the year.
Moreover, the company faced liquidity issues during the year due to non-repayment of sales tax refunds of Rs.5.7 billion by FBR. Hence, the company had to obtain large amount of short-term borrowings to meet its working capital requirements. The imposition of super tax increased the average effective tax rate for 2022 to 37.52 percent as against effective tax rate of 26.63 percent in 2021.
As a result, net profit posted a year-on-year dive of 6.47 percent in 2022 to clock in at Rs. 5407.01 million with NP margin clocking in at 10.13 percent. EPS also sank to Rs.28.19 in 2022.
The devastating floods in the southern region of the country proved to be the worst beginning of 2023. Shrunken pockets of farmer community squeezed the tractor demand since the beginning of the year. This coupled with sky-rocketed level of inflation, Pak Rupee depreciation, high discount rate, spiked energy charges and import restrictions created chaos in the overall automobile industry which is highly import oriented.
MTL produced 19,022 units in 2023 which were 45.3 percent lesser than the production volume recorded by the company in 2022. This translated into a capacity utilization of 63 percent in 2023 which was even lesser than 2020 level.
MTL’s topline slid by 17.21 percent year-on-year in 2023 to clock in at Rs.44,190.84 million. This came on the back of 47 percent drop in sales volume. Cost of sales inched down by 18.13 percent year-on-year, resulting in 13.29 percent drop in gross profit in 2023. However, GP margin rose to 20 percent due to upward revision in the prices of tractors in 2023 to pass on the impact of cost hike to the customers.
Operating expense surged by 15 percent year-on-year in 2023 due to higher trademark fee and payroll expense incurred during the year.
MTL booked net other expense of Rs.319.01 million in 2023 which was due to significantly lower dividend income recognized during the year coupled with exchange loss incurred due to weaker Pak Rupee. This trimmed down the operating profit by 24.57 percent year-on-year in 2023 with OP margin slipping to 15.18 percent. 496.70 percent higher finance cost incurred in 2023 was the consequence of unparalleled level of discount rate and considerably higher long-term as well as working capital related borrowings in 2023.
MTL’s bottomline slid by 37.53 percent year-on-year in 2023 to clock in at Rs.3377.64 million with EPS of Rs.17.61 and NP margin of 7.64 percent – the lowest among all the years under consideration.
MTL recorded a phenomenal year-on-year growth of 107.13 percent in its topline which clocked in at Rs.91,534.50 million in 2024. During the year, the company produced 30,479 tractors which resulted in capacity utilization of 102 percent.
Dispatches stood at 30,620 units, up 64.43 percent year-on-year. This revival in sales volume came on the back of improved farm economics and robust growth recorded in important crops. Cost of sales mounted by 198.31 percent in 2024. This resulted in 142.40 percent year-on-year enhancement in gross profit with GP margin attaining a new high level of 23.42 percent in 2024.
Selling and distribution expense escalated by 77.68 percent in 2024 on the back of massive spike in trademark fee paid to M/s Massey Ferguson Corp, insurance expense as well as salaries expense incurred during the year. Administrative expense surged by 87.33 percent in 2024 which was the result of higher payroll expense. Number of emplpyes surged to 473 in 2024 versus 336 in 2023. Other income strengthened by 142.39 percent in 2024 on account of hefty dividend received from Millat Equipment Limited and higher return of bank deposits.
However, the impact of other income was completely offset by 59.43 percent hike in other expense due to higher profit-related provisioning.
MTL recorded 168.63 percent higher operating profit in 2024 with OP margin jumping up to 19.68 percent. The company was able to cut down its finance cost by 12.32 percent in 2024 by paying off its outstanding liabilities.
Net profit picked up by 202.72 percent in 2024 to clock in at Rs.10,224.875 million with EPS of Rs.52.26 and NP margin of 11.17 percent.
In 2025, MTL topline fell by a drastic magnitude of 43 percent to clock in at Rs.52,108.997 million. This came on the back of 39.32 percent decline in sales volume which clocked in at 18,580 units. The total units sold also included 5795 tractors sold under Green Tractor Subsidy Scheme of the Government of Punjab.
Capacity utilization was recorded at 62 percent in 2025 versus capacity utilization of 102 percent recorded in 2024.
Demand destruction in the tractor industry was the result of a marginal growth of 0.56 percent recorded by the agriculture sector in 2025. This was due to adverse weather conditions which affected the production of major crops including wheat, cotton, sugarcane, rice and maize. This resulted in tractor industry recording the lowest sales volume in two decades to the tune of 29,192 units. Cost of sales plunged by 45.45 percent in 2025 due to lower production volume, lower inflation and improved value of local currency.
In absolute terms, gross profit deteriorated by 35.30 percent in 2025, however, GP margin attained its highest level of 26.61 percent. Selling & distribution expense dwindled by 14.25 percent in 2025 due to lower trademark fee and insurance fee incurred during the year.
Administrative expense surged by 19.16 percent in 2025 mainly on account of higher payroll expense. This was despite the fact that the company streamlined its workforce from 473 employees in 2024 to 464 employees in 2025.
Lesser provisioning done for WWF and WPPF resulted in 22.65 percent slide in other expense in 2025. Other income also plummeted by 44 percent in 2025 due to no dividend income received from Millat Equipment Limited, lower return on bank deposits due to monetary easing and lower interest received on early payments and advances. MTL also didn’t recognize any exchange gain in 2025.
Operating profit tapered off by 43.19 percent in 2025, however, OP margin stayed almost intact at the last year level of 19.60 percent. Despite monetary easing, the company’s finance cost mounted by 82.60 percent in 2025 due to massive spike in short-term borrowings in 2025. This was due to liquidity constraints faced by the company as its sales tax refund of Rs.7.588 billion was not processed during the year.
MTL’s net profit weakened by 37.67 percent to clock in at Rs.6372.928 million in 2025. This translated into EPS of Rs.31.94 and NP margin of 12.23 percent in 2025.
Recent Performance (2026)
In 2026, MTL posted year-on-year growth of 22.35 percent in its net sales which clocked in at Rs.63,755.24 million. Decline in the purchasing power of farmers due to delays in the implementation of government subsidy schemes, restricted access to affordable financing and spike in fertilizer, fuel and seed prices squeezed the farmers’ ability to invest in new machinery which resulted in lesser sales volume of tractors in 2026.
While volumes weakened during the year, higher per unit value of tractors due to hike in the prices of steel, engine and other imported components drove the net sales up.
Cost of sales grew by a lesser magnitude of 13.47 percent in 2026. This resulted in 46.85 percent stronger gross profit in 2026 with GP margin climbing up to 31.94 percent. Distribution expense mounted by 24.82 percent in 2026 likely due to higher fuel prices which pushed up the freight expense. Administrative expense also ticked up by 8.16 percent in 2026 due to increase in minimum wage rate which pushed up the payroll expense.
Other expense escalated by 26.67 percent in 2026 likely due to higher provisioning done for WPPF and WWF. Conversely, other income dipped by 6.25 percent in 2026 possibly due to high-base effect as the company sold its investments in the previous year. MTL recorded 55.26 percent stronger operating profit in 2026 with OP margin jumping up to 24.93 percent.
Finance cost tapered off by 32.85 percent in 2026 due to monetary easing. The company continued to face liquidity constraints as its sales tax refund mounted. Hence, external borrowings continued to spike. Net profit improved by 23 percent to clock in at Rs.7840.789 million in 2026. This translated into EPS of Rs.19.65 and NP margin of 12.30 percent in 2026.
Future Outlook
The start of green tractor scheme for Medium Horse Power Tractors, seasonal demand from the wheat harvest cycle and flood rehabilitation drives are positive omen for the tractor industry. The company is also planning to focus more on exports so as to offset the impact of thin demand in the home market.
MTL has recently entered into a distribution agreement with Lovol Intelligent Agricultural Technology Co., the largest agricultural machinery manufacturer of China.
Under the agreement, MT L will undertake the distribution of high technology and efficient agricultural machinery in Pakistan. This will strengthen the company’s product range and enhance its presence in the agricultural market.

















Comments