


Cherat Cement Company Limited: performance and outlook
Cherat Cement (CHCC) experienced fluctuating financial performance from 2021-2026, influenced by economic conditions, input costs, and strategic initiatives, with a focus on future growth and diversification.
- Shareholding pattern as of June 2026.
- Historical financial performance from 2021 to 2026.
- Factors influencing CHCC's revenue and profitability.
- Future outlook, including expansion and diversification plans.

Cherat Cement Company Limited (PSX: CHCC) was incorporated in Pakistan as a public limited company in 1981. The company is engaged in the manufacturing, marketing and sale of cement.
Pattern of Shareholding
As of June 30, 2026, CHCC has a total of 194.295 million shares outstanding which are held by 6995 shareholders. Local general public has the majority stake of 27.94 percent in the company followed by associated companies, undertakings and related parties holding 26.40 percent shares.
Modarabas & Mutual funds account for 14.98 percent of the outstanding shares of CHCC while Banks, DFIs and NBFIs hold 8.05 percent shares. Around 3.60 percent of CHCC’s shares are held by Directors, CEO, and their spouse and minor children and 2.60 percent by Insurance companies.
Foreign general public accounts for 1.20 percent shares of CHCC. The remaining shares are held by other categories of shareholders.
Historical Performance (2021-26)
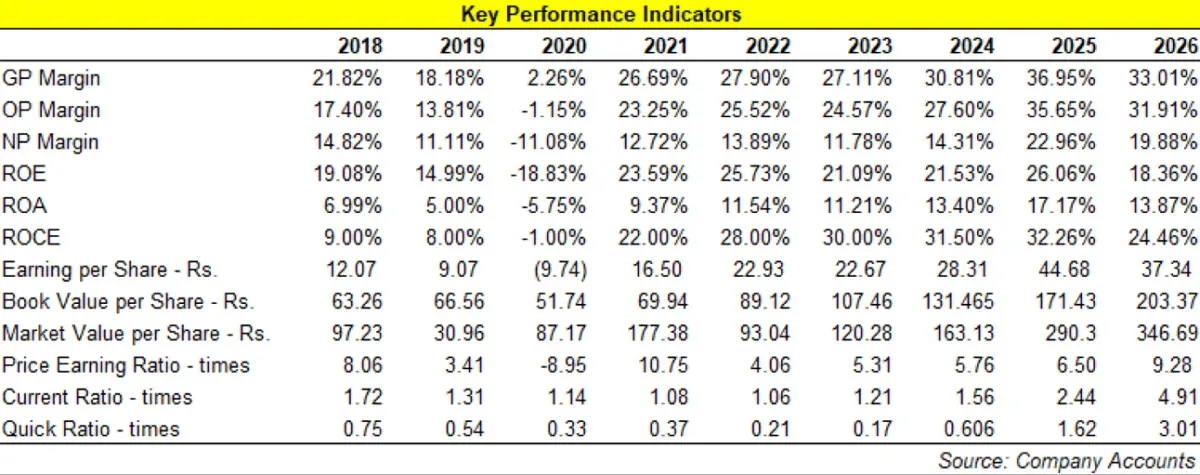
Except for a year-on-year decline in 2025 and 2026, CHCC’s topline posted year-on-year growth over the period under consideration. Its bottomline which posted net loss in 2021 rebounded for the next two years followed by a decline in 2023. In 2024 and 2025, CHCC’s net profit reasonably grew to attain its optimum level. This was followed by a downtick in CHCC’s bottomline in 2026.
The company’s margins followed the similar pattern as its bottomline and reached their peak level in 2025 followed by a decline in 2026. The detailed performance review of the period under consideration is given below.
CHCC clearly seems out of hot waters in 2021 with its topline staggeringly growing by 47.49 percent to clock in at Rs.25,206.81 million. Not only did CHCC did immensely well in 2021, the entire industry’s dispatches rose by 21 percent on account of launch of several government backed construction projects and enhanced allocation and disbursement of funds for PSDP. CHCC’s cement dispatches rose by 16.96 percent to clock in at 3.950 million tons.
Local sales volume grew by 18 percent and export sales grew by 8 percent in 2021. Higher demand also enabled the company to revise its prices which resulted in 1640.89 percent bigger gross profit in 2021 with GP margin jumping up to 26.69 percent from 2.26 percent in the previous year. Distribution expense grew by 18.58 percent in 2021 on account of increased sales volume.
While the company further squeezed its workforce to 966 employees in 2021, inflationary pressure didn’t allow payroll expense to subside. This resulted in 7.16 percent taller administrative expense incurred during the year. Enormous provisioning worth Rs.228.274 million booked for WPPF resulted in 1221 percent surge in other expense in 2021.
Other income grew by 48.67 percent in 2021 on the back of gain on redemption of short-term investments and increased profit on bank accounts. Scrap sales, although slid in 2021, however, made the biggest chunk of CHCC’s other income.
The company made a robust operating profit of Rs.5861.40 million in 2021 which was the highest ever operating profit recorded by the company to-date. This translated into OP margin of 23.25 percent in 2021. The company posted operating loss of Rs.195.73 million in 2020. Finance cost lowered by 39.68 million in 2021 due to monetary easing and a downtick in long-term and short-term financing.
Gearing ratio fell to 55.98 percent in 2021. CHCC registered net profit of Rs.3205.06 million in 2021 with EPS of Rs.16.50 and NP margin of 12.72 percent. This was against the net loss of Rs.1893.11 million and loss per share of Rs.9.74 recorded in 2020.
In 2022, CHCC’s topline further strengthened by 27.29 percent to clock in at Rs.32,085.36 million. Overall cement industry dispatches declined by 8 percent in 2022 due to economic and political instability in the home market and geopolitical tensions in Afghanistan.
CHCC sales volume dipped by 10 percent to clock in at 3.552 million tons in 2022. Local and export sales of CHCC dipped by 5 percent and 43 percent respectively during the year. Hence, topline growth was merely the result of upward revision in cement prices to account for inflation and Pak Rupee deprecation.
Russia-Ukraine crisis also led to commodity super-cycle in the international market. Gross profit enhanced by 33 percent in 2022 with GP margin climbing up to 27.90 percent.
Distribution expense spiked by 23.29 percent in 2022 due to higher fuel prices. Administrative expense enlarged by 19.89 percent in 2022 due to higher payroll expense as CHCC increased its employee headcount to 1007 in 2022, resulting in elevated payroll expense.
Other expense ticked up by 9.53 percent in 2022 due to provisioning done for WWF. Other expense was completely offset by 272.25 percent higher other income recorded by CHCC in 2022 which was the consequence of exchange gain recorded on escrow account. Operating profit strengthened by 39.69 percent in 2022 with OP margin rising up to 25.52 percent.
Despite monetary tightening, CHCC was able to cut down its finance cost by 10.85 percent in 2022 due to repayment of outstanding loans. This enabled the company to mark down its gearing ratio to 48.59 percent in 2022.
Net profit enhanced by 39 percent in 2022 to clock in at Rs.4455.97 million with EPS of Rs.22.93 and NP margin of 13.89 percent.
CHCC’s topline registered 16.52 percent ascent to clock in at Rs. 37,386.19 million in 2023. The country was passing through a rough patch with diminishing FOREX reserves.
In order to resume the IMF program, the government had to take austerity measures in both monetary and fiscal domains. This significantly slowed down the overall economy. Cement industry dispatches recorded a decline of 16 percent in 2023 due to thinner PSDP budget, shaky investor confidence and higher financing rates.
Increase in sales tax and FED on cement also inhibited demand. CHCC’s sales volume plunged by 19.17 percent to clock in at 2.871 million tons in 2023. Local and export sales slid by 16 percent and 13 percent respectively in 2023.
Hike in coal, fuel, electricity and other raw material prices coupled with Pak Rupee depreciation resulted in 17.79 percent hike in cost of sales in 2023. Gross profit in absolute terms grew by 13.25 percent in 2023, however, GP margin inched down to 27.11 percent.
Distribution expense swelled by 14.58 percent in 2023 due to inflationary pressure. Increase in employee headcount to 1022 and inflationary pressure resulted in higher payroll expense which pushed up administrative expense by 24.91 percent in 2023.
Other expense spiked by 31.51 percent in 2023 due to higher profit related provisioning. Other income improved by 16.25 percent in 2023 due to higher scrap sales and profit on bank accounts.
CHCC recorded 12.20 percent higher operating profit in 2023, however, OP margin slid to 24.57 percent. Finance cost mounted by 40.86 percent in 2023 due to higher discount rate. Gearing ratio marched down to 36.72 percent in 2023.
Super tax levy was increased from 4 percent in 2022 to 10 percent in 2023. This resulted in 1.17 percent contraction in CHCC’s net profit which clocked in at Rs.4403.93 million in 2023 with EPS of Rs.22.67 and NP margin of 11.78 percent.
In 2024, CHCC’s topline ticked up by 2.80 percent to clock in at Rs.38,433.75 million. This primarily came on the back of upward revision in cement prices to offset higher input cost – particularly electricity and gas tariffs.
The company’s overall dispatches tumbled by 8.50 percent to clock in at 2.63 million tons in 2024. While local sales slid by 13 percent, exports sales surged by 22 percent due to increased exports to Afghanistan.
During 2024, the company’s cost of sales dropped by 2.41 percent which was achieved through the optimization of coal and power mix. Lower cost coupled with increased cement prices resulted in 16.81 percent higher gross profit recorded in 2024 with GP margin attaining an unprecedented level of 30.81 percent.
Higher export sales resulted in 25.42 percent greater distribution expense in 2024. Administrative expense mounted by 14.75 percent in 2024 on account of inflationary pressure. This was despite the fact that CHCC streamlined its workforce from 1022 employees in 2023 to 978 employees in 2024. Increased profit related provisioning pushed up other expense by 28 percent in 2024; however, it was offset by 8.69 percent higher other income.
Superior other income recognized during the year was the result of robust dividend income and profit on bank accounts. Scrap sales drastically fell during the year. CHCC recorded 15.49 percent higher operating profit in 2024 with OP margin of 27.60 percent. Scheduled and early repayments of long-term loans resulted in 27.85 percent slide in finance cost in 2024 despite high discount rate.
Gearing ratio clocked in at 18.05 percent in 2024. Net profit grew by 24.88 percent in 2024 to clock in at Rs.5499.75 million with EPS of Rs.28.31 and NP margin of 14.31 percent.
CHCC’s net sales tapered off by 1.62 percent to clock in at Rs.37,810.81 million in 2025. The company’s overall dispatches contracted by 9 percent to clock in at 2.39 million tons in 2025. Local sales volume slid by 10 percent due to macroeconomic flaws while export sales volume slid by 3 percent due to logistics issues.
The decline in CHCC’s topline would have been more profound if the prices were not increased by Rs.1400 per ton locally and Rs.323 per ton internationally. During the year, the company raised its overall solar capacity to 23 MW by commissioning an additional 9 MW solar capacity. Efficient coal procurement strategies also kept a check on CHCC’s cost of sales in 2025.
Cost optimization coupled with increased retention prices culminated into 18 percent stronger gross profit in 2025 with GP margin attaining its optimum level of 36.95 percent. Distribution expense escalated by 12.32 percent in 2025 due to higher salaries of sales force and increased advertising & promotion budget allocated for the year.
Administrative expense mounted by 19.18 percent in 2025 due to higher payroll expense.
This was despite the fact that the company streamlined its workforce from 978 employees in 2024 to 945 employees in 2025. Other expense multiplied by 35.61 percent in 2025 due to increased profit related provisioning.
Other income posted a staggering 221.92 percent growth in 2025 due to gain recognized on the redemption of short-term investments at FVTPL followed by gain on disposal of property, plant & equipment and scrap sales, CHCC posted 27 percent rebound in its operating profit in 2025 with OP margin picking up to 35.65 percent.
Finance cost dwindled by 57.15 percent in 2025 due to monetary easing and early payment of long-term loans. This resulted in a much lower gearing ratio of 15.15 percent recorded in 2025.
CHCC’s net profit posted year-on-year recovery of 57.85 percent to clock in at Rs.8681.36 million. This translated into EPS of Rs.44.68 and NP margin of 22.96 percent in 2025.
Recent Performance (2026)
In 2026, CHCC registered 3.51 percent year-on-year plunge in its net sales which clocked in at Rs.36,482.81 million. While local dispatches increased by 9 percent, the decline was the result of 57 percent thinner export sales due to the closure of Afghan border.
Overall dispatches dipped by 1.75 percent to clock in at 2,348,405 tons in 2026. Higher coal prices and less favorable fuel mix resulted in 2.51 percent uptick in cost of sales in 2026 despite weaker topline. This resulted in 13.79 percent diminution in gross profit in 2026 with GP margin falling down to 33 percent. Higher petroleum prices and increased local dispatches resulted in 6.65 percent spike in distribution expense in 2026.
Administrative expense also spiked by 15.52 percent in 2026 due to inflationary pressure. This was despite the fact that the company streamlined its workforce from 945 employees in 2025 to 935 employees in 2026.
Lower profit related provisioning was the cause of 9.53 percent plunge in other expense in 2026. Conversely, other income strengthened by 11.25 percent in 2026 due to gain recognized on short-term investments and effect of discounting.
CHCC’s operating profit plummeted by 13.63 percent in 2026 with OP margin falling down to 31.91 percent. Huge repayments of outstanding loan and lower discount rate for most part of the year enabled the company to squeeze its finance cost by 42.27 percent in 2026. Gearing ratio also fell from 15.15 percent in 2025 to 6.90 percent in 2026.
CHCC registered net profit of Rs.7254.568 million in 2026, down 16.44 percent year-on-year. This translated into EPS of Rs.37.34 and NP margin of 19.88 percent in 2026.
Future Outlook
PSDP, CPEC and other government related projects are expected to gain momentum and support local sales volumes in the coming year. Moreover, infrastructure spending in the flood affected regions will also shape local demand.
The planned addition of 5.4 MW in the CHCC’s solar power capacity and 25 MW in battery energy storage system (BESS) capacity will improve its power generation profile which alongside incremental power package for industries will result in optimization of CHCC’s energy cost.
Recently, CHCC has notified via PSX notice of its intention to acquire at least 30 percent shares of Nimir Industrial Chemicals Limited (NICL). This will diversify CHCC’s sources of income.

























Comments