


Pakistan National Shipping Corporation: performance and outlook
PNSC, Pakistan's national shipping carrier, saw fluctuating financial performance from 2020-2026, with recent strong growth driven by fleet expansion and geopolitical factors. A major NLC acquisition is planned.
- PNSC's detailed financial performance and revenue drivers from 2020-2026.
- Impact of geopolitical tensions and fleet expansion on company growth.
- Proposed acquisition of PNSC by National Logistics Corporation (NLC).

Pakistan National Shipping Corporation (PSX: PNSC) is a national carrier of Pakistan. It is engaged in the transportation of dry bulk and liquid cargos across the globe. PNSC operates under the control of Ministry of Maritime Affairs, Government of Pakistan.
The company manages a fleet of 12 ships with a carrying capacity of 938,876 tons of deadweight. Besides, PNSC also has a real estate business and a repair workshop.
Pattern of Shareholding
As of June 30, 2026, PNSC has a total of 198.095 million shares outstanding which are held by 17,022 shareholders. Director General Port & Shipping has the majority stake of 87.56 percent in PNSC followed by local general public holding 6.18 percent shares.
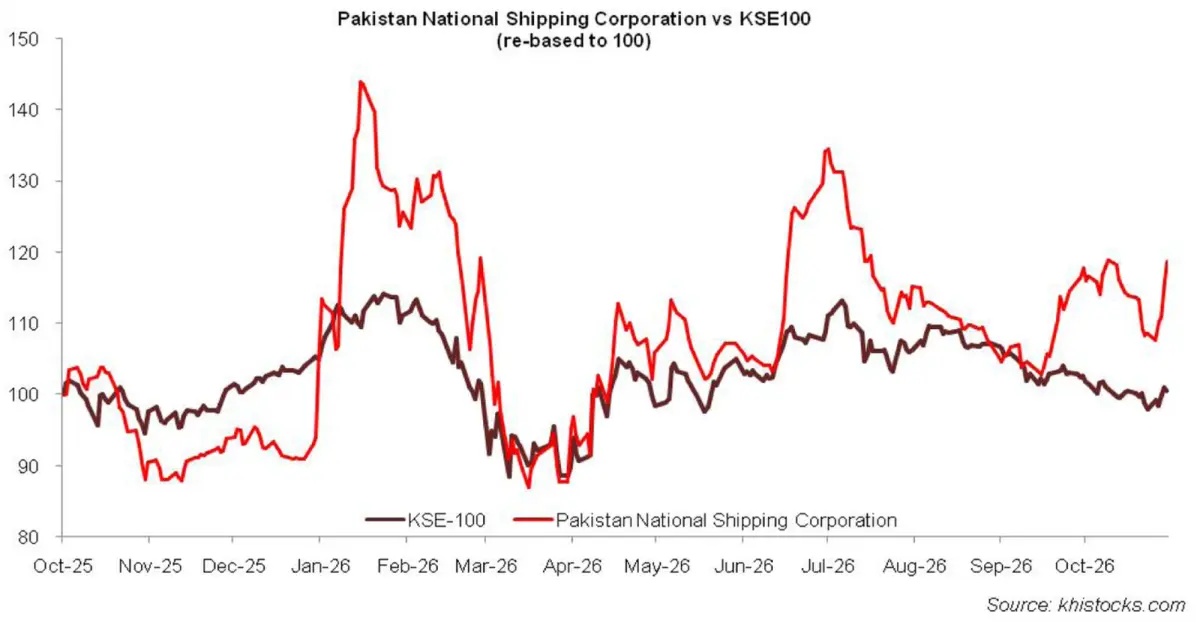
Associated companies, undertakings and related parties account for around 2.14 percent stake in the company. The remaining shares are held by other categories of shareholders.
Historical Performance (2020-26)
Over the period under consideration, PSNC’s topline posted a decline in 2021, 2024 and 2025. Its bottomline slid in 2021 and 2024. PNSC’s margins mounted until 2020 (except for a decline in net margin in 2020) followed by a plunge in 2021. In the subsequent two years, the margins gained back their momentum.
In 2024, all the margins plummeted. In 2025, gross margin continued to slide while operating and net margins rebounded. Conversely, in 2026, gross margin strengthened while operating and net margins deteriorated. The detailed performance review of the period under consideration is given below.
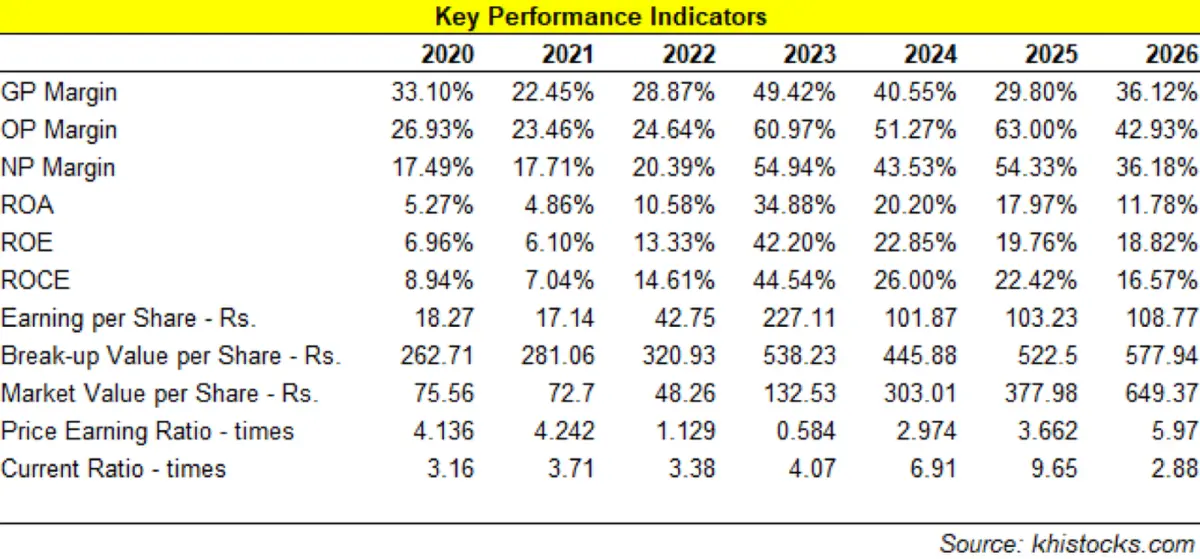
In 2020, PNSC boasted a year-on-year growth of 21.20 percent in its topline which clocked in at Rs.13,803.58 million. This came on the back of improved revenue from oil tankers which grew by 67 percent year-on-year in 2020. Revenue from bulk carriers, on the other hand, dropped by 14 percent year-on-year during the year. The chartered segment also remained lackluster registering a plunge of 53 percent year-on-year in 2020.
Rental income remained buoyant and rebounded by 35.24 percent year-on-year during 2020. PNSC posted GP margin of 33.10 percent in 2020 as against GP margin of 27.33 percent posted in 2019. In absolute terms, gross profit strengthened by 46.80 percent in 2020. This was because of improved performance of tanker segment which formed the largest chunk of PNSC’s sales mix. The decline in indirect fleet expense and real-estate expense in 2020 also contributed in pushing the GP up in 2020.
Administrative expense remained largely intact in 2020. Other expense posted a decline of 8.64 percent in 2020 on the back of lesser employees’ compensated absences, no loss recognized on the revaluation of long-term investments and no loss incurred on the sale of bunker.
Other income dipped by 24.61 percent in 2020 primarily on account of considerably lower exchange gain and lesser liabilities written back during the year. Impairment loss on financial assets surged by 608.38 percent in 2020.
PNSC was able to post OP margin of 26.93 percent in 2020 as against OP margin of 25.50 percent in the previous year as it kept a check on its administrative expenses. 152.24 percent higher finance cost incurred in 2020 was the result of elevated discount rate in the first three quarters of 2020.
Conversely, debt-to-equity ratio fell from 28 percent in 2019 to 21 percent in 2020. PNSC posted net profit of Rs.2413.88 million in 2020, up 10 percent year-on-year. This translated into EPS of Rs.18.27 in 2020 versus EPS of Rs.16.62 registered in 2019, NP margin fell from 19.27 percent in 2019 to 17.49 percent in 2020.
2021 was characterized by a 7.35 percent year-on-year drop in PNSC’s revenue which clocked in at Rs.12,788.56 million. 2021 presented a contrasting story when compared to the previous year. In 2021, oil tanker segment didn’t perform well and slid by 18 percent. This was on account of lesser fuel consumption across the globe owing to lockdown and related restrictions which adversely affected the road transport and aviation sectors.
Bulk carriers and chartered segment significantly improved during the year, however, couldn’t offset the plunge in the oil tanker segment. Rental income also fell by 3.27 percent year-on-year in 2021.
During the year, the company recognized massive revenue to the tune of Rs.548.58 million from other operating activities, especially demurrage income. GP margin slid to 22.45 percent in 2021, down from GP margin of 33 percent posted in the previous year. In absolute terms, gross profit also shrank by 37.15 percent in 2021.
PNSC kept a check on its operating expense and other expense in 2021 and also booked a reversal worth Rs. 285.27 million on financial assets as against impairment loss booked in the previous year. Despite that, operating profit dropped by 19.30 percent year-on-year in 2021 with OP margin slipping to 23.46 percent.
A significant 50.89 percent year-on-year drop in finance cost in 2021 was due to low discount rate and a drop in the debt-to-equity ratio to 16 percent. Net profit tapered off by 6.17 percent to clock in at Rs.2265.03 million in 2021. This translated into EPS of Rs.17.14 and NP margin of 17.71 percent in 2021
2022 proved to be the most vigorous year for PNSC as its shipping, rental and other operating business, all boasted a massive jump. Its overall revenue mounted by 116.71 percent to clock in at Rs. 27,714.20 million in 2022. Within the shipping segment, oil tanker segment boasted a major 52 percent year-on-year growth in revenue while the foreign chartered segment grew by over 800 percent to clock in at Rs.7019 million.
Other operating income also grew by 611.43 percent to clock in at Rs.3902.76 million in 2022 on the back of demurrage income. Gross profit improved by 178.63 percent in 2022. GP margin also surged to 28.87 percent in 2022 after witnessing a dip in the year.
The company booked a massive impairment loss of Rs.929.53 million its financial assets during the year, especially on trade debts. Other expenses also grew by 95.39 percent year-on-year in 2022 particularly on account of provision booked on slow moving stores and spares. However, other income performed well on account of high discount rate which boosted income from saving accounts and term deposits. Moreover, depreciation of Pak Rupee also resulted in sizeable exchange gain for the company.
Operating Profit multiplied by 127.61 percent in 2022 with OP margin growing to 24.64 percent. Finance cost dropped by 4.83 percent in 2022 despite higher discount rate. This was because the company was continuously squeezing its debt-to-equity ratio which stood at 11 percent in 2022.
Net profit picked up by 149.44 percent to clock in at Rs.5649.89 million in 2022 with EPS of Rs.42.75 and NP margin of 20.39 percent.
In 2023, PNSC’s total revenue strengthened by 97 percent to clock in at Rs.54,597.18 million.
Revenue from shipping business, other activities and rental income, all posted considerable improvement during the year. The star performer during the year was liquid cargo segment (crude oil and refined oil). The demand was influenced by Russia-Ukraine crisis which created supply chain impediments and heightened demand for shipping services. During the year, the company added two AFRAMAX tankers to its fleet.
Total expense grew by 40 percent in 2023 due to increase in the number of vessels and resultant increase in the number of voyages by 12. Gross profit picked up by 237.23 percent in 2023 with GP margin attaining its optimum level of 49.42 percent. Administrative expense hiked by 32.19 percent during the year particularly on the back of higher payroll expense, general establishment as well as legal & professional charges incurred during the year.
The company expanded its workforce from 642 employees in 2022 to 680 employees in 2023. Impairment loss also spiked by 20.81 percent in 2023. Other expense ticked up by 6.12 percent in 2023 due to greater provisioning done for WPPF and higher employees’ gratuity.
Other income did exceptionally well during the year boasting 579.45 percent year-on-year growth. This was the consequence of gain recognized on the disposal of a vessel, massive exchange gain and greater profit from saving accounts and term deposits. PNSC’s operating profit multiplied by 387.53 percent in 2023 with OP margin jumping up to 60.97 percent.
Finance cost escalated by 165.90 percent in 2023 due to monetary tightening and increased financing. Despite greater outstanding liabilities, higher equity due to increased revenue reserves resulted in a lower debt-to-equity ratio of 10 percent in 2023. Net profit registered 430.88 percent year-on-year surge to clock in at Rs.29,994.30 million in 2023. This translated into EPS of Rs.227.11 and NP margin of 54.94 percent in 2023.
After two successive years of posting tremendous topline and bottomline growth, PNSC registered year-on-year decline of 15 percent in its revenue which clocked in at Rs.46,363.49 million in 2024. While rental income ticked up by 8.48 percent in 2024, income from shipping business and other operating activities (demurrage income) dipped by 13.20 percent and 28.50 percent respectively. This was largely due to high-base effect as the company experienced exceptionally high demand in the previous year due to Russia-Ukraine crisis.
Despite massive decline in revenue, total expenses remained largely intact in 2024 owing to higher depreciation expense from capitalizing dry-docking expense, greater repair & maintenance cost owing to aging fleet and upward revision in the salaries of afloat officers and staff salaries and linking it to USD in alignment with global standards. This resulted in 30.31 percent decline in gross profit in 2024 with GP margin sliding down to 40.55 percent.
Administrative expense surged by 24.58 percent in 2024 due to increment in salaries. This was despite the fact that the workforce was squeezed from 680 employees in 2023 to 663 employees in 2024. Impairment loss on financial assets plunged by 84.57 percent in 2024. Other expense didn’t give any respite and surged by 67.56 percent in 2024 due to higher provisioning done for WPPF and unrealized exchange loss recorded during the year. Other income deteriorated by 16.73 percent in 2024 due to high-base effect as the company recorded gain on disposal of vessel and unrealized gain on the revaluation of foreign currency balances in the previous year.
Operating profit dwindled by 28.58 percent in 2024 with OP margin falling down to 51.27 percent. Finance cost tapered off by 28 percent in 2024 despite monetary tightening. This was due to settlement of outstanding liabilities which led to debt-to-equity ratio shrinking to 3 percent in 2024.
Net profit went downhill by 32.71 percent to clock in at Rs.20,181.74 million in 2024. This translated into EPS of Rs.101.87 and NP margin of 43.53 percent in 2024.
In 2025, PNSC’s revenue dropped by 18.82 percent to clock in at Rs.37,637.42 million. Except rental income, the other two sources of revenue – shipping business and other operating activities posted decline in 2025. During the year, two of the company’s vessels – MT Lahore and MT Quetta – were disposed off.
While the company met its commitments by deploying charter vessels, however, low margins of charter vessels took its toll on the overall profitability of the company. Besides, the company experienced significant off-hire, idle days and repair days which affected its utilization, however, was essential for its long-term operational efficiency.
Total expense plummeted by 4.13 percent in 2025 due to lower fleet expenses after the sale of two vessels during the year. Gross profit diminished by 40.35 percent in 2025 with GP margin drastically falling to 29.80 percent.
Administrative expense ticked up by 3.47 percent in 2025 due to increased amortization, depreciation and sales tax expense and workshop management charges incurred during the year. After three years of booking impairment loss on its financial assets, PNSC recorded a reversal of Rs.1833.92 million in 2025. Other expense dropped by 31.60 percent in 2025 due to no unrealized exchange loss recorded.
Other income picked up by 67.73 percent in 2025 particularly due to capital gain on mutual funds, gain on disposal of vessels, unrealized gain on the revaluation of foreign currency balances, liabilities no longer payable written off as well as insurance claim income recorded during the year.
PNSC’s operating profit ticked down by a paltry 0.26 percent in 2025, however, its OP margin attaining its optimum level of 63 percent. Finance cost shrank by 57.59 percent in 2025 due to monetary easing and decline in outstanding debt obligations. Debt-to-equity ratio slipped to 2 percent in 2025. PNSC’s net profit inched up by 1.32 percent to clock in at Rs.20,448.74 million in 2025. This translated into EPS of Rs.103.23 and NP margin of 54.33 percent in 2025.
In 2026, PNSC posted a splendid 58.21 percent increase in its total revenue which clocked in at Rs.59,547.449 million. All three sources of income registered growth during the year. Freight revenue continued to be the star contributor to the overall revenue of PNSC in 2026 followed by Add-war risk income. During the year, the company acquired three new vessels from international market and also placed an order for a new container vessel locally with Karachi Shipyard & Engineering Works.
The company carried 13.18 million tons of cargo in 2026, up 20.37 percent year-on-year. PNSC ensured continuous supply of crude oil and refined petroleum products to Pakistani refineries despite regional tensions and blockage of critical chokepoints.
Revenue from dry cargo increased by 10 percent while liquid cargo segment registered 59 percent growth in revenue in 2026. Total expense surged by 43.97 percent in 2026 on the back of 44.35 percent spike in fleet expense while real estate expense tapered off by 14.35 percent in 2026. Greater fleet expense was due to charter hire and related expense and also because of greater diesel, fuel and lubricant charges incurred during the year.
Gross profit strengthened by 91.77 percent in 2026 with GP margin climbing up to 36.12 percent. Administrative expense ticked up by 4.51 percent in 2026 due to higher payroll expense and legal & professional charges incurred.
Number of employees was reduced from 636 in 2025 to 620 in 2026. Reversal of impairment loss on financial assets plunged by 90.29 percent in 2026. Other expense escalated by 70.50 percent in 2026 largely on the back of realized and unrealized exchange loss and provisioning done for damage claims and slow-moving stores and spares.
Other income deteriorated by 47.77 percent in 2026 due to thinner interest income, lesser capital gain on mutual funds and a decline in gain on disposal of fixed assets. PNSC registered 7.81 percent uptick in its operating profit in 2026 with OP margin falling down to 42.93 percent.
Finance cost spiked by 437.63 percent in 2026 due to greater outstanding liabilities on account of fleet expansion. Net profit improved by 5.37 percent to clock in at Rs.21,546.96 million in 2026. This translated into EPS of Rs.108.77 and NP margin of 36.18 percent in 2026.
Recent Performance (1QFY27)
During the first quarter of the ongoing fiscal year, PNSC registered a massive 107.37 percent growth in its total revenue which clocked in at Rs.21,290.184 million. All three sources of revenue – shipping business, rental income and other operating activities – posted growth during the period under review. The liquid cargo was the key revenue driver during the period under review driven by geopolitical tensions.
The timely induction of three new vessels and favorable freight rates in the international market enabled the company to take optimum benefit of the favorable market conditions.
Gross profit strengthened by 226.65 percent in 1QFY27 with GP margin clocking in at 50.66 percent versus 32.16 percent in 1QFY26. Administrative expense inched up by 5.30 percent in 1QFY27 largely on the back of greater payroll expense. PNSC booked impairment loss of Rs.41.38 million in 1QFY27 versus reversal of impairment loss worth Rs.68.68 million recorded in 1QFY26.
Other expense ticked down by 6.26 percent in 1QFY27, likely due to lesser provisioning done during the period. Other income also deteriorated by 26.23 percent in 1QFY27 due to lesser return on short-term investments and thinner dividend income. PNSC recorded 156.28 percent stronger operating profit in 1QFY27 with OP margin clocking in at 53.24 percent versus 43 percent in 1QFY26. Finance cost mounted by a massive 2268.83 percent in 1QFY27 due to investment in new vessels.
The company recorded net profit of Rs.9833.336 million in 1QFY27, up 164.71 percent year-on-year. This translated into EPS of Rs.49.64 and NP margin of 46.19 percent in 1QFY27 versus EPS of Rs.18.75 and NP margin of 36.18 percent recorded in 1QFY26.
Future Outlook
Geopolitical tensions offer both risk and opportunities for the shipping business. The long-term outlook of the company will be supported by fleet expansion, rising shipping volumes and Pakistan’s growing participation in seaborne trade. Key risks include international freight rate volatility and higher finance cost.
As per the notice issued on the Pakistan Stock Exchange, PNSC has received a letter from the Ministry of Maritime Affairs regarding the proposed acquisition of a 29.5 percent stake in PNSC by National Logistics Corporation (NLC), along with the proposed transfer of management control.
The proposal was approved by the ECC and the Federal Cabinet. This is a government-led restructuring initiative aimed at integrating Pakistan’s shipping and land-based logistics operations. The acquisition will also be beneficial for PNSC as it will result in stronger operational coordination, fleet expansion and modernization as well as increased cargo volumes and revenue.


















Comments