


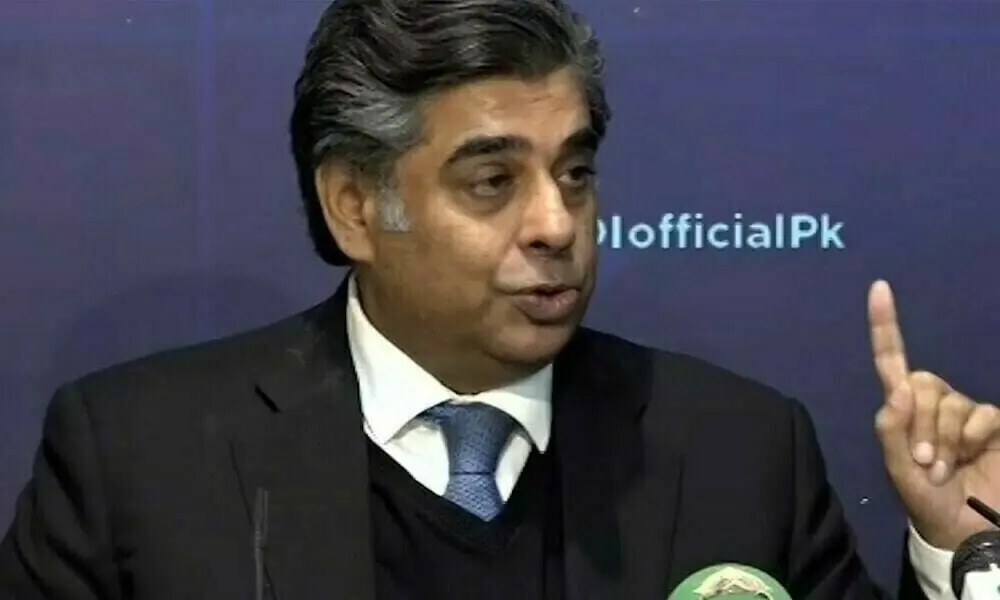

Former caretaker federal minister Gohar Ejaz on Wednesday questioned the effectiveness of monetary tightening in tackling Pakistan’s fuel-driven inflation, arguing that raising interest rates would only inflate debt servicing costs without addressing the root causes of price pressures.
Earlier this week, the State Bank of Pakistan (SBP) increased the policy rate by 100 basis points (bps) to 11.50% in its third Monetary Policy Committee (MPC) meeting of 2026. This was the central bank’s first hike in almost three years.
However, Gohar Ejaz said the increase in the policy rate could not influence international fuel prices, which “remain the primary driver of domestic inflation amid ongoing global conflicts and supply disruptions”.
Citing the views of Nobel laureate Joseph Stiglitz, Ejaz stressed that supply-side shocks, particularly those stemming from global commodity and energy markets, were not effectively managed through higher interest rates.
“Monetary tightening cannot bring down imported inflation,” he said, adding that such policies risk suppressing economic activity without delivering meaningful relief to consumers.
He questioned whether the SBP decision to hike rates could either reduce fuel consumption significantly or alter international pricing dynamics, arguing that the answer in both cases was “clearly no”.
Highlighting the fiscal consequences, Ejaz warned that every one percent increase in borrowing costs adds approximately Rs600 billion to the government’s annual interest payments.
“At a time when debt servicing is already projected to exceed Rs8 trillion this fiscal year, such policy moves will only deepen fiscal stress,” he noted.
Ejaz further cautioned that the ballooning cost of debt would inevitably translate into additional taxation, placing a heavier burden on citizens already grappling with high inflation and stagnant incomes.
“This is not just a monetary issue—it is a fiscal and structural crisis.”
He urged policymakers to rethink the reliance on interest rate hikes as a primary tool for inflation control and instead focus on supply-side interventions, energy reforms, and measures to enhance domestic production.
“Without addressing structural inefficiencies and external vulnerabilities, tightening monetary policy will only exacerbate the economic slowdown,” the former caretaker minister said.
























Comments