


Citi Pharma Limited: performance and outlook
Citi Pharma Limited (CPHL) demonstrated steady financial growth from 2021-2025, navigating market challenges and expanding operations, with strong recent performance and strategic future plans.
- CPHL's financial performance and margin trends from 2021 to 2025.
- Strategic expansions, international partnerships, and recent acquisition plans.
- Key factors impacting sales growth, costs, and profitability.

Citi Pharma Limited (PSX: CPHL) was incorporated in Pakistan as a private limited company in 2012 and was converted into public unlisted company in 2020. CPHL was listed on Pakistan Stock Exchange in 2021. The company is engaged in the manufacturing and sale of pharmaceuticals, medical chemicals and botanical products.
Pattern of Shareholding
As of June 30, 2025, CPHL has a total of 228.46 million shares outstanding which are held by 16,456 shareholders.
Local general public has a majority stake of 54.18 percent in the company followed by Directors, CEO, their spouse and minor children holding 38.66 percent shares of CPHL.
Modarabas & Mutual Funds account for 2.23percent shares of CPHL while joint stock companies hold 1.97 percent shares. The remaining shares are held by other categories of shareholders.
Financial Performance (2021-25)
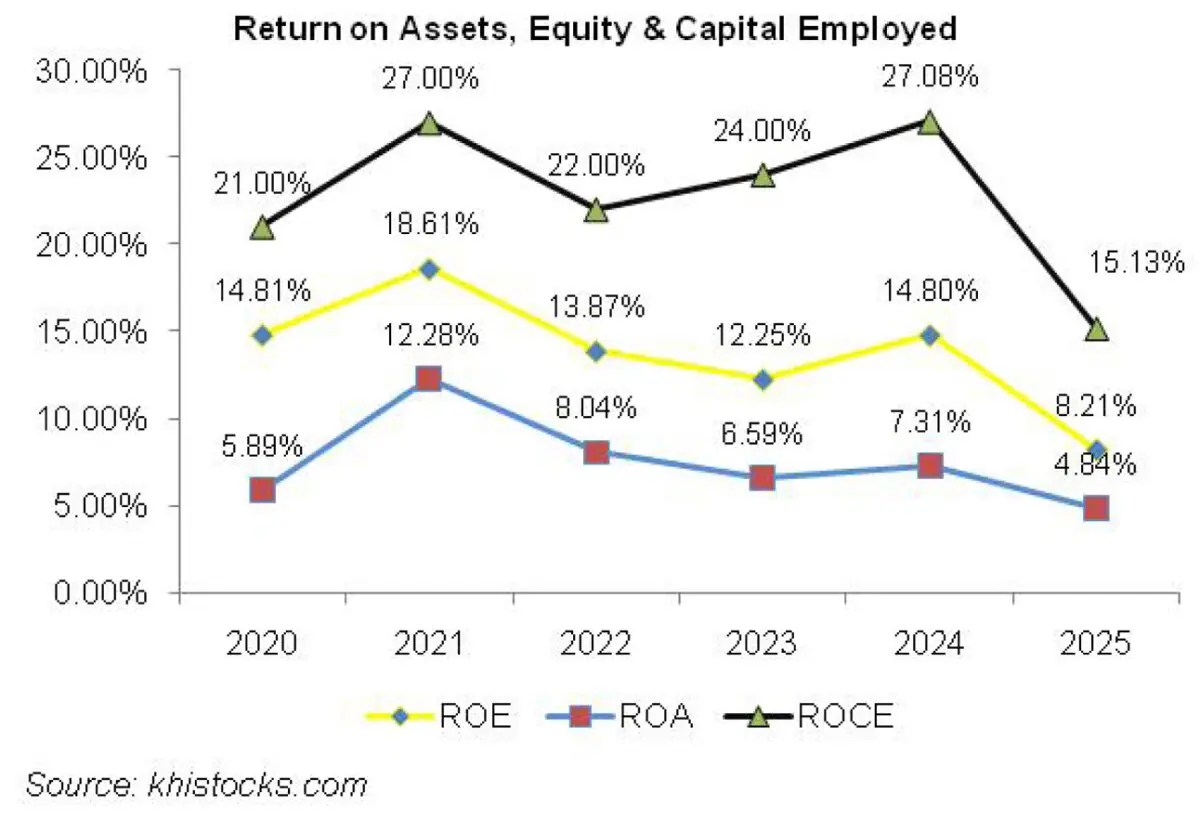
CPHL’s topline and bottomline posted steady growth over the period under consideration. Its margins followed an upward trajectory until 2022 followed by a plunge in 2023. In the following years, margins picked up yet again and attained their optimum level in 2025. The detailed performance review of the period under consideration is given below.
In 2021, CPHL’s topline grew by 64.29 percent year-on-year to clock in at Rs.5795.40 million. This was because the demand for Paracetamol rose due to COVID-19. Cost of sales grew by 62.26 percent in 2021 on the back of increase in the prices of raw materials internationally coupled with Pak Rupee depreciation.
Gross profit multiplied by 78.62 percent in 2021 with GP margin clocking in at 13.47 percent versus GP margin of 12.39 percent recorded in 2020. Administrative expense surged by 17 percent in 2021 as the company expanded its workforce from 420 employees in 2020 to 573 employees in 2021.
Many BMR projects were underway during the year including the expansion of Paracetamol plant, building three manufacturing facilities in the formulation segment and constructing a dedicated line in Active Pharmaceutical Ingredients (API) manufacturing to eliminate the chances of cross contamination.
During 2021, distribution expense also escalated by 11.95 percent due to higher courier expense as well as elevated advertising & marketing budget. 133.15 percent higher other expense incurred during the year was on account of higher profit-related provisioning. Other income slid by 35.40 percent in 2021 due to lower profit on saving accounts and a dip in the amortization of grant income.
Operating profit improved by 119.32 percent in 2021 with OP margin standing at 9.33 percent versus OP margin of 7 percent recorded in 2020. CPHL’s finance cost inched down by 7.17 percent in 2021 on account of monetary easing. Net profit grew by 145.28 percent year-on-year in 2021 to clock in at Rs.351.769 million.
CPHL recorded EPS of Rs.31.87 in 2020 which drastically fell to Rs.2.07 in 2021 on the back of split of share price from Rs.100 to Rs.10 and also because of issuance of 200 percent bonus shares during the year. NP margin stood at 6.07 percent in 2021 versus NP margin of 4.07 percent posted in 2020.
In 2022, CPHL registered 68.75 percent higher net sales to the tune of Rs.9779.88 million. Due to increased demand for Paracetamol, the company increased its annual capacity from 3600 tons to 5400 tons. During the year, cost of sales grew by 67.83 percent due to higher inflation and depreciating value of local currency.
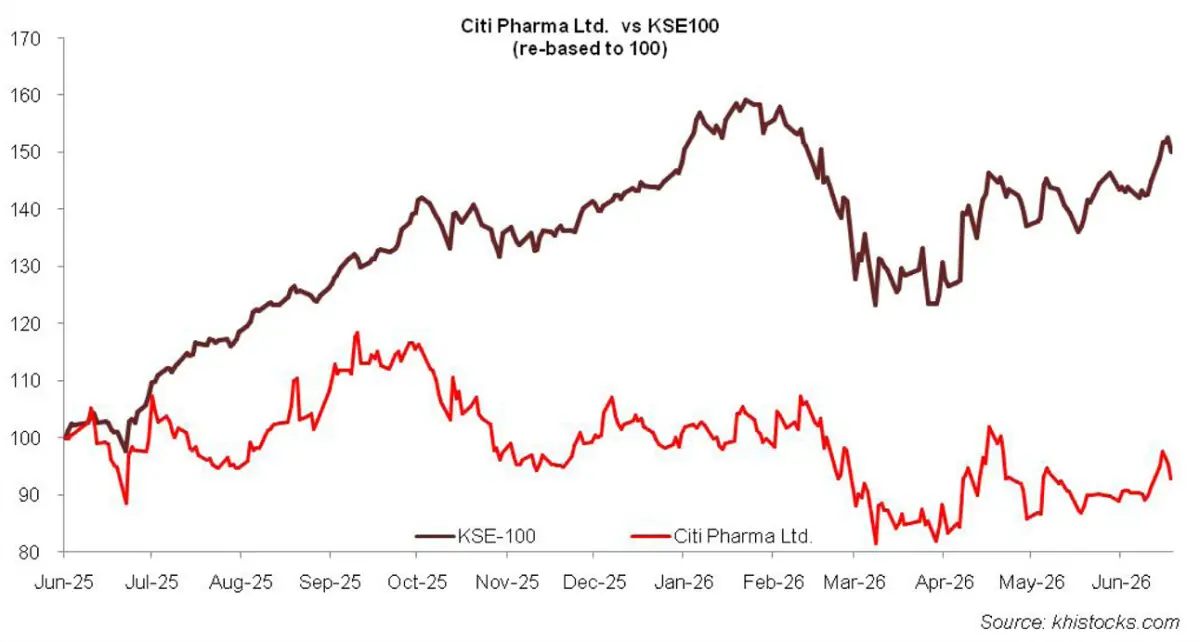
CPHL recorded 74.65 percent enhancement in its gross profit in 2022 with GP margin inching up to 13.94 percent. Administrative expense surged by 141.10 percent in 2022 due to listing expense as the company got listed on Pakistan Stock Exchange.
Besides, payroll expense also hiked during the year due to increase in the number of employees to 587 in 2022. Higher courier expense incurred during the year was somewhat offset by considerably lower advertising budget, resulting in a paltry 4.21 percent uptick in distribution expense in 2022.
Other expense multiplied by 163.74 percent in 2022 due to higher profit related provisioning. However, it was offset by 4692.90 percent higher other income recorded by CPHL in 2022 on the back of increased profit on TDRs and saving accounts. CPHL’s operating profit increased by 109.36 percent in 2022 with OP margin climbing up to 11.57 percent. Finance cost spiked by 74.21 percent in 2022 due to monetary tightening coupled with increased borrowings.
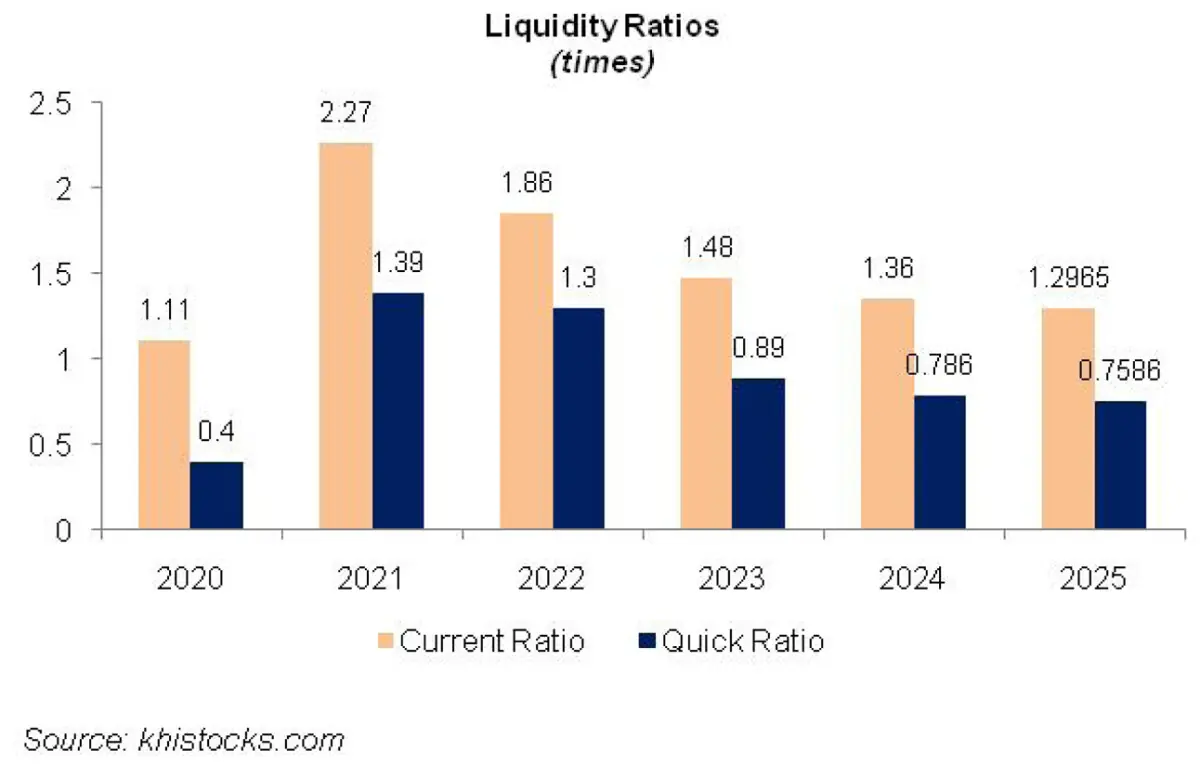
This drove up CPHL’s debt-to-equity ratio from 15 percent in 2021 to 21 percent in 2022. 10 percent super tax levied on pharmaceutical sector further diluted the bottomline growth which was recorded at 85.83 percent in 2022.
CPHL’s net profit stood at Rs.653.692 million in 2022 with EPS of Rs.2.88 and NP margin of 6.68 percent.
As the company got listed on PSX in 2022, it issued 72.69 million ordinary shares at the strike price of Rs.32 which included premium of Rs.22 per share.
CPHL’s topline grew by 26.76 percent in 2023 to clock in at Rs.12,396.98 million. This was due to increased demand. The company faced immense cost pressure due to drastic depreciation in the value of local currency, high indigenous inflation, commodity super cycle in the international market as well import restrictions imposed during the year.
Devastating floods in the southern region of the country at the onset of the financial year also created supply chain impediments. This resulted in GP margin falling down to 12.16 percent in 2023 despite 10.57 percent higher gross profit recorded during the year.
Administrative expense slid by 29.28 percent in 2023 due to high-base effect as the company paid listing charges of Rs.127.668 million in 2022. During the year, the company enhanced its workforce to 594 employees versus 587 employees in 2022.
CPHL’s distribution expense escalated by 46.59 percent in 2023 due to higher courier charges, marketing & advertising budget as well as payroll expense. Higher profit related provisioning and loss on investment in shares resulted in 24.93 percent higher other expense incurred in 2023. Other expense was offset by 26.42 percent higher other income recorded in 2023.
This was on account of higher profit earned on TDRs and mark-up on investment in Yaqeen Developers Limited, a related party of CPHL. Operating profit multiplied by 18.72 percent in 2023, however, OP margin fell to 10.84 percent. Finance cost surged by 443.71 percent in 2023 due to unprecedented discount rate as well as tremendous rise in working capital related borrowings during the year.
CPHL’s debt-to-equity ratio soared to 29 percent in 2023. This greatly diluted the bottomline growth which inched up by only 0.66 percent year-on-year in 2023 to clock in at Rs.657.984 million with EPS of Rs. 2.88 and NP margin of 5.31 percent.
CPHL’s net sales grew by a paltry 0.10 percent in 2024 to clock in at Rs.12,409.24 million. During the year, the company faced supply chain disruptions due to import restrictions. Demand also remained weak during the year due to inflationary pressure.
Cost of sales slid by 0.61 percent in 2024 particularly due to favorable movement in the value of local currency during the second half of FY24. This resulted in 5.25 percent uptick in gross profit with GP margin jumping up to 12.78 percent.
Administrative expense grew by 8.35 percent in 2024 primarily due to higher payroll expense which was the consequence of inflationary pressure as well as workforce enhancement from 594 employees in 2023 to 615 employees in 2024.
Distribution expense mounted by 16.66 percent in 2024 on account of higher delivery/courier expense, marketing & promotional charges as well as salaries of sales force. During the previous year, the company incurred loss on investment in shares which created high base for 2024. Hence, despite increased profit related provisioning done in 2024, CPHL recorded 1.73 percent downtick in other expense in 2024.
Conversely, other income strengthened by 67.57 percent in 2024 on the back of higher profit recognized on TDRs, mark-up on investment in Yaqeen Developers Limited, exchange gain, dividend income as well as realized and un-realized gain on investment in shares recorded during the year.
Operating profit picked up by 17.69 percent in 2024 with OP margin reaching its highest level of 12.74 percent. Despite monetary tightening, finance cost shrank by 22.35 percent in 2024 on account of settlement of long-term and short-term liabilities during the year.
Debt-to-equity ratio was recorded at 25 percent in 2024. Net profit grew by 26.67 percent in 2024 to clock in at Rs.833.463 million with EPS of Rs.3.65 and NP margin of 6.72 percent.
In 2025, CPHL recorded 6 percent uptick in its net sales which clocked in at Rs.13,153.52 million. This was due to increased demand on the back of growing population and rising health awareness. Increase in the prices of medicines after the pricing deregulation by the DRAP also buttressed the company’s topline in 2025.
Gross profit multiplied by 27.20 percent in 2025 with GP margin attaining its optimum level of 15.34 percent in 2025. Administrative expense spiked by 8.80 percent in 2025 mainly on account of elevated fee & subscription charges incurred during the year.
Distribution expense mounted by 8.41 percent in 2025 on account of higher delivery/courier expense, increased salaries of sales force and an upward adjustment in marketing/promotional budget.
Other expense ticked up by 3.62 percent in 2025 due to increased provisioning done for WWF, WPPF and CRF. Other income deteriorated by 59.51 percent in 2025 due to drastic fall in the profit from TDRs. During the year, the company’s short-term investments considerably shrank.
Operating profit posted 6.52 percent uptick in 2025 with OP margin recorded at 12.80 percent. Finance cost grew by 9.93 percent in 2025 due to considerable spike in short-term borrowings. This resulted in a drastic surge in debt-to-equity ratio which clocked in at 70 percent in 2025. CPHL’s net profit improved by 7 percent to clock in at Rs.892.039 million with EPS of Rs.3.90 and NP margin of 6.78 percent.
Recent Performance (9MFY26)
During the nine-month period of the ongoing fiscal year, CPHL recorded 6.81 percent year-on-year growth in its net sales which clocked in at Rs.10,787.56 million. This was on the back of demand growth, portfolio expansion, price revision and improved sales mix with greater contribution from formulation products.
Continuous improvement in its operational efficiency through expansionary projects resulted in 37.27 percent stronger gross profit in 9MFY26 with GP margin clocking in at 18.53 percent versus GP margin of 14.42 percent in 9MFY25. Administrative and distribution expense surged by 2.50 percent and 49 percent respectively in 9MFY26 due to enhancement in operations and sales volume.
Thinner short-term investments coupled with monetary easing were the causes of 52.15 percent decline in other income in 9MFY26. Other expense grew by 24 percent in 9MFY26, likely due to increased provisioning done for WWF, WPPF and CRF.
CPHL recorded 29.70 percent stronger operating profit in 9MFY26 with OP margin clocking in at 15.15 percent versus OP margin of 12.48 percent recorded in 9MFY25. Despite monetary easing, finance cost spiked by 21.83 percent in 9MFY26 due to increase in outstanding liabilities.
Net profit strengthened by 30.14 percent in 9MFY26 to clock in at Rs.883.44 million with EPS of Rs.3.87 versus EPS of Rs. 2.97 recorded in 9MFY25. NP margin ticked up from 6.72 percent in 9MFY25 to 8.19 percent in 9MFY26.
Future Outlook
CPHL is making relentless strides to enhance its sales volume and geographical presence besides focusing on cost reduction and R&D. The company has recently started the export of finished nutraceuticals in the US market which has opened up a fresh revenue stream for the company besides adding to its credibility subsequent to approval from FDA.
The company has also entered into a joint venture with Hangzhou Newsea Technology Co Ltd, a renowned player in the Chinese pharmaceutical industry to produce new APIs to enhance its product range. Besides, the company has entered into a strategic partnership with India’s Murli Krishna Pharma Private Limited for the supply of APIs.
CPHL is currently focusing on the completion and starting of its Bioequivalence and Research Center which will expedite its entry in regulated international markets.
Moreover, the company is actively looking for potential partners and distributors in the emerging markets to enhance its export potential. Furthermore, the company is also looking forward to formulating products to enhance livestock productivity and animal health.
On May 06, 2026, CPHL announced the approval of its plan to acquire 100 percent stake of Pakheim International Pharmaceuticals (Private) Limited. This will enhance the company’s product portfolio, manufacturing capacity and market presence besides creating operational synergies and supply-chain enrichment.




Comments