


Peshawar High Court takes notice of ‘coercive’ tax recovery measures, issues notice to FBR
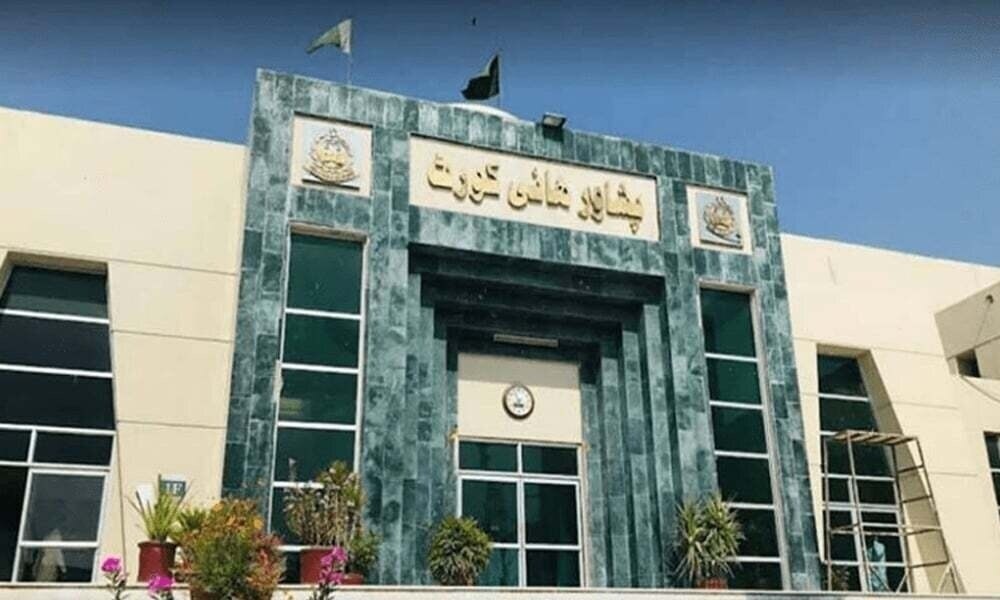

ISLAMABAD: Peshawar High Court has taken serious notice of alleged unlawful and coercive tax recovery measures adopted by the tax authorities, observing that the matter requires judicial consideration in light of settled law and constitutional safeguards provided in Pakistan LNG Limited case.
In a recent interim relief order, PHC suspended the operation of factory and bank attachment notices and issued notice to the Federal Board of Revenue (FBR) for filing of comments.
Abbottabad: DG I&I IR Peshawar officers can’t recover ST liabilities: PHC
It is reliably learnt that counsel for the petitioner contended that the respondents had illegally resorted to coercive recovery of an alleged tax demand in blatant violation of Sections 138 and 140 of the Income Tax Ordinance, 2001. It was further argued that such actions were in clear disregard of the mandatory requirements of due process of law, as guaranteed under Article 10-A of the Constitution.
The petitioner’s counsel placed reliance on the judgment in Pakistan LNG Limited v. FOP (2022 PTD 1763), which has subsequently been upheld by the Supreme Court of Pakistan in Pakistan LNG Limited v. FOP (2025 SCP 267), to assert that coercive recovery without lawful authority and adherence to due process is impermissible. After hearing the submissions, the Court observed that the points raised merit consideration.
Accordingly, notice has been issued to the respondents, directing them to submit their para-wise comments within a period of a fortnight.
Copyright Business Recorder, 2025




















Comments
Comments are closed for this article.