


EDITORIAL: Privatisation is meant to attract capital, not deter it
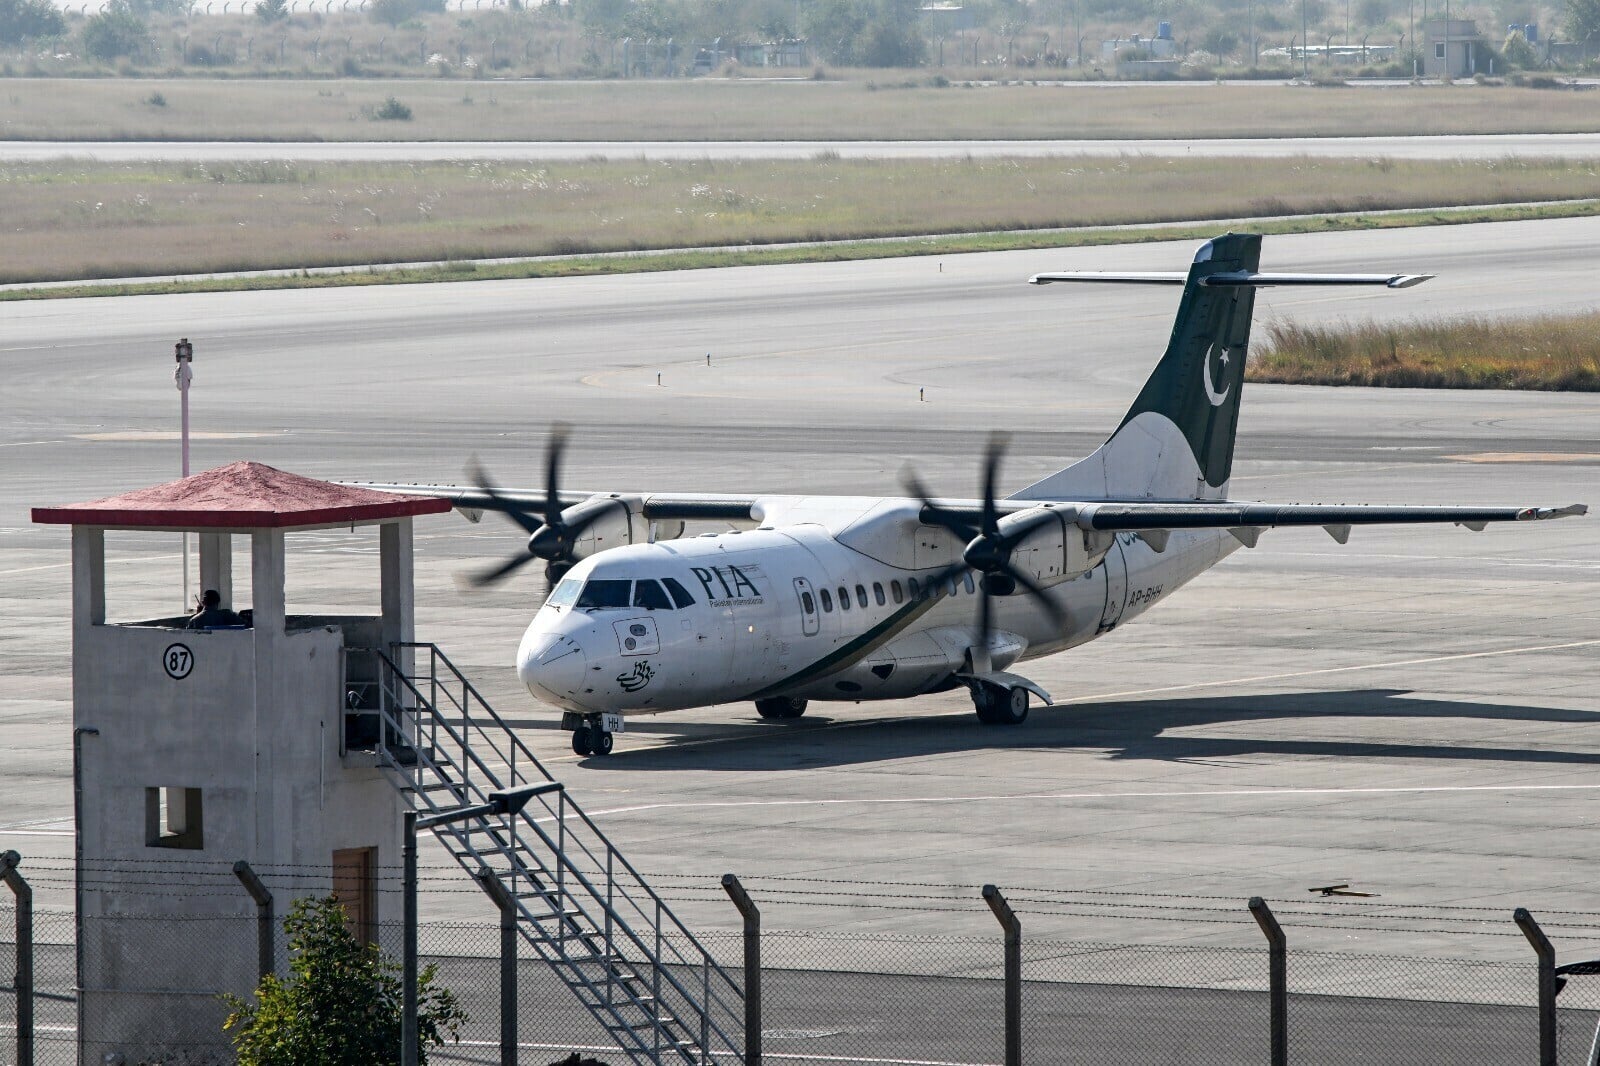
EDITORIAL: It says something about the state of public sector reform that the country’s flagship privatisation has entered a phase where confidence and uncertainty sit side by side.
The government is presenting the selloff of Pakistan International Airlines (PIA) as a decisive step toward financial rehabilitation, yet senior officials have acknowledged that investors will not receive guarantees. It is difficult to imagine a more contradictory approach.
Privatisation is meant to attract capital, not deter it, and in a sector already scarred by decades of mismanagement, the absence of assurances will test even the most optimistic bidders.
The government insists that the process is moving forward. The prime minister was briefed on a timetable that puts PIA’s privatisation on track for completion and on a plan to sell 75 percent of the airline’s shares. Officials spoke of a transformational business plan, with the fleet targeted to expand from 18 to 38 aircraft by 2029 and the route network from over 30 cities to more than 40. Four investors have been pre-qualified, and the administration is projecting confidence about the next phase.
The prime minister called for transparency and urged officials to address long-standing operational weaknesses. The statements reflect an attempt to show clarity and resolve, as usual.
Yet the broader context, as outlined by the chairman of the privatisation commission only a few days earlier, suggests that the optimism is masking deeper concerns. Investors are being told that guarantees will not be offered, even though the government acknowledges that its own governance gaps, corruption, and economic weaknesses have eroded its bargaining position. When the state’s ability to negotiate is this constrained, and when past divestments have been marred by inadequate due diligence, the refusal to provide comfort to buyers becomes a far more serious issue.
The chairman has been frank about the leverage major powers enjoy in government-to-government transactions, and has argued that Pakistan should avoid such arrangements where possible in favour of competitive and transparent procedures. The irony is that transparency is exactly what has been missing from many sales attempts.
The contradiction is hard to ignore. If the government believes the airline can attract credible bidders under open market conditions, it must also recognise that investors will judge the risks without sentiment. A privatisation of this scale, in a climate where the government itself admits to limited leverage, cannot rely solely on encouraging language.
The absence of guarantees is likely to cast a shadow over the process, and while the removal of sales tax on the transaction may help, it does not address the concerns about regulatory consistency or long-term policy support. These are the factors private capital weighs most heavily.
It is also worth asking why alternative approaches have not received more attention. The chairman has pointed to examples abroad where privatisation was undertaken through transparent capital market placements, yet there is little indication that such models are being seriously considered. A stock market route would broaden the investor base, reduce political exposure, and impose disclosure obligations that strengthen credibility.
Instead, the government appears committed to a narrower process that risks repeating the shortcomings of past attempts. The reluctance to embrace more transparent options raises questions about political will and about whether the state is prepared to relinquish the discretionary control that often enables inefficiency and misuse.
The underlying problem is not limited to PIA. Almost all State Owned Enterprises (SOEs) have been draining public finances since forever because governance standards are weak and because opaque structures create opportunities that do not align with public interest. When officials speak of the need to modernise PIA and improve punctuality, they are acknowledging symptoms rather than causes.
Corruption is the fundamental issue, and the chairman’s remarks about governance gaps make that clear. Removing guarantees may align with fiscal caution, but without parallel reforms in oversight and policy coherence, the decision risks becoming another example of a difficult reform attempted without the institutional clarity to support it.
Privatisation is not simply a transaction. It is a test of whether the state can create an environment where private capital sees stability rather than uncertainty. For PIA, the government’s mixed signals are undermining its own objective. A transparent, credible process remains the only path to success. The alternative is another cycle of expectations raised and then quietly abandoned when the realities of governance overwhelm the rhetoric.
Copyright Business Recorder, 2025


























Comments
Comments are closed for this article.