



Pakistan’s listed oil and gas exploration and production (E&P) sector started FY27 on a stronger note, supported by higher international oil prices, improved hydrocarbon production and better gas price realisations. However, the recovery remains uneven, while rising exploration costs, maturing fields and persistent circular debt-related receivables continue to pose challenges.
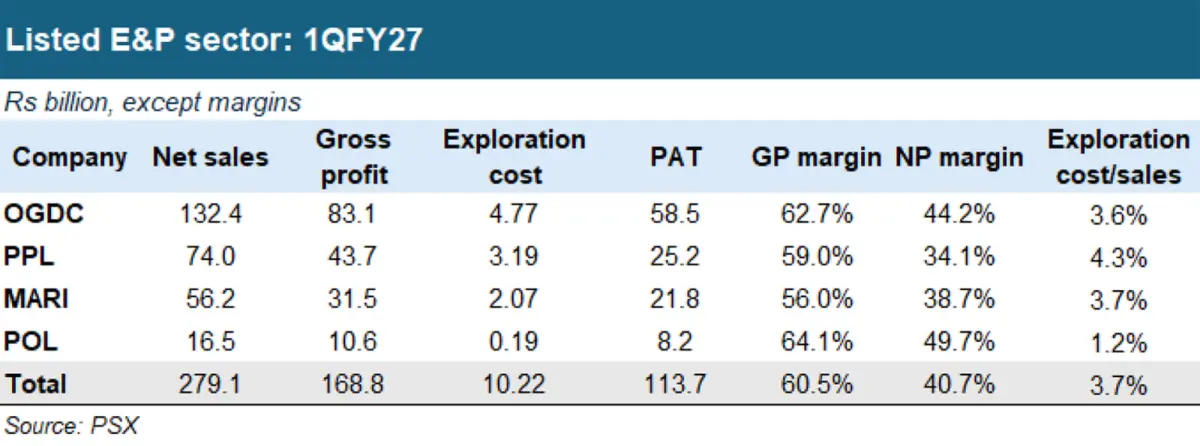
The four major listed E&P companies—OGDC, PPL, Mari Energies (MARI) and Pakistan Oilfields (POL)—reported combined profit after tax (PAT) of Rs113.7 billion in 1QFY27, up 43 percent year-on-year. Net sales increased by 32 percent to Rs279 billion, while gross profit rose by 35 percent to Rs169 billion. The sector’s gross margin stood at 60.5 percent, while net margin reached 40.7 percent.
The improvement was largely driven by favourable pricing. Average international crude oil prices increased by 26 percent year-on-year to around $90 per barrel, while revised wellhead gas prices provided additional support. Higher production volumes also contributed, with national oil output increasing by 10 percent and gas production rising by 6 percent during the quarter.
Operationally, the quarter showed encouraging signs. OGDC recorded 13 percent growth in oil production and 17 percent in gas, supported by incremental output from newer fields. PPL also benefited from higher production, while MARI’s gas output increased by 7 percent. POL recorded a 27 percent increase in gas production, although its oil output declined by 5 percent.
Company-wise, OGDC remained the largest contributor, accounting for more than half of sector earnings. Its profitability increased by 53 percent to Rs58.5 billion. PPL’s earnings rose by 25 percent to Rs25.2 billion, while MARI posted a 39 percent increase to Rs21.8 billion. POL registered 51 percent earnings growth to Rs8.2 billion, supported by higher prices, improved gas production, and sharply lower exploration expenses.
Exploration costs, however, remained a mixed picture. Combined expenses increased by 45 percent to Rs10.2 billion, equivalent to 3.7 percent of net sales, compared to approximately 3.3 percent in 1QFY26. PPL recorded a substantial increase following a dry well, taking its exploration-cost-to-sales ratio to 4.3 percent. OGDC’s expenses also rose due to higher prospecting activity, while exploration costs declined at MARI and POL. Such volatility highlights the risks associated with exploration and the need to replenish reserves as existing fields mature.
The comparison with FY26 is particularly important. The four companies reported combined annual earnings of around Rs460 billion, up 31 percent year-on-year. However, much of that increase resulted from Rs77.8 billion in one-off super-tax reversals. Excluding these adjustments, FY26 earnings increased by just 8.8 percent. Thus, the 1QFY27 improvement appears more closely linked to actual production, pricing, and operating performance, although higher investment income also supported profitability.
Nevertheless, profitability declined by approximately 47 percent quarter-on-quarter in 1QFY27, largely reflecting the absence of FY26’s tax reversals and lower sequential oil prices. The sector’s receivables also remain substantial despite improved recoveries, particularly at OGDC and PPL.
Looking ahead, higher oil prices and incremental production could sustain earnings. However, the real test will be maintaining production growth, accelerating commercially viable discoveries, and improving cash recoveries. Without sustained investment in reserves and exploration, the current earnings recovery may prove difficult to maintain.



Comments