


Pakistan bank deposits double to Rs40.83tr in 4 years, but lending to govt raises growth concerns
Pakistan's bank deposits have nearly doubled to Rs40.83 trillion, sparking debate on whether these funds are fueling productive economic activities or primarily government borrowing.
- Doubling of Pakistan's bank deposits.
- Funds flow to productive sectors versus government.
- Impact on private sector credit and economic growth.
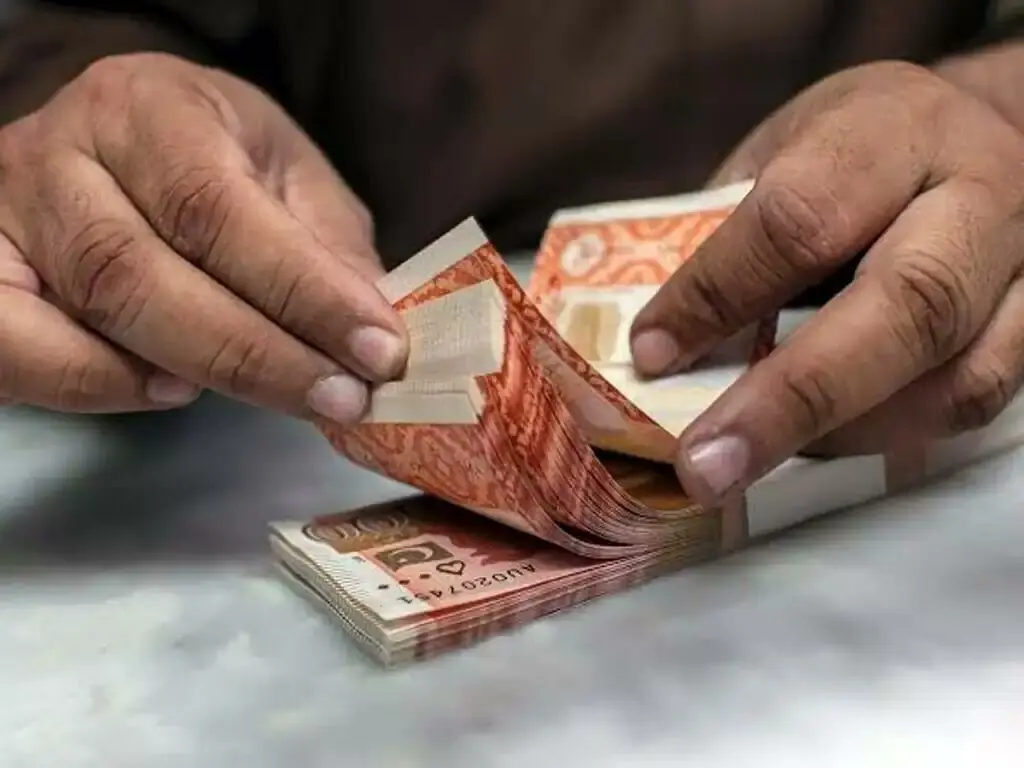
Deposits held by Pakistan’s scheduled banks have nearly doubled to Rs40.83 trillion in September 2026 from Rs21 trillion four years ago, highlighting a massive expansion in the banking system’s deposit base but raising questions about the flow of funds into productive economic activities.
Former minister and chairman Pakistan Economic Policy and Business Development Dr Gohar Ejaz said on Saturday, that scheduled banks’ total deposits increased by Rs19.83 trillion between September 2022 and September 2026, reflecting a substantial increase in funds available within the banking system.
However, the growing deposit base has renewed the debate over whether these funds are being channelled towards businesses, industry and private-sector investment or are increasingly being absorbed by government borrowing.
Ejaz stressed that the money mobilised by banks must reach businesses and industry, arguing that sustainable economic growth depends on productive economic activity rather than lending to the government.
The expansion in deposits represents a significant pool of financial resources that could potentially support industrial expansion, business investment, employment generation and economic activity.
However, the availability of deposits alone does not guarantee an increase in private-sector credit or investment.
The key challenge is to ensure that banks translate this growing deposit base into financing for productive sectors, particularly businesses seeking funds to expand operations, modernise production facilities and create jobs.
Heavy government borrowing from the banking system can compete with private-sector borrowers for available funds.
Depending on prevailing returns and credit risks, banks may prefer lending to the government over extending loans to businesses, particularly smaller enterprises that often face higher borrowing costs and stringent collateral requirements.
A sustained shift towards government securities could constrain the availability of credit for businesses, limiting investment and weakening the potential contribution of the private sector to economic growth.



Comments