


Shabbir Tiles & Ceramics Limited (PSX: STCL) was incorporated in Pakistan as a public limited company in 1978. The principal activity of the company is the manufacturing and sale of tiles under the brand name “Stile”. STCL has also diversified into trading of building and installation products.
Pattern of Shareholding
As of June 30, 2025, STCL has a total of 239.32 million shares outstanding which are held by 3436 shareholders. Foreign companies have the majority stake of 54.81 percent in the company followed by local general public holding 18.71 percent of shares. Modarabas & Mutual funds account for 14.04 percent of the outstanding shares of STCL.
Around 3.1 percent of the company’s shares are held by its Directors and their spouses and minor children and 2.89 by insurance companies. Thal Limited, which is an associated company of STCL, owns 1.30 percent of its shares.
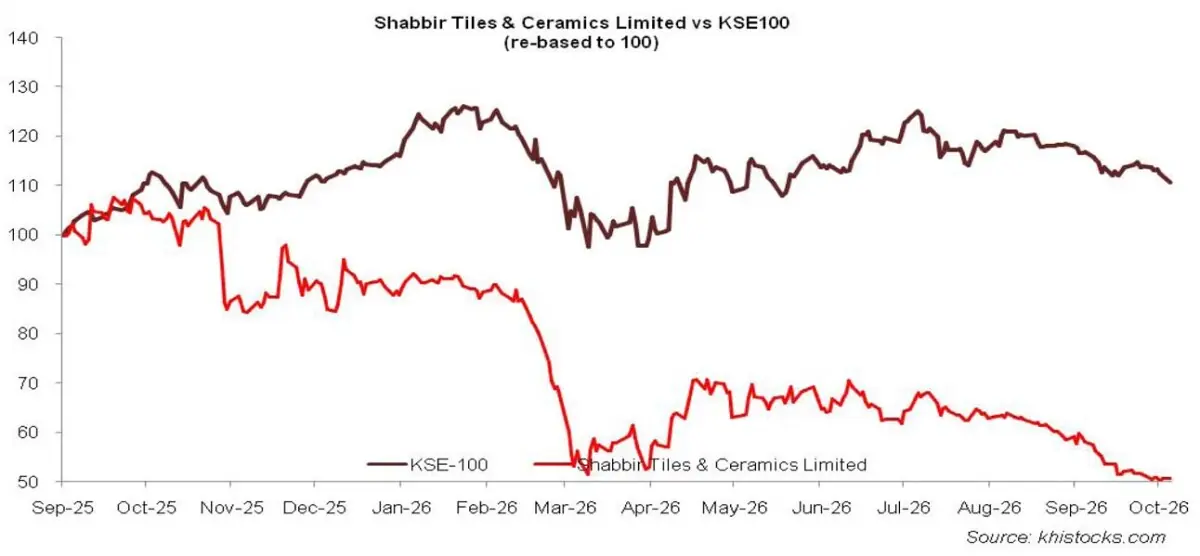
The remaining ownership is distributed among other categories of shareholders.
Financial Performance (2021-26)
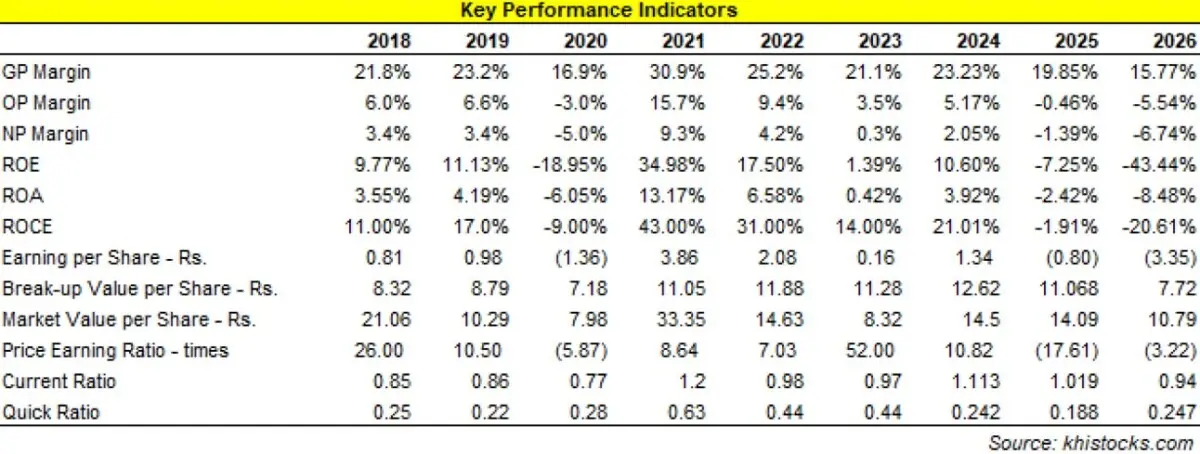
STCL’s topline posted decent growth until 2024 followed by a sharp decline in 2025 and 2026. The company’s bottomline which registered considerable improvement in 2021, deteriorated in 2022 and 2023. In 2024, net profit staggeringly rebounded followed by net losses recorded in 2025 and 2026. The margins of the company oscillated over the period under consideration. 2021 appears to be a healing year for STCL whereby all its margins attained their optimum levels.
However, the recovery didn’t prove to be sustainable as 2022 and 2023 saw steep decline in margins. In 2024, the margins posted an uptick followed by a plunge in 2025 and 2026.
The detailed performance overview underscoring the reasons of STCL’s financial performance over the period under consideration is given below.
STCL’s financial performance which took an ugly turn in 2020 considerably recovered in 2021 with 52.98 percent year-on-year rebound in net sales which clocked in at Rs.9904.50 million. This was mainly due to enhancement in construction activity during the year on account of construction stimulus packages introduced by the government coupled with accommodating monetary policy.
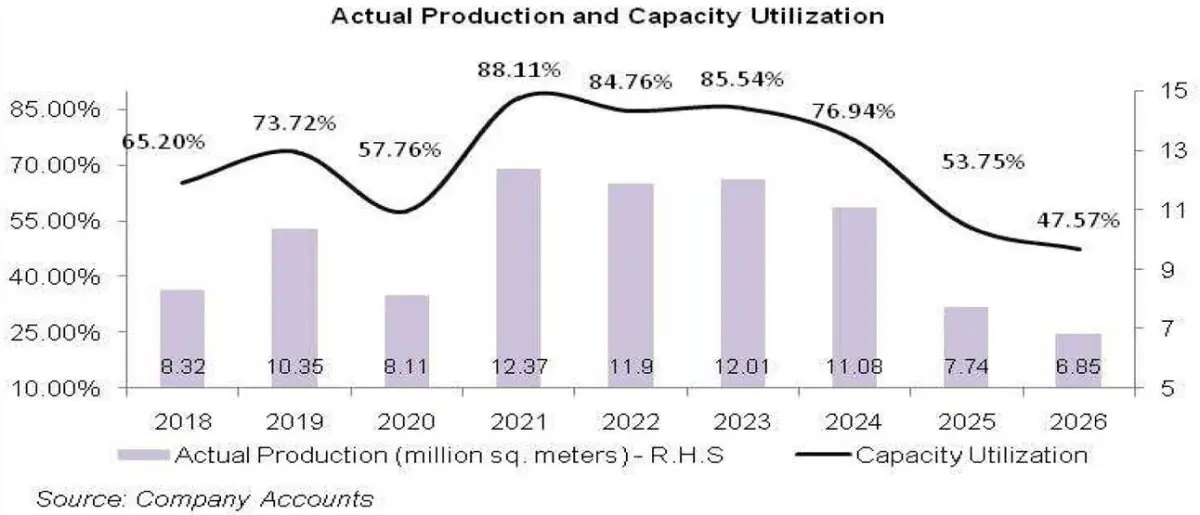
In response to demand recovery, the company produced 12.37 million square meters of tiles, up 53 percent year-on-year. This led to 88.11 percent capacity utilization in 2021. Since STCL is a company with high fixed-cost, hence, increased capacity utilization resulted in better absorption of cost, resulting in 179 percent year-on-year rebound in gross profit with GP margin of 30.90 percent recorded in 2021. This was against the GP margin of 16.94 percent recorded in 2020.
Distribution expense grew by 34.60 percent year-on-year in 2021 due to high freight charges on account of increased volume, higher payroll expense and cut-throat advertising to attain greater market penetration. Administrative expense grew by 13 percent year-on-year in 2021 on account of higher payroll expense despite a drop in employee count from 766 in 2020 to 742 in 2021. STCL posted robust net other income of Rs.162.03 in 2021, up 320.27 percent on account of gain recognized on the re-measurement of GIDC payable.
The company posted a staggering operating profit of Rs.1557.19 million in 2021 with OP margin of 15.72 percent – the highest among all the years under consideration. This was against the operating loss of Rs. 193.74 million recorded in 2020.
Despite monetary easing and lesser borrowings, finance cost spiraled by 23.39 percent year-on-year in 2021 as a consequence of unwinding of finance cost of GIDC. STCL’s gearing ratio fell to 7.06 percent in 2021 from 18.66 percent in 2020.
Net profit stood at an impressive Rs.924.89 million in 2021 with EPS of Rs.3.86 and NP margin of 9.34 percent. This was against the net loss of Rs. Rs.325.77 million and loss per share of Rs.1.36 recorded in 2020.
2022 also witnessed topline growth, albeit, with a lower magnitude of 20.14 percent year-on-year. This translated into net sales of Rs.11,898.97 million in 2022. This came on the back of improved product mix and price revision.
The production volume ticked down to 11.9 million square meters, culminating into capacity utilization of 84.76 percent in 2022.
Reduced volume was the result of high inflation and elevated discount rate which halted the construction activities in the country by restraining the purchasing power.
The development spending also took a plunge in 2022 as the government was grappling against current account and fiscal slippages. Exorbitantly high energy prices as well as gas shortages also led to reduced capacity utilization during the year and also contributed towards 30 percent year-on-year cost hike in 2022. Gross profit narrowed down by 2.13 percent year-on-year in 2022 with GP margin declining to 25.17 percent.
Distribution expense posted 14.88 percent year-on-year surge in 2022 which was due to sharp spike in freight cost on account of elevated petroleum prices. Administrative expense also measured up by 16.16 percent year-on-year in 2022.
STCL registered net other income of Rs.85.25 million in 2022, down 47 percent year-on-year as re-measurement gain on GIDC payable was no longer recorded in 2022. Operating profit tapered by 27.91 percent year-on-year with OP margin considerably plummeting to stand at 9.43 percent in 2022.
Finance cost enlarged by 7.81 percent in 2022 as the company incurred low unwinding of finance cost on GIDC and lease liabilities. STCL’s gearing ratio grew to 9.03 percent in 2022. Net profit inched down by 46.23 percent year-on-year in 2022 to clock in at Rs.497.322 million with EPS of 2.08 percent and NP margin of 4.2 percent.
Slowdown of construction activity in the country led to lackluster demand of tiles in 2023. This forced many tile manufacturers to either hold back or shut down their production activities in 2023. In such uncertain economic backdrop, STCL’s topline showed resilience as it grew by 19.19 percent year-on-year to clock in at Rs. 14,182.48 million in 2023.
While the demand remained sluggish, STCL altered its sales mix and pricing strategy to maintain its sales volume at the previous year’s level. Capacity utilization stood at 85.54 percent in 2023. Topline growth couldn’t trickle down to produce a healthier bottomline amid 25.73 percent higher cost of sales recorded in 2023. This was the consequence of Pak Rupee depreciation, unprecedented inflation and unparalleled energy cost. This pushed GP margin down to 21.1 percent.
In absolute terms, gross profit ticked down by 0.26 percent in 2023. Distribution expense mounted by 32.91 percent in 2023 due to higher freight charges on account of whopping upturn in diesel prices. Administrative expense escalated by 15.14 percent in 2023 due to higher payroll expense on account of inflationary pressure.
Conversely, workforce was squeezed from 745 employees in 2022 to 730 employees in 2023. STCL registered net other income of Rs.22.08 million in 2023, down 74.10 percent year-on-year. This was due to lesser interest income on TDRs, low dividend income from mutual funds and higher exchange loss recorded in 2023. STCL registered 55.62 percent decline in its operating profit in 2023 with OP margin drastically falling down to 3.51 percent.
Finance cost surged by 67.19 percent in 2023 due to higher unwinding of finance cost of lease liabilities and elevated discount rate. Besides, the company’s outstanding long-term loans also increased during the year in order to finance its CAPEX and for the investment in renewable energy.
STCL’s gearing ratio escalated to 18.52 percent in 2023. Net profit weakened by 92.44 percent in 2023 to clock in at Rs.37.61 million with EPS of Rs.0.16 and NP margin of 0.27 percent.
STCL recorded 9.86 percent year-on-year uptick in its net sales which clocked in at Rs.14,182.48 million in 2024. The enduring political and economic crisis took its toll on the demand of tiles due to sluggish activity in the construction sector – both individual and commercial segments.
The company operated at 76.94 percent capacity in 2024 versus capacity utilization of 85.54 percent recorded in the previous year.
The company passed on the impact of cost hike to its consumers by revising its prices. This resulted in 21.17 percent year-on-year improvement in gross profit in 2024 with GP margin climbing up to 23.23 percent. Distribution expense surged by 16.84 percent in 2024 due to heightened freight charges, axle load requirements and high diesel prices.
Administrative expense inched up by 2.91 percent due to inflation. This was despite the fact that the company streamlined its workforce from 730 employees in 2023 to 702 employees in 2024.
STCL recorded net other income of Rs.94.72 million in 2024, up 328.92 percent year-on-year. This was due to considerably lower exchange loss incurred during the year coupled with higher profit recognized on bank deposits. STCL’s operating profit strengthened by 61.57 percent in 2024 with OP margin jumping up to 5.17 percent.
Finance cost inched up by just 2.56 percent in 2024. This was due to lesser outstanding borrowings recorded at the end of 2024.
STCL’s gearing ratio fell from 18.52 percent in 2023 to 15.19 percent in 2024. The company’s bottomline posted a staggering growth of 751.21 percent to clock in at Rs.320.17 million in 2024 with EPS of Rs.1.34 and NP margin of 2.1 percent.
In 2025, STCL’s net sales dipped by 11.14 percent to clock in at Rs.13,846.06 million. This was on account of lower public and private sector developmental spending due to dampened investor confidence. Improved macroeconomic activity didn’t provide much impetus to the construction sector.
Growth was restricted in renovation projects and certain government-led initiatives. Private sector construction activity remained lackluster in 2025. In accordance with thinner demand, the company operated at 53.75 percent capacity in 2025.
Cost of sales tumbled by a lesser magnitude of 7.22 percent in 2025 owing to higher raw material charges and elevated energy charges. Gross profit thinned down by 24 percent in 2025 with GP margin falling down to 19.85 percent. Lower sales volume resulted in 4.72 percent decline recorded in distribution expense in 2025.
Conversely, administrative expense mounted by 30.32 percent in 2025 due to higher payroll expense on account of inflationary pressure. This was despite the fact that the company streamlined its workforce from 702 employees in 2024 to 681 employees in 2025. Net other income weakened by 6.39 percent in 2025 mainly due to thinner dividend income and scrap sales.
STCL incurred operating loss of Rs.63.39 million in 2025 versus operating profit of Rs. 804.93 million recorded in the previous year.
Finance cost dropped by 9.89 percent in 2025 despite monetary easing. This was despite increased short-term borrowings. Gearing ratio ticked up to 15.68 percent in 2025. STCL recorded net loss of Rs.192.13 million in 2025. This translated into loss per share of Rs.0.80 in 2025.
Recent Performance (2026)
In 2026, STCL’s net sales further dwindled by 14 percent to clock in at Rs.11.898.89 million. This was due to lackluster housing and construction activity during the year despite improving macroeconomic fundamentals.
Capacity utilization of STCL fell to 47.57 percent in 2026 to go with lower demand. To add to ado, regional tensions escalated fuel and freight cost as well as raw material prices and caused supply chain disruptions in 2026. This resulted in 31.72 percent decline in gross profit in 2026 with GP margin falling to its lowest level of 15.77 percent.
Lesser sales volume & promotional budget resulted in 9 percent decline in distribution expense in 2026. Administrative expense escalated by 19.46 percent in 2026 due to higher payroll expense. This was despite workforce rationalization to 569 employees in 2026.
Net other income strengthened by 180.77 percent in 2026 due to lower exchange loss, gain on discounting of Sindh Infrastructure Development cess, greater scrap sales and gain on disposal of fixed assets. Operating loss surged by 939.71 percent to clock in at Rs.659.04 million in 2026.
Due to weaker cash flow position, STCL relied on external borrowings in 2026 which translated into 73.11 percent spike in finance cost in 2026. Gearing ratio climbed up to 37.53 percent in 2026. Net loss worsened by 317.48 percent to clock in at Rs.802.10 million in 2026. This translated into loss per share of Rs.3.35 in 2026.
Future Outlook
While demand stayed fragile during the year with no massive turnaround anticipated in 2027, the company is focusing on maintaining cost discipline, attaining energy mix optimization by investment in 6MW Battery Energy Storage System (BESS) project, fixed cost rationalization and streamlining of organizational processes through SAP S/4HANA Public Cloud implementation.
The company is also focusing on high-margin products to strengthen its margins and push its bottomline into positive zone.



Comments