


Metropolitan Steel Corporation Limited: performance and outlook
Metropolitan Steel Corporation Limited (MSCL) has faced consistent net losses since 2021, struggling with low capacity utilization, high costs, and intense competition despite some sales growth.
- MSCL's fluctuating sales and consistent net losses since 2021.
- Impact of high costs, currency depreciation, and subdued demand.
- Future challenges and strategies for capacity utilization and profitability.
Metropolitan Steel Corporation Limited (PSX: MSCL) was incorporated in Pakistan as a public limited company in 1955. The company is engaged in the manufacturing of steel products such as torsteel, ribbed bars, bailing hoops, wire rods, transmission towers, mild and special steel wires etc.
Pattern of Shareholding
As of June 30, 2025, MSCL has a total of 30.978 million shares outstanding which are held by 3964 shareholders. Directors, CEO, their spouse and minor children are the major shareholders of MSCL holding 75.23 percent shares of the company followed by local general public having a stake of 23.75 percent in the company. The remaining shares are held by other categories of shareholder
Historical Performance (2021-25)
MSCL’s topline posted a staggering year-on-year growth in 2021. The growth trajectory continued in the subsequent year, however with a significantly lesser magnitude.
In 2023, MSCL’s net sales ticked down followed by a rebound in 2024. In 2025, topline plunged. Among all the years under consideration, the company posted net profit only in 2021.
In rest of the years under consideration, the company was not even able to post gross profit, let alone positive bottomline. In 2022, MSCL posted the highest net loss despite topline growth. The detailed performance review of the period under consideration is given below.
In 2021, MSCL’s topline boasted a massive year-on-year growth of 238.23 percent to clock in at Rs.92.67 million. As the signs of COVID-19 began to subside, the market responded positively. MSCL’s sales mainly grew on the back of vigorous demand from automobile and foaming industry and also because of upward revision in the prices of MSCL products.
Pak Rupee depreciation greatly increased the cost of sales; yet, MSCL was able to post gross profit of Rs. 11.504 million after successive years of gross losses.
GP margin clocked in at 12.41 percent in 2021. Administrative and distribution expenses rose by 7.95 percent and 80.3 percent year-on-year respectively in 2021 on the back of higher payroll expenses due to high capacity utilization and also because of hefty forwarding and transportation charges. After two consecutive years, the company incurred other expense of Rs.7.589 million in 2021 as it sustained bad debts, loss on sale of machinery and also booked provision for obsolete store and spares.
Other income ticked down by 10.29 percent year-on-year in 2021 due to lesser realized gain on short-term investment and lesser profit on TDRs. Operating profit clocked in at Rs.1.128 million in 2021 with OP margin of 1.22 percent. Finance cost further climbed down by 40.63 percent year-on-year due to lesser bank charges.
The company reported a positive bottomline of Rs.1.845 million in 2021 with EPS of Rs. 0.06 and NP margin of 2 percent. This was against net loss of Rs. 16.717 million and loss per share of Rs.0.54 recorded in 2020.
The sales growth continued in 2022, however, with a considerably lower degree of 8.7 percent year-on-year. MSCL’s net sales were recorded at Rs.100.734 million in 2022.
The sales growth was driven by the demand of spoke wire, MS wire, spring wire, high carbon wire and MS products. However, high cost of sales due to commodity super cycle in the global market coupled with Pak Rupee depreciation culminated into gross loss of Rs.17.65 million in 2022.
Administrative and selling expenses grew by 26.25 percent and 14.48 percent respectively in 2022 due to higher salaries, fee and subscription charges and freight charges incurred during the year. Other expense drastically grew by 969.76 percent year-on-year as the company booked provision worth Rs. 81.18 million for doubtful debt.
Other income performed well and registered growth of 814.31 percent year-on-year to clock in at Rs.26.14 million as director loan of Rs.18.55 million was written back during the year and the company also made scrap sales of Rs.7.3 million in 2022.
Due to significantly high other expense, the company posted operating loss of Rs. 79.779 million, the highest among all the years under consideration. Finance cost also grew by 21percent year-on-year. MSCL posted the highest net loss of Rs.79.88 million in 2022 with loss per share of Rs.2.58.
In 2023, MSCL’s topline slid by 1.52 percent to clock in at Rs.99.203 million. This was due to subdued demand from both automobile and construction sectors on account of ongoing economic and political crisis. Due to sluggish demand, the company’s capacity utilization stood at 6.11 percent in 2023 versus 7.21 percent in 2022.
Cost of sales dropped by 9.81 percent in 2023, yet the company posted gross loss of Rs.7.573 million, down 57 percent year-on-year. Administrative expense multiplied by 34.95 percent in 2023 due to higher payroll expense as well as legal & professional charges incurred during the year.
MSCL significantly downsized its workforce to only 9 employees in 2023 from 27 employees in the previous year. Distribution expense nosedived by 1.43 percent in 2023 due to lower forwarding and transportation charges amid thin demand.
Other expense dropped by 86.83 percent in 2023 due to lesser provisioning done for doubtful debts. Other income also slumped by 46.12 percent in 2023 due to high-base effect as the company wrote off directors’ loan in 2022 and also because of scrap sales made in 2022. Operating loss contracted by 82.96 percent to clock in at Rs.13.594 million in 2023.
Finance cost surged by 278.26 percent in 2023 on account of higher bank charges & commission and also because of LC charges incurred during the year. MSCL posted net loss of Rs.13 million in 2023, down 83.73 percent year-on-year. Loss per share stood at Rs.0.42 in 2023.
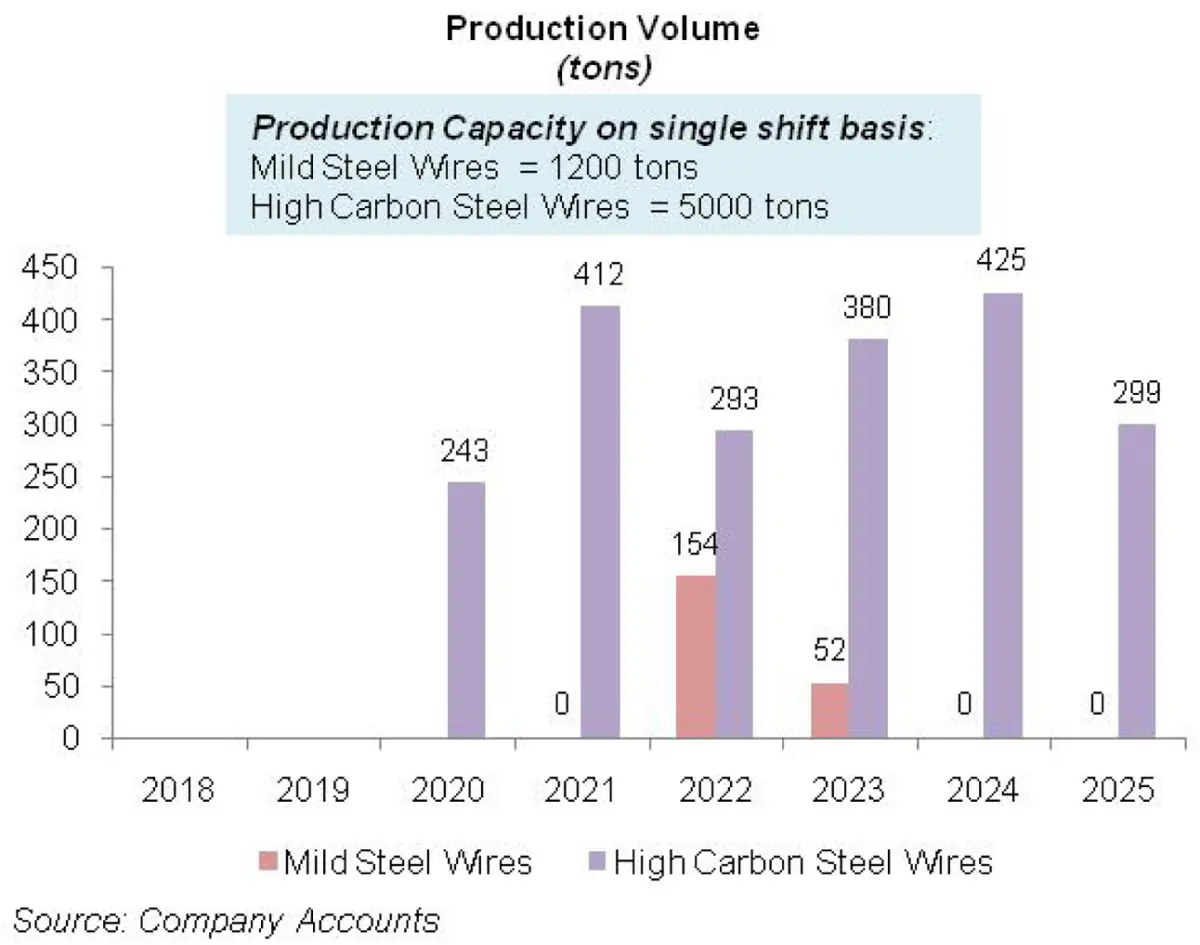
In 2024, MSCL’s topline grew by 23.46 percent year-on-year to clock in at Rs.122.475 million. During the year, the company didn’t produce any mild steel wires due to sluggish demand in the market on account of political and economic instability.
Conversely, the production of high carbon steel wires grew by 11.84 percent to clock in at 425 tons which is still very low when compared to the rated capacity of 5000 tons.
Pak Rupee depreciation, elevated energy cost and escalated raw material prices resulted in 30.82 percent higher cost of sales in 2024.
Low demand in the market and idle plant capacity didn’t allow MSCL to pass on the impact of cost hike to its consumers. This resulted in 127.29 percent higher gross loss to the tune of Rs. 17.213 million incurred during the year. Administrative expense escalated by 14.86 percent in 2024 due to inflationary pressure.
Distribution expense surged by 50.85 percent in 2024 due to higher forwarding and transportation charges incurred during the year. Other income shrank by 67.29 percent in 2024 due to high-base effect as the company wrote back liabilities in 2023. Operating loss mounted by 73.33 percent to clock in at Rs.23.56 million in 2024.
Finance cost dwindled by 26.44 percent in 2024 due to lower bank commission and charges paid during the year. Net loss multiplied by 79.55 percent to clock in at Rs. 23.34 million in 2024. This translated into loss per share of Rs.0.75 in 2024.
In 2025, MSCL posted 17.74 percent year-on-year decline in its topline which was recorded at Rs.100.747 million.
This was on account of sluggish demand and a decline in the prices of final products due to steep fall in international steel prices. This greatly increased the competitive pressure.
While the local companies continued to face cost pressure on the back of exorbitant energy cost, cheaper smuggled products expanded their wings. Just like the previous year, the company produced no mild steel wires in 2025. Production of high carbon steel wires also plummeted by 29.65 percent to clock in at 299 tons in 2025.
Cost of sales dwindled by 19.51 percent in 2025 due to stability in the value of local currency and decline in international steel prices on account of lackluster demand from key economies like China and India. This resulted in 32.13 percent plunge recorded in the gross loss of the company which clocked in at Rs.11.683 million in 2025.
Administrative expense mounted by 70.80 percent in 2025 mainly on account of higher payroll expense as well as legal & professional charges incurred during the year. Unlike previous year where MSCL recorded no other expense, provisioning done for doubtful debt and obsolete store and spares resulted in other expense of Rs.1.415 million in 2025.
Other income strengthened by 291.10 percent in 2025 on account of liabilities written back. Operating loss tapered off by 45.65 percent to clock in at Rs.12.805 million in 2025. Finance cost ticked up by 6.77 percent in 2025 due to higher bank charges incurred during the year.
The company has no external short-term or long-term liabilities on its books as of June 30, 2025. MSCL recorded 46.78 percent thinner net loss to the tune of Rs.12.423 million in 2025. This translated into loss per share of Rs.0.40 in 2025.
Recent Performance (9MFY26)
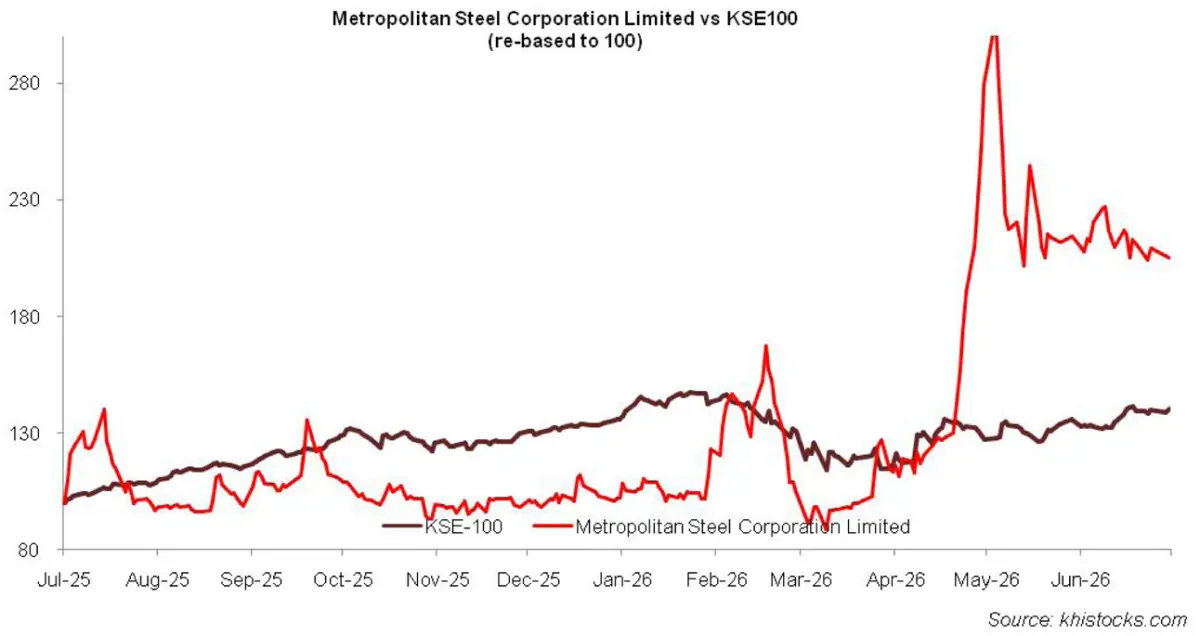
During the nine-month period of the ongoing fiscal year, MSCL recorded a marginal 1.37 percent uptick in its net sales which clocked in at Rs.75.30 million. The company’s main products included springs for mattresses and cars which faced demand deficit due to decline in the purchasing power of consumers and companies.
The spike in steel prices in the aftermath of Middle East crisis didn’t impact the company as it consumed its inventory from previous years which enabled it to record inventory gain. However, it was able to upward revise the prices of its products in line with elevated steel prices.
Cost of sales fell by 11.34 percent during 9MFY26 which resulted in 99.33 percent diminution in gross loss which was recorded at Rs.0.072 million.
Administrative expense tumbled by 4 percent in 9MFY26 due to considerable decline in legal & professional charges. Other income also dipped by 64.17 percent during the period seemingly due to lower mark-up income on account of monetary easing and lesser bank balances at the end of the period.
Operating loss clocked in at Rs.10.65 million in 9MFY26, down 47.66 percent year-on-year. Finance cost (which included bank & L/C charges) surged by 57.58 percent in 9MFY26. Net loss tapered off by 49.60 percent to clock in at Rs.10.12 million in 9MFY26. This translated into loss per share of Rs.0.327 in 9MFY26 versus loss per share of Rs.0.648 recorded in 9MFY25.
Future Outlook
Gradual local economic recovery coupled with the rebound of local automobile, white goods and construction industries provide impetus to improved demand of steel products.
However, MSCL, facing structural slowdown and operating on a very minimal capacity, is expected to struggle in order to regain profitability.
The company has no external debts on its books which shields it from finance cost as of now, however, this also implies that it has limited access to working capital. This coupled with intense competition from low-cost imported products is expected to take its toll on the financial performance of MSCL.
In order to increase its capacity utilization and sales, it would need external borrowing or capital injection. It would also need to revamp its offering and shift to high-margin steel products in order to evade competition from cheaper regional products.


Comments