


Cement: Growth meets margin pressure
Despite robust volume growth, the cement industry's profitability is flat due to soft retention prices and declining other income, with reduced finance costs protecting the bottom line.
- Flat profitability despite robust volume growth.
- Significant impact of declining finance costs.
- Challenges in passing on price adjustments.
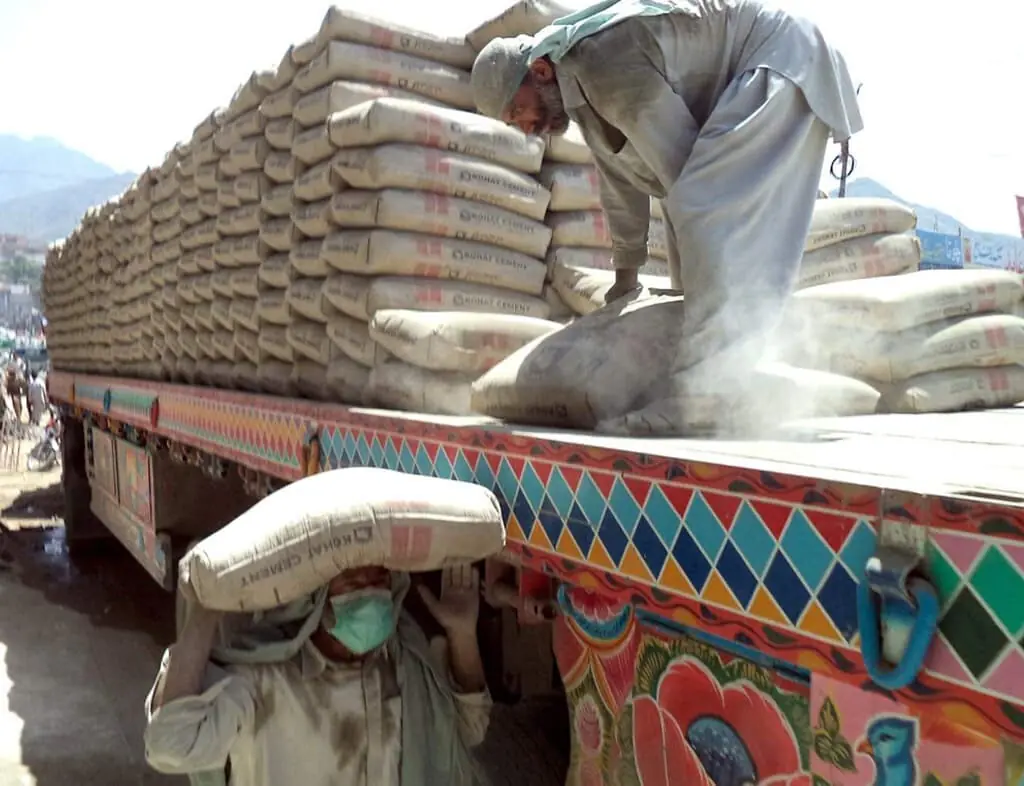
This year, the cement industry is learning that a volume recovery may not be enough to boost profitability. Despite a robust offtake growing by 10 percent, where domestic demand brought much of the impetus, earnings have remained flat as a share of revenue. In 9MFY26, the industry’s cumulative margins stood at 18 percent.
Combined revenues of listed cement players rose 8 percent in 9MFY26, lagging volumetric growth as revenue per ton slipped 2 percent. Export markets that were once a release valve for excess capacity saw their relevance in the sales mix drop with their share of total sales easing to 18 percent from 19 percent last year.
The shift back to local demand may have improved utilization rates, but retention prices have remained on the softer side.
Margins as a result have continued to cool. Gross margins were dragged down to 30 percent from 31 percent a year earlier. The pressure is notable because input costs, at least on paper, were relatively benign.
Costs per ton sold fell marginally by 1 percent, helped by lower imported coal prices. But the absence of cheaper Afghan coal for northern producers and the inability to fully pass on price adjustments diluted much of the fuel savings.
The industry’s earnings quality also remains dependent on factors outside core operations. Other income declined 3 percent year on year and now contributes 6 percent of sales versus 7 percent last year, reinforcing the fading support from treasury income and subsidiary dividends that had previously cushioned profitability.
What ultimately protected the bottom line was the decline in finance costs. Financial charges fell 40 percent year on year, shrinking to just 2 percent of revenues from 4 percent last year as lower interest rates and deleveraging reshaped balance sheets. Without this relief, the sector’s earnings growth would have looked considerably weaker.
Though demand has returned, capacity utilization is still hovering near suboptimal levels. The upward move of global coal and fuel prices, particularly amid renewed geopolitical disruptions, could test whether the sector has regained enough pricing discipline to protect margins without derailing the very demand recovery it is counting on.










Comments