



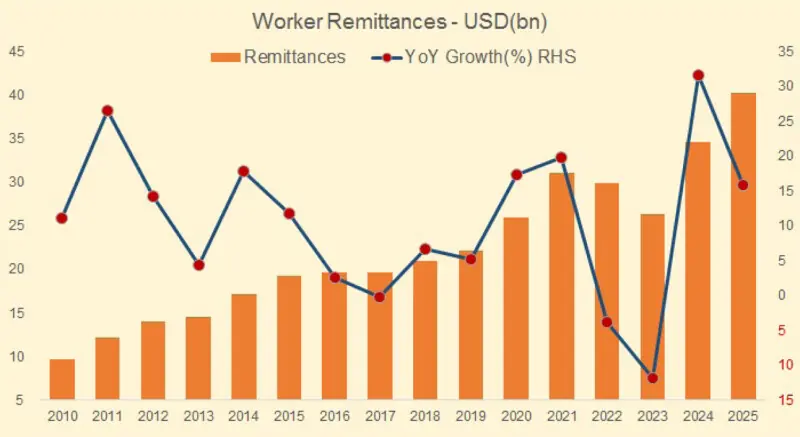
Workers’ remittances remain Pakistan’s quiet stabilizer in 1HFY26. Between July and December, overseas Pakistanis sent home $19.7 billion, up 10.6 percent from last year’s $17.8 billion. At a time when exports, portfolio flows, and FDI are all uneven, remittances have become the country’s most dependable source of hard currency.
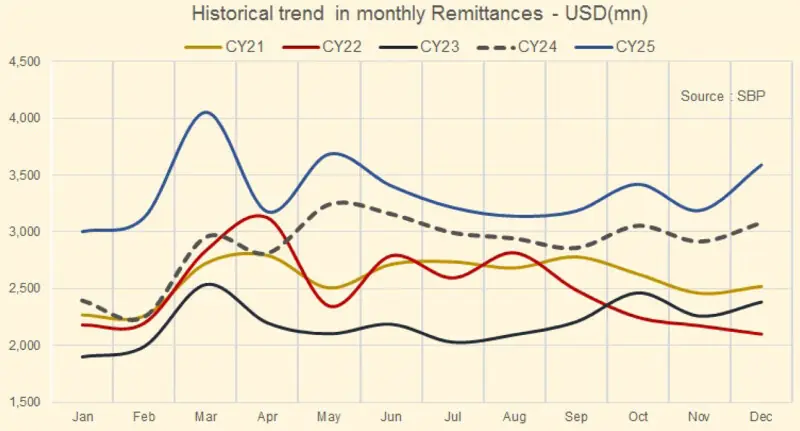
December 2025 underlined that strength. Inflows touched $3.6 billion, a solid 16.5 percent higher than a year earlier and 12.6 percent higher than November. This was not just a good month — it capped a strong half-year. With $16.1 billion already in by November, December pushed the total close to $20 billion, confirming that momentum did not fade as the year went on.
More importantly, monthly remittances now seem to have found a new “floor” well above $3 billion, which was not the case a few years ago.
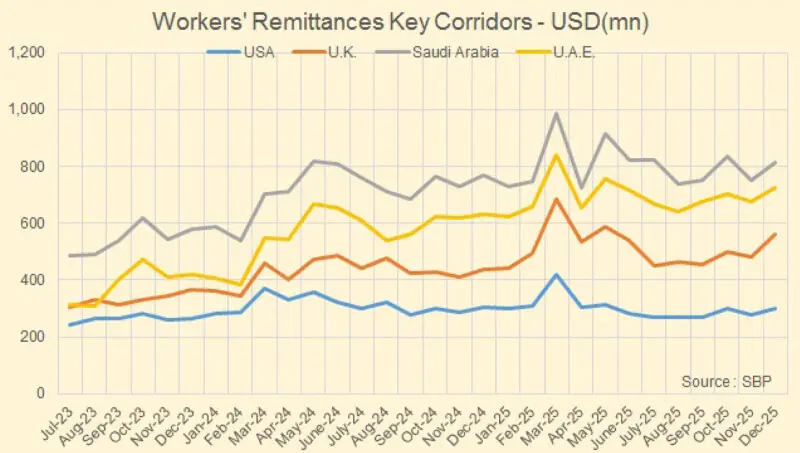
Where the money is coming from also tells an important story. In December, the bulk of inflows came from Saudi Arabia ($813 million) and the UAE ($726 million), followed by the UK ($560 million) and the US ($302 million). These four corridors alone delivered around two-thirds of all remittances.
The Gulf countries matter because they reflect real employment — millions of Pakistanis working on construction sites, in services, and in households — while the UK and US flows are tied more to the settled diaspora. Together, they create a powerful and relatively stable pipeline.
What stands out this year is not just how high remittances are, but how steady they have become. And spikes around Eid and Ramadan is going to boost these inflows further. That stability in remittances has real macroeconomic value: it helps keep the rupee from coming under pressure, supports the country’s FX reserves, and gives policymakers some breathing room in managing imports and debt payments.
Still, remittances are not a growth strategy. They keep the economy afloat, but they do not replace exports, investment, or productivity. If anything, today’s strong inflows should be seen as an opportunity — a window in which Pakistan can push reforms, make life easier for exporters, and improve the investment climate, instead of constantly firefighting external crises.
Moving forward, much will depend on two things. One is whether the gap between official and informal exchange rates stays narrow — if it widens, money will leak out of the banking system.
The other is whether job markets in the Gulf remain healthy. For now, both are holding up. With nearly $20 billion already earned in the first half of FY26 and December closing at $3.6 billion, Pakistan enters the rest of the year with its most reliable external lifeline still very much intact.


















Comments
Comments are closed for this article.