



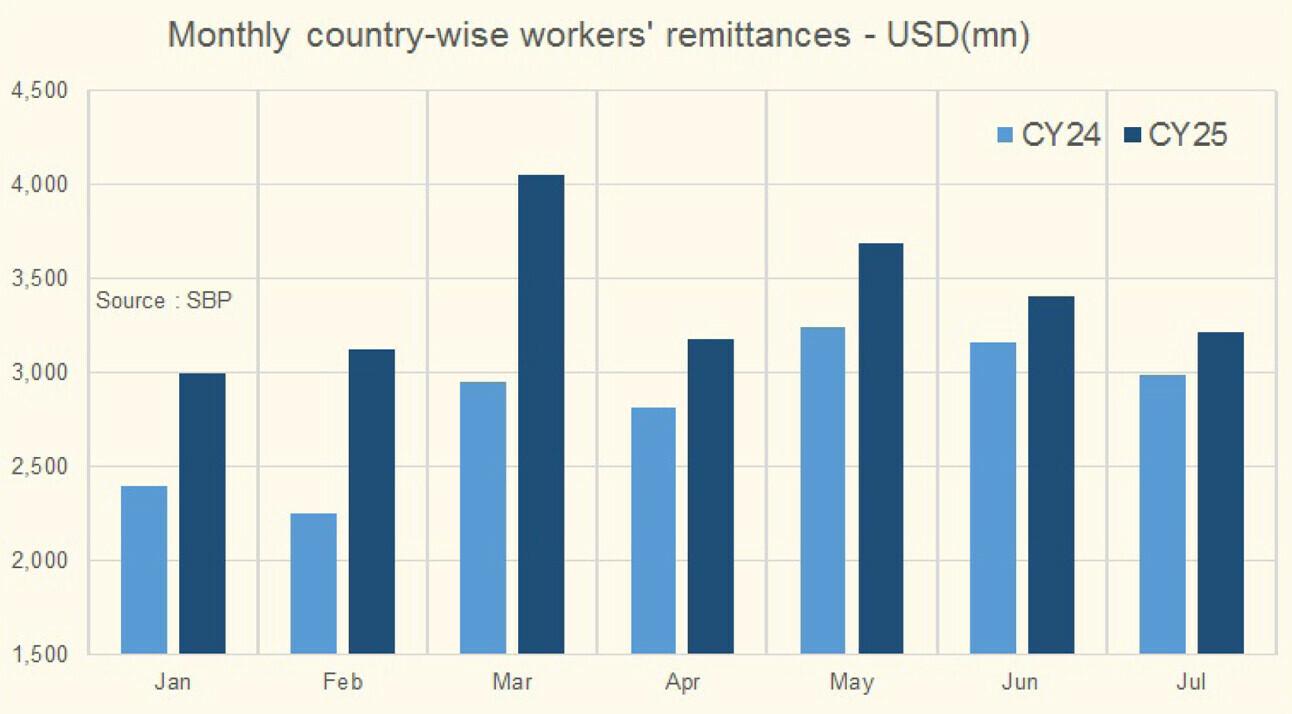
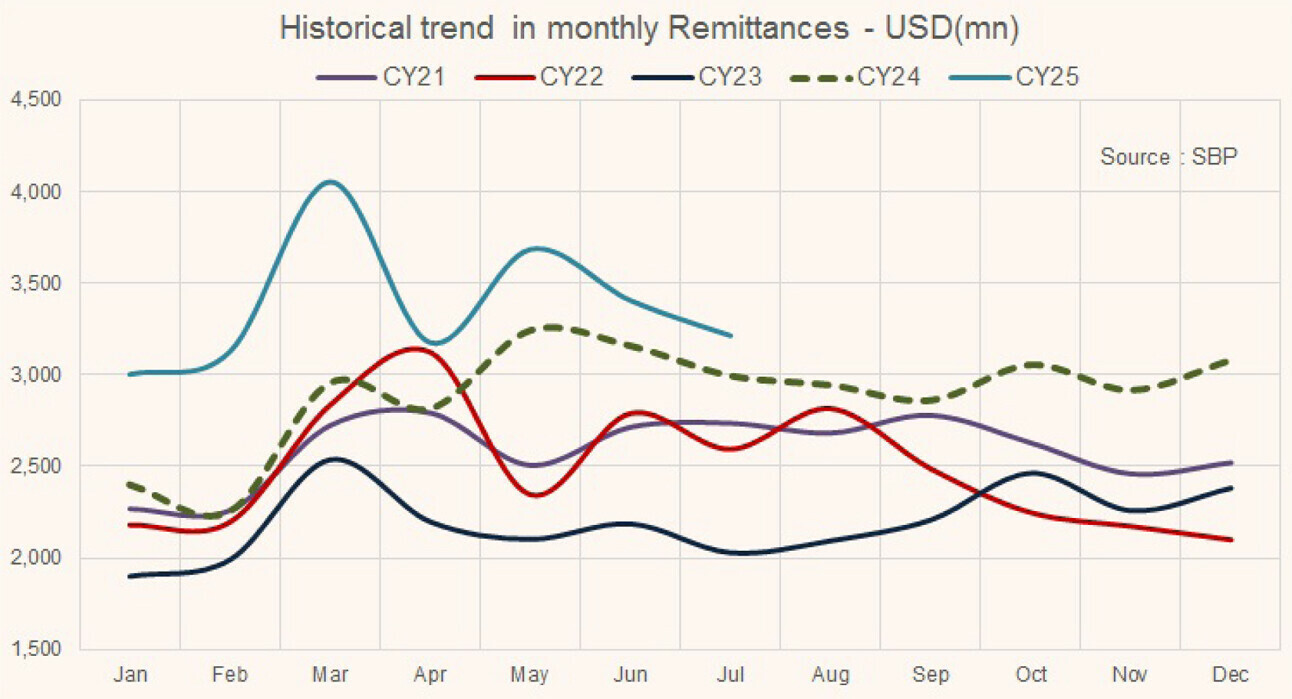
Pakistan’s remittance inflows in Jul-25 reached $3.21 billion, up 7.4 percent year-on-year, though 5.6 percent lower than June’s $3.4 billion due to seasonal normalization after the end-of-fiscal surge.
The growth marks a strong start to FY26, following FY25’s record $38.3 billion in remittances—a 27 percent increase from the previous year that even exceeded total export earnings.
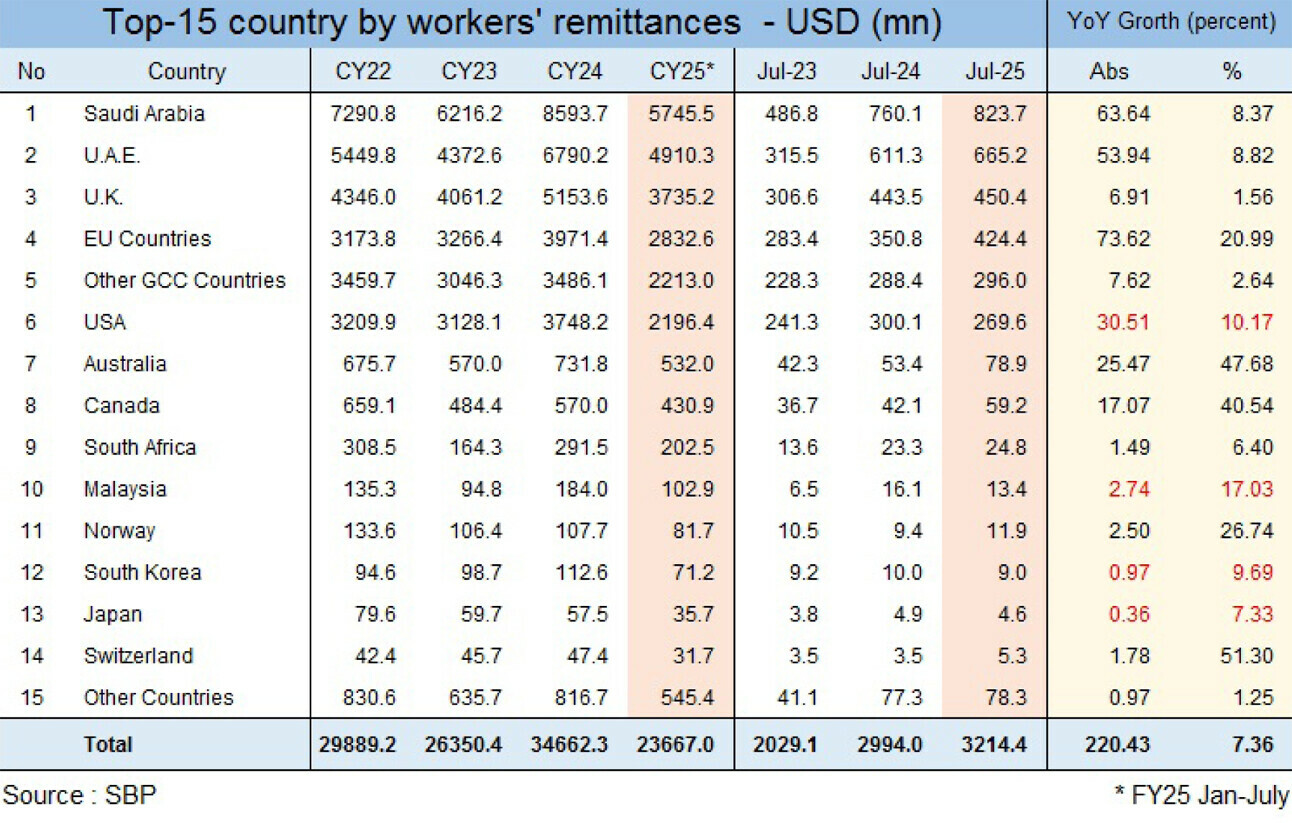
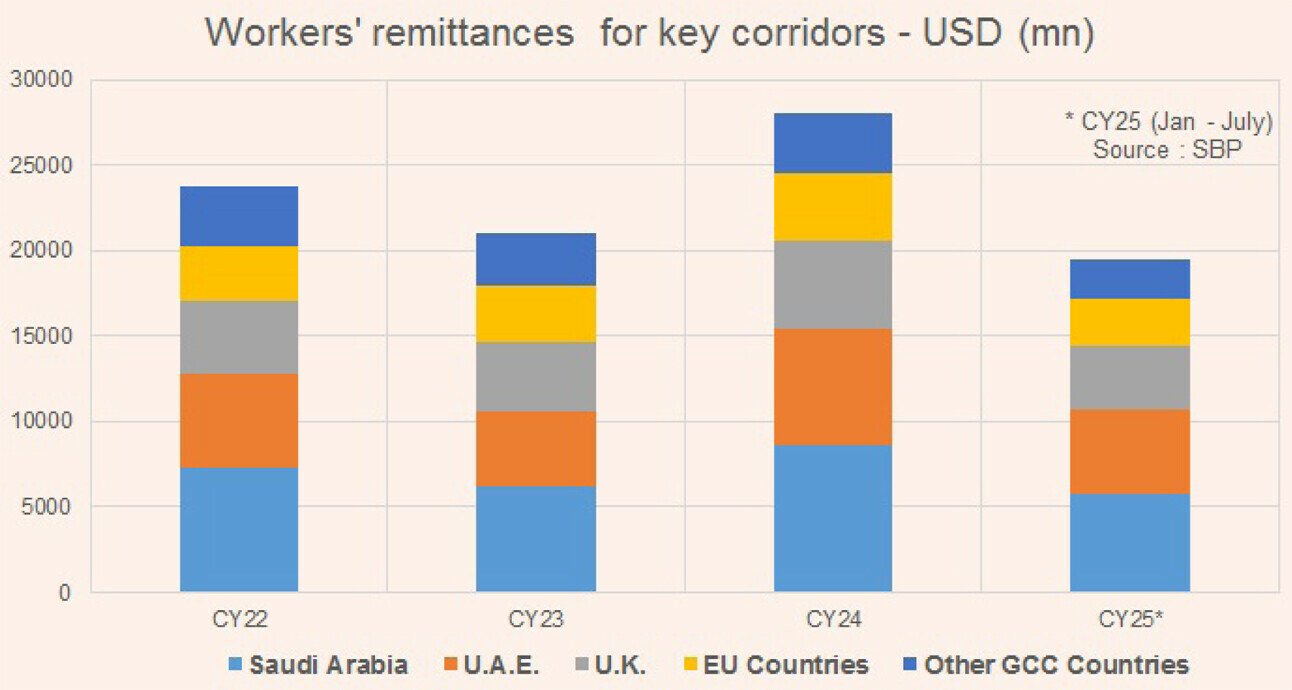
According to the State Bank of Pakistan, Saudi Arabia remained the largest contributor in July with $823.7 million, followed by the UAE at $665.2 million (including $456.8 million from Dubai), the UK at $450.4 million, the EU at $424.4 million, the US at $269.6 million, and other GCC countries including Qatar, Oman, and Kuwait contributing $296 million. This distribution underscores the continued reliance on Gulf-based labour migrants while highlighting steady inflows from Europe and North America, reflecting a diversified base that now includes professionals, students, and freelancers alongside traditional workers.
Several factors have supported recent inflows. A crackdown on hundi/hawala networks and money laundering has made formal banking channels more attractive, while a more competitive exchange rate has reduced incentives for informal transfers.
Rising income from freelancers and Pakistan-based professionals working remotely for foreign companies has also added to the inflow, offsetting stagnant outward migration as some Gulf states tighten work visa quotas.
Despite their importance in shoring up foreign exchange reserves and easing the current account, remittances remain vulnerable to external job markets, oil prices, and host country policies.
Heavy reliance on them also risks a “Dutch Disease” effect—drawing labour into low-productivity sectors like construction, boosting imports, and delaying the structural reforms needed to enhance export competitiveness.
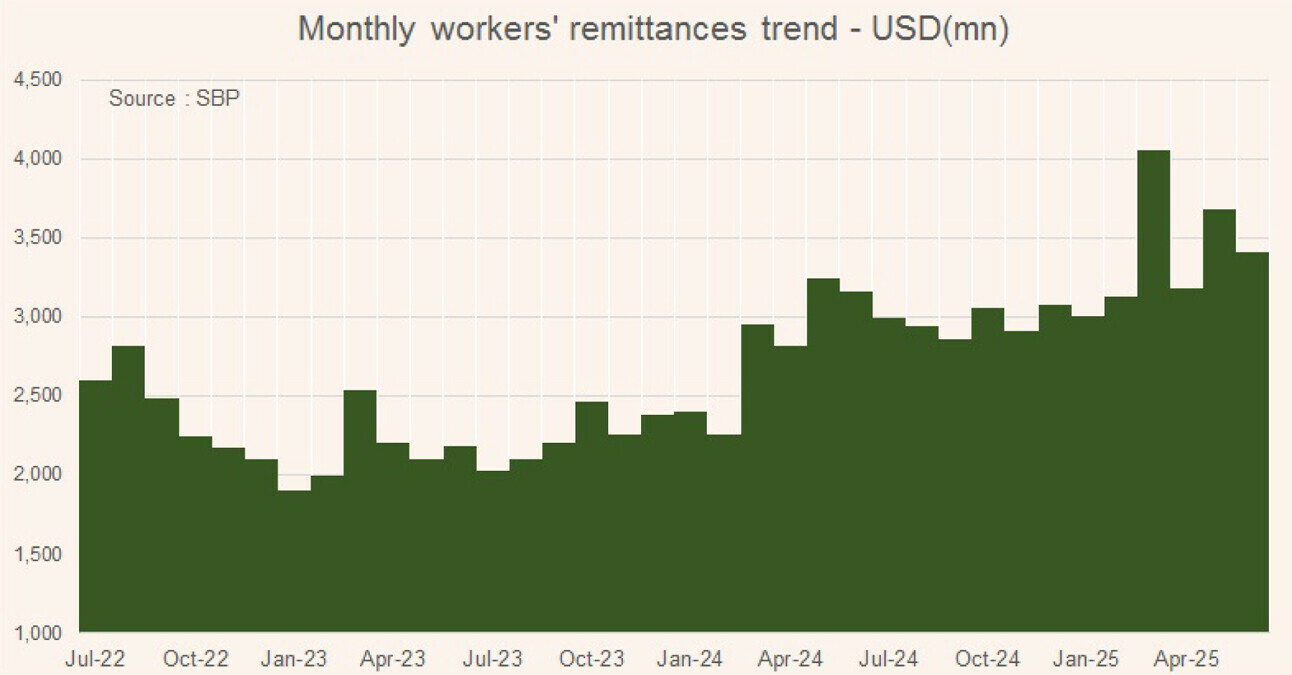
Seasonal peaks, such as around Eid or the fiscal year’s start, can mask underlying volatility, while shifts in the global economy or slower Gulf growth could quickly put inflows under pressure.
This is why policymakers must view the current remittance windfall as a strategic opportunity rather than a permanent cushion.
Maintaining the enforcement environment that channels inflows through formal means is necessary, but not sufficient. The real imperative is to channel these funds into productivity-enhancing investments—expanding value-added manufacturing, upgrading skills, and integrating into global supply chains.
July’s performance is encouraging, but the measure of success will be whether the country can convert this inflow into long-term resilience, reducing dependence on a revenue stream that is ultimately shaped by forces beyond its control.




















Comments
Comments are closed for this article.