



MCB Bank Limited ended 1HCY25 with a higher Investment to Deposit Ratio than the infection ratio on its loan book. This does not happen often.
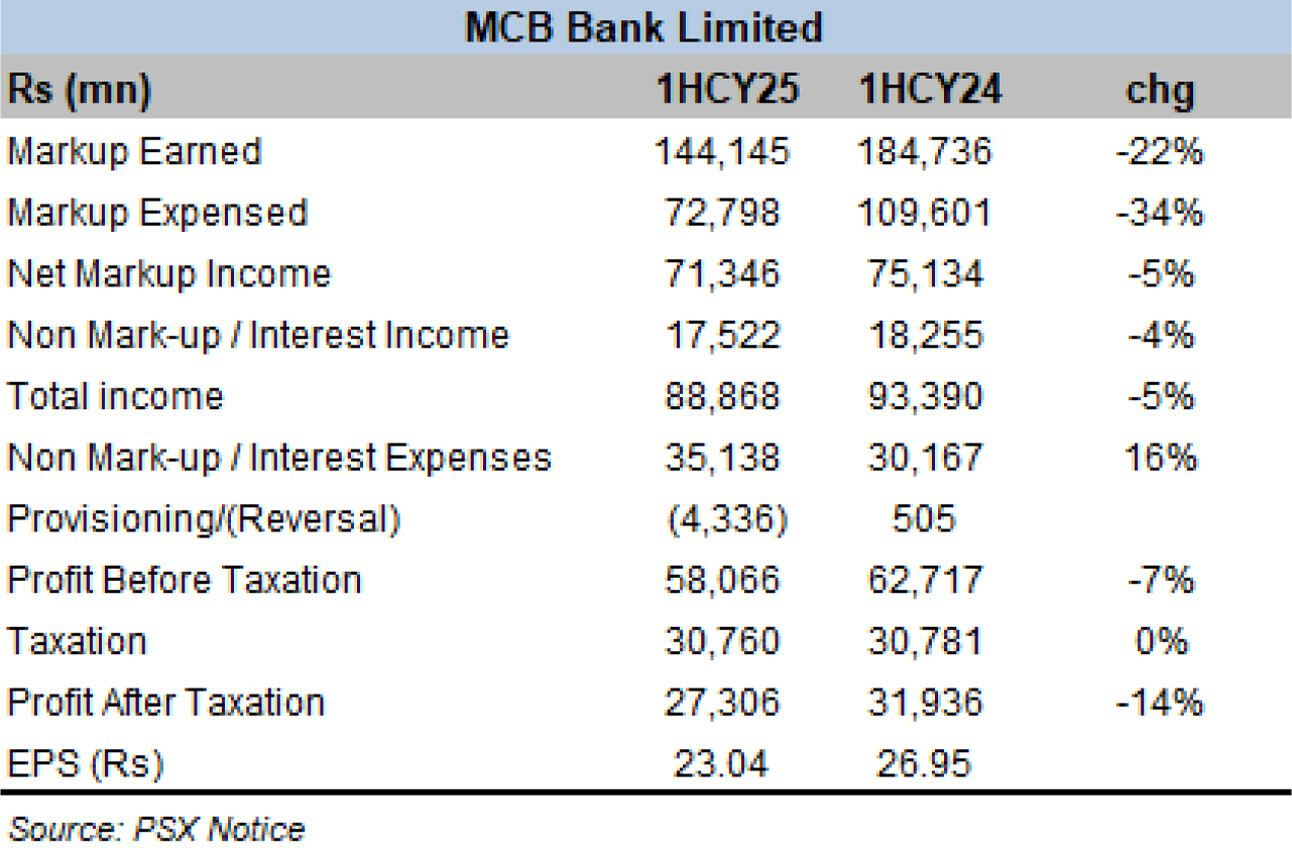
The bank recorded a 7 percent year-on-year dip in pre-tax profits, as pressure on markup income and high administrative expenses weighed on profitability. A significant reversal in provisioning charges arrested the slide and the bank continued with its rich payout legacy with another interim dividend, taking the year-to-date payout to Rs18/share.
The retreat from December end 2024 asset composition was always going to happen – but the pace of it appears too swift. Investments, primarily in government securities, crossed Rs2 trillion – a massive 78 percent jump from December 2024. Industry growth of investments during the same time is a little over 20 percent.
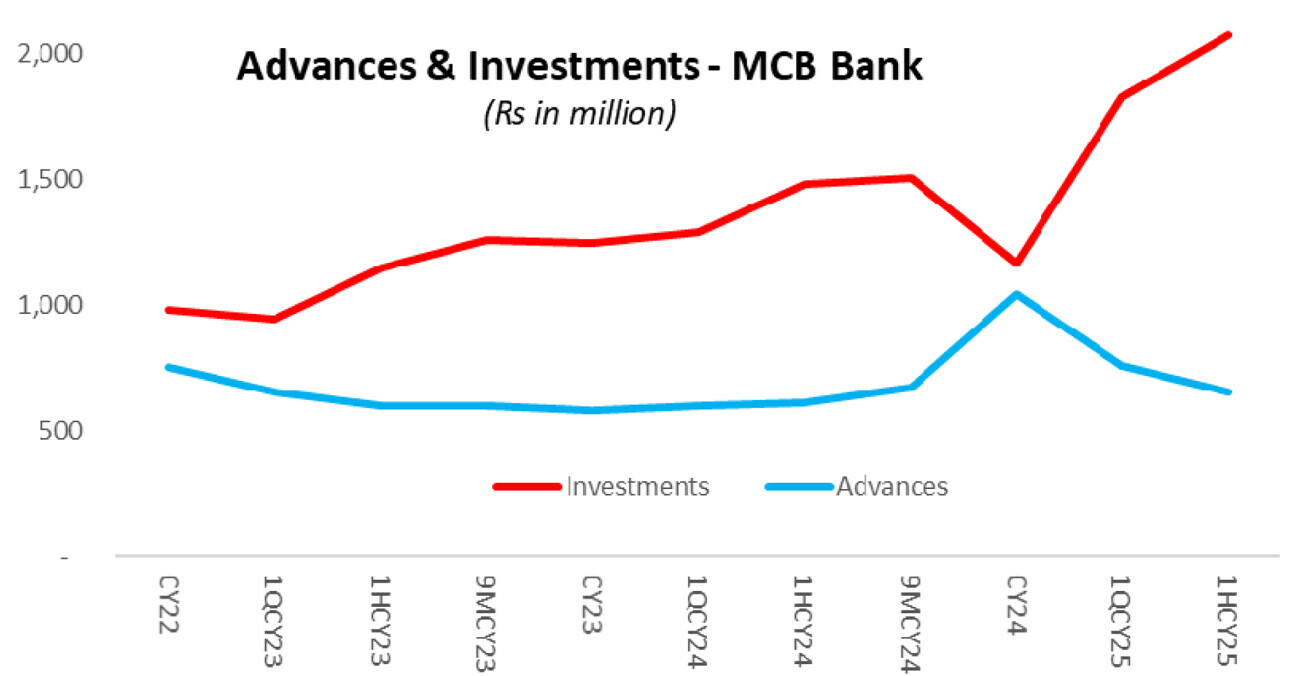
The investment to deposit ratio (IDR) crossed 90 percent – a number not usually associated with IDRs – as Rs900 billion were added to the investment portfolio over December 2024.
The advances portfolio received much less love as the penal tax on ADR threshold was not the hanging sword unlike 4QCY24. MCB’s advances dipped 37 percent over December 2024, shedding Rs385 billion – outpacing the industry wide drop in advances of 16 percent. The trajectory of both advances and investments should not surprise anyone. The magnitude may.
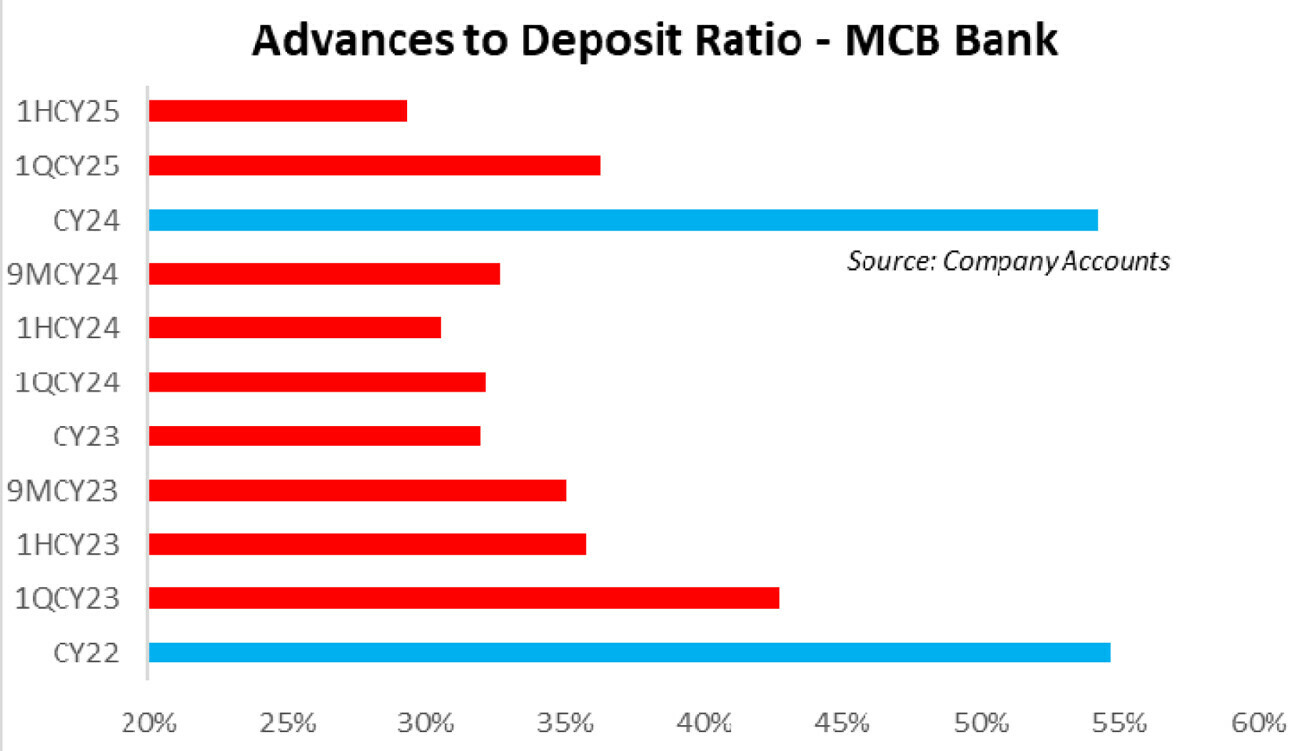
The ADR slipped under 30 percent – comfortably the lowest in a long time (if not ever). The macroeconomic a may well be looking up – genuine credit demand is still lagging even while the interest rates have been halved in less than a year.
On the liabilities side, deposits grew by 16 percent over December 2024, much in line with industry average.
Strongest growth came from low cost and no cost deposits, with the current account growth constituting 82 percent of all deposit growth, adding a staggering Rs256 billion over December 2024.The domestic cost of deposits, as a result, was halved from 10.76 percent a year ago to 5.23 percent during 1HCY25.
Such was the rush for investments in government securities, MCB added more to its borrowing portfolio than it did to the deposit base over December 2024. Another rarity in banking events.
On the profit and loss front, the cost-to-income ratio took a hit, as both markup and non-funded income remained lower year-on-year. MCB’s administrative costs stayed above period average inflation, which the bank puts down to talent, technology and marketing costs.
Infection and coverage ratio remain healthy. It is likely that the asset composition will again start to shift as the year deepens – but a mad rush of borrowers looking for financing is not a high probability in the near future.
The required thresholds of ADR will once again likely be met to avoid penalties – but won’t necessarily reflect a permanent shift in how banks have been banking for quite some while.




















Comments
Comments are closed for this article.