


SBP reviews
Pakistan's SBP doubled banks' Minimum Capital Requirement, citing rising costs and its role as a contractionary monetary tool. This move, potentially influenced by IMF conditions, aims to combat high inflation and stagflation risks.
- Reasons for the SBP's 100% MCR increase for banks.
- Factors driving banks' rising operating costs, including inflation and IMF conditions.
- The MCR's role as a contractionary monetary policy tool.
- The potential link between the MCR hike and IMF agreements.

EDITORIAL: The State Bank of Pakistan (SBP) has increased the Minimum Capital Requirement (MCR) for new and existing banks operating in Pakistan by 100 percent. The reason cited by the SBP is the rising operating costs associated with establishing and running financial institutions on a sustainable basis.
The MCR is a tool that ensures banks have sufficient liquid capital relative to their assets to remain solvent, and — equally importantly — to whether a potential financial crisis. In other words, it is designed to mitigate risks to depositors and support a stable financial system. Therefore, the explanation given by the central bank does have merit.
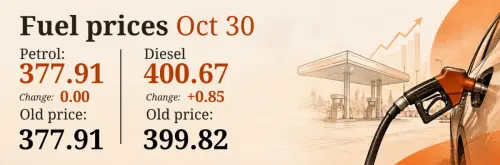
The question arises: why have banks witnessed a rise in their operating costs? The answer is fairly obvious. The Consumer Price Index (CPI) has been in double digits since earlier this year, partly due to the fallout from the ongoing Middle East crisis, and partly because of the substantial rise in administrative costs linked to International Monetary Fund (IMF) program conditions. These conditions require the government to ensure the full cost recovery of utilities, which in turn has raised costs across the board. Additionally, daily adjustments to the prices of petroleum and petroleum products are impacting transport costs.
Another factor could well be investments in specific sectors that are not generating the expected profits. In this context, it is relevant to note that Pakistani banks have been, and continue to be, overexposed to the energy sector. Their initial resistance to extending another 1.23 trillion-rupee loan last year to retire the massive energy circular debt—and to stagger its repayment—was eventually overcome; consequently, their costs may have risen dramatically.
However, acknowledging these factors does not detract from the fact that the MCR is also a monetary policy tool used to guide the economy. Thus, a rise in the MCR acts as a contractionary policy tool because it reduces the credit and money supply in circulation, whereas a reduction in the MCR is an expansionary policy designed to contain a recession.
So why was the MCR raised a day after the policy rate was increased by the Monetary Policy Committee? Is it because the central bank successfully convinced IMF staff that implementing a policy rate contraction well above 50 basis points to offset inflation would send the wrong signal to a market already struggling? After all, despite a registered growth rate of 3.7 percent, the economy is not backed by a rise in employment opportunities or domestic productivity. Instead, that growth reflects a rise in wholesale and retail trade driven by consumption, which is partly fuelled by smuggling across long, porous borders.
Thus, it stands to reason that the decision to double the MCR overnight—a day after the policy rate was hiked by 50 basis points—may stem from an agreement with the IMF, as outlined in the fourth review staff-level agreement published on the Fund’s website on October 7 of this year.
That being said, a contractionary policy is the suggested remedy during high inflationary pressures, while an expansionary policy is the suggested remedy during a recession. Given that inflation remains in double digits and major industries — including textiles, cement, and fertilizers — are under stress due to high input costs (as per an anecdotal survey by the Business Recorder), the country is experiencing and facing ongoing risks of stagflation. This explains why a contractionary monetary policy — raising both the MCR and the policy rate — is being implemented.
Copyright Business Recorder, 2026



Comments