


Remittance incentives
Pakistan's home remittances are vital for its economy, growing significantly due to incentives. A new lottery scheme aims to boost formal channels, with banks now bearing the cost, though its funding mechanism raises concerns.
- Pakistan's growing home remittances and economic impact.
- New Pasban Remittance Reward Scheme incentives.
- Concerns over lottery scheme's legality and funding.
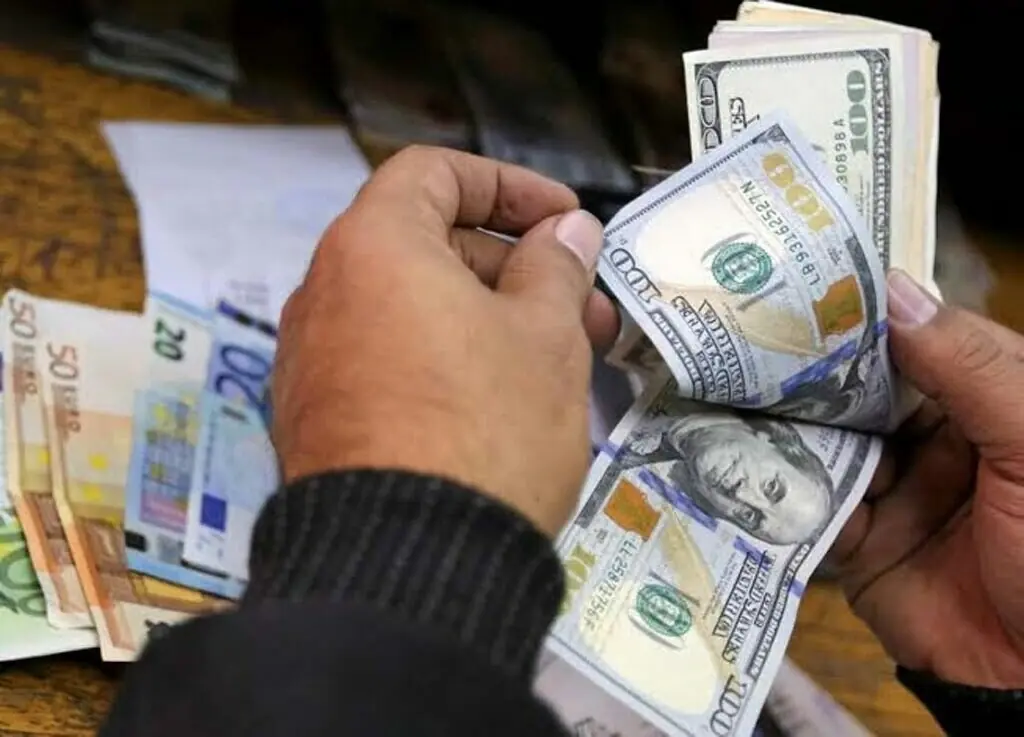
EDITORIAL: One of the prime reasons for balance of payments sustainability and the build-up of SBP’s forex reserves is the spectacular performance of home remittances, which grew from a low of $27.3 billion in FY23 to $41.6 billion in FY26. Even today, with GCC economies — from where over 50 percent of remittance flows come — under pressure due to war, the growth continues, and the total is likely to reach SBP’s target of $44 billion in FY27.
The government and SBP are incentivizing the formal segment to capture the share of the informal hundi-hawala market, and they are largely being successful. Earlier, the government provided a subsidy routed through banks, which has now been terminated. A new mechanism has now been devised under which banks are providing support on their own to ensure that the growth remains intact.
The buck doesn’t stop here, as SBP and PBA (Pakistan Banks Association) have recently announced a new lottery scheme known as the Pasban Remittance Reward Scheme, under which Rs16 billion in annual cash prizes are to be offered by banks to remitters. There would be 2,521 winners per quarter, receiving a total of Rs4 billion in cash. The idea is to encourage more people to use formal channels and become part of the lucky draws.
That is good. Evidence shows that remittance incentives do work. In 2009, the Pakistan Remittance Initiative (PRI) was jointly launched by SBP, the Ministry of Finance and the Ministry of Overseas Pakistanis to facilitate remittances through formal channels by making them faster and cheaper. That did work, as remittances have been on a steady growth path since then, compared to a mere $7.8 billion in FY09.
Thereafter, whenever government support was held back, the flows invariably moved to informal channels. The latest example is FY23 when the then PDM (Pakistan Democratic Movement) government rolled back the subsidy and remittances dipped from $31.3 billion in FY22 to $27.3 billion in FY23. Thereafter, the then caretaker government restarted the subsidy, and inflows started moving up again. There were other reasons for the dip and resurgence as well, but surely the lack of incentives was one of them.
Later, some banks had reportedly started exploiting the subsidy through excessive spending on marketing, which included foreign trips for local employees. Plus, the IMF and other stakeholders did not like this subsidy. Anyhow, it is now over, and banks are assuming the cost, which is making them more prudent and smarter in their spending. The fate of the new lottery scheme is similar.
Banks in Pakistan make more money than any other sector. However, increasingly, the business model relies on taking deposits from all over and investing primarily in government securities. The banks’ focus is on lowering costs by increasing the share of current accounts, which carry zero cost, and they attempt to mis-sell to consumers at times. On the other hand, private-sector credit is shrinking.
External-account vulnerabilities are the biggest exposure, and growing remittances are providing a cushion against them. Thus, it is a win-win for the government, SBP and banks to let the latter assume the cost and facilitate higher and more resilient formal remittances.
The system is working fine. Banks’ risk is associated with sovereign risk, as predominantly banks’ assets are deployed in government papers and securities. Thus, it is in the mutual interest of banks and the government to lower these risks.
It is, however, pertinent to point out that reward schemes based on a lottery have been held to be un-Islamic by the Islamic Ideology Council in the past. We wonder if this scheme has been announced after obtaining their approval.
Furthermore; to mitigate the cost of this scheme to the banks, the State Bank has withdrawn the condition of Minimum return on deposits held with the banks (Minimum Deposit Rate) that was restricted to 1.4 percent below the policy rate.
Henceforth, it would only apply to deposits in savings accounts of up to ten million only. For a country that suffers from a dismally low national savings rate this represents an unkind cut to the savers and penalises savings within the banking system above ten million rupees in an account. Thus, it is appropriate to let the banks bear the cost of incentives provided to remitters instead of making broader taxpayers and savers pay for them.
Copyright Business Recorder, 2026




Comments