


'Pakistan’s natural wealth could unlock trillion-dollar carbon, biodiversity market'
- Pakistan needs to create bankable and investable projects, says Faraz Khan, a sustainability professional who was conferred with the Order of the British Empire award in 2023 for his services to UK-Pakistan relations
Pakistan holds significant potential in the trillion-dollar global carbon and biodiversity credit market. Leveraging its natural resources and establishing robust frameworks are crucial for attracting green investments and achieving climate goals.
- Pakistan's potential in the global carbon and biodiversity credit market.
- Establishing robust frameworks and exchanges for carbon projects.
- Creating bankable, investable climate projects to attract capital.
- Connecting Pakistan's climate finance ecosystem with OIC investors.
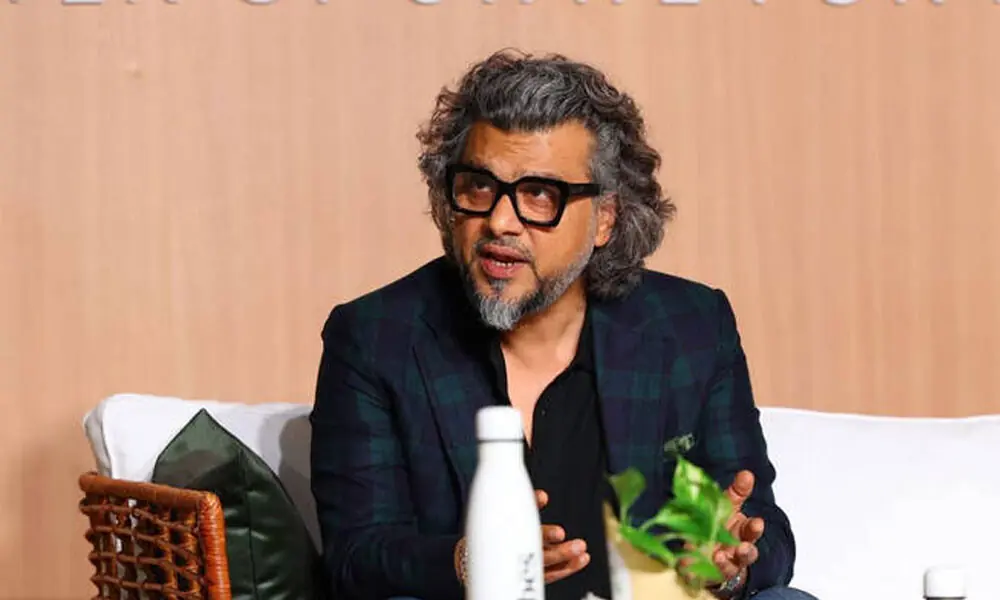
Boosting a varied biodiversity and natural resources, Pakistan has significant potential to tap into the global carbon and biodiversity credit market, which has emerged as a trillion-dollar asset class, said Faraz Khan, newly appointed Special Adviser on Climate Finance, Biodiversity, Carbon Credits and Tokenisation at the Islamic Chamber of Commerce and Development (ICCD).
Speaking exclusively to Business Recorder, he said Pakistan could leverage its biodiversity and natural resources to create value through carbon and biodiversity credits.
“Carbon credits and biodiversity credits … [have] emerged as a trillion-dollar asset class,” Khan said. “Pakistan’s biodiversity as an ecosystem has so much opportunity to create a leverage point, monetise and create that impact as well.”
Faraz Khan, who was conferred with the Order of the British Empire award in 2023 for his services to UK-Pakistan relations, is a sustainability professional with two decades of experience in the field who believes his Pakistani heritage will be a great asset in his new role.
He explained that biodiversity was a broader concept than carbon credits, encompassing areas including water, forestry, food security and circularity.
He said that carbon markets provide businesses with mechanisms to reduce or offset their emissions.
“Decarbonisation means when a business or an industry wants to reduce its carbon footprint by taking steps as per the regulations or through their own mandates to reduce its own carbon footprint.”
Meanwhile offsetting allows businesses to compensate for residual emissions through investments in projects such as forestry and other nature-based initiatives.
For Pakistan to unlock this potential, Faraz said, the country needed to establish a registry of carbon projects and ensure robust verification of the quality of carbon credits.
He pointed out that “exchanges like Saudi Arabia”, which has launched a voluntary carbon market (VCM), where they buy the carbon credits for their local entities to offset, can be replicated “in Pakistan”.
“Institutions like PSX, funds, Securities and Exchange Commission, all need to sit together with the climate ministry and the relevant ministries to create these kinds of exchanges to leverage the potential that Pakistan has in terms of carbon and biodiversity credits,” Faraz said.
His remarks come as Pakistan actively develops its carbon market as a key strategy to achieve climate goals, attract green investments, and transition towards a low-carbon economy.
In December 2024, the federal cabinet approved policy guidelines for carbon market trading. Pakistan’s carbon markets became functional in early 2025, following the approval of federal guidelines under Article 6 of the Paris Agreement.
Last year, the Pakistan government launched its first sovereign Green Sukuk to generate much-needed capital. Terming it “a positive step”, Faraz pointed out the Sukuk alone cannot address challenges on climate finance in Pakistan.
“But it shows that Pakistan is in a position to not only launch a vehicle like this, but also create an ecosystem as well.”
Faraz noted that Pakistan’s regulatory environment was also moving in the right direction. “We got our Pakistan green taxonomy, green banking guidelines, IFRS S1, S2 rolled out.”
However, he said Pakistan needs to create bankable and investable projects, calling it a major challenge in attracting international climate capital.
“Now the challenge that we face…. is creating a pipeline of bankable, investable projects that are aligned with global jurisdictions, investor mandates and local regulations as well.
“So creation of these bankable projects and then taking them to the right kind of investors with the right mandates is the next step. And I think Pakistan is very much geared to embark on that journey.”
However, climate finance is not simply about financial returns, says Faraz, but also involves generating measurable impact through resilience, mitigation and adaptation.
Globally, biodiversity finance is gaining greater attention as policymakers and investors increasingly recognise nature-related risks. A study published in Nature Ecology & Evolution in June found that biodiversity loss and ecosystem degradation could have significant implications for sovereign creditworthiness and financial markets, leaving $83 trillion in global sovereign debt vulnerable.
For Pakistan, Faraz, said the opportunity lies in connecting its emerging climate-finance ecosystem with investors across OIC countries, i.e. KSA, Syria, through the ICCD network.
“Pakistan’s brand and positioning in today’s world is definitely a power to reckon with. So from the brand Pakistan perspective, we are in a very, very good place,” said Faraz.
He identified three immediate priorities for his ICCD role: bridging the knowledge gap and simplifying climate-finance concepts, mobilising climate-finance investors towards suitable projects, and creating actual transactions.
“There is a lot of talk historically on climate transition and climate finance, but the quantum of actual transactions is not matching with the conversations,” Khan said, adding that converting Pakistan’s climate and biodiversity potential into investable projects would be key to turning this opportunity into tangible financial flows.







Comments