


Copper slips as inventories build; weak dollar offers support
- Benchmark three-month copper on the London Metal Exchange was down 0.4% at $13,988 a metric ton
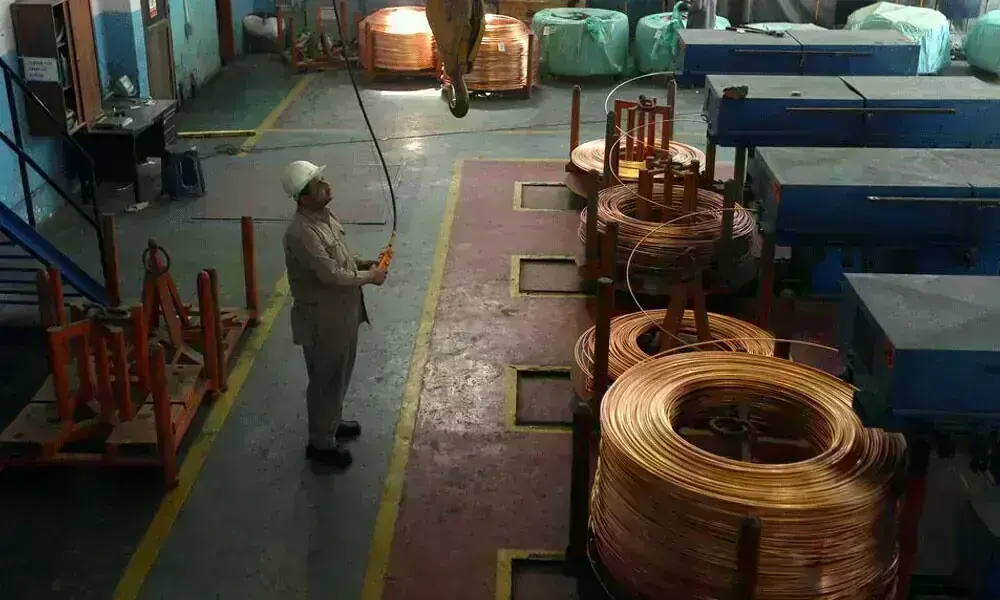

LONDON: Copper prices slipped on Thursday as more inventories arrived in warehouses, but losses were modest due to a weaker dollar after the U.S. government moved to calm the bond markets.
Benchmark three-month copper on the London Metal Exchange was down 0.4% at $13,988 a metric ton by 1025 GMT, having added 0.5% in the previous session.
LME copper hit a six-month peak on Monday on worries about low inventories, but has eased since then as a flow of metal replenished storage facilities.
“Yesterday’s buyback announcement from the Treasury helped arrest the slide that we saw as inventories started to return to the LME,” said Ole Hansen, head of commodity strategy at Saxo Bank in Copenhagen.
“The announcement sends quite a strong signal and points to the risk of a weaker dollar ahead. It also highlights a world where there’s competition for investors not only to fund debt, but also for hard assets, and copper has been at the forefront of that recently.”
The dollar index fell to a three-month low after the Treasury Department moved to calm a bond market selloff that had pushed long-end yields to their highest since 2007.
A weaker dollar makes commodities priced in the U.S. currency cheaper for buyers using other currencies.
The most-traded copper contract on the Shanghai Futures Exchange edged 0.2% higher to 107,200 yuan ($15,943.13) a ton.
LME copper inventories rose by another 3,950 tons, data showed on Thursday, bringing the gains over the past week to 17%.
On-warrant copper stocks, meaning metal not already earmarked for warehouse removal, on the LME have surged by more than 50% since the start of the week, but are still less than half their levels three months ago.
Among other metals, LME aluminium lost 1% to $3,196 a ton and nickel shed 1.3% to $16,890, while zinc gained 1.2% to $3,751, lead rose 0.1% to $1,890 and tin added 0.3% to $55,705.













Comments