


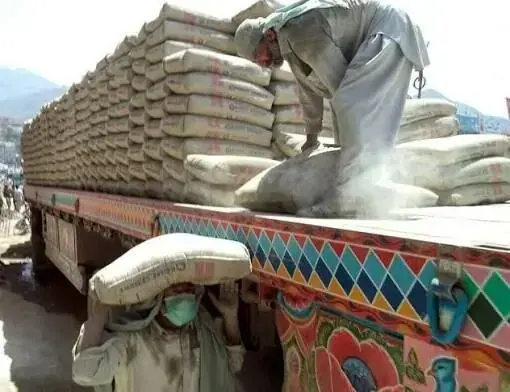
KARACHI: Profitability of Pakistan’s cement sector is projected to increase 2 percent year-on-year to Rs29.6 billion in the first quarter of fiscal year 2026-27, supported by higher cement offtakes and increased retention prices, according to a research report.
The report by AKD Securities Limited forecasts revenue for its cement companies to rise 15 percent year-on-year to Rs141.2 billion in 1QFY27, compared with Rs122.6 billion in the same period last year. The projected increase reflects 2 percent growth in cement offtakes and a 10 percent rise in cement prices.
Gross profit is expected to increase 17 percent to Rs47.2 billion from Rs40.3 billion, while the gross margin is projected to improve to 33.5 percent from 32.9 percent a year earlier. AKD attributed the expected margin improvement primarily to a higher proportion of domestic sales and increased retention prices, which are likely to offset higher coal prices and transportation costs.
Operating expenses are projected to rise 8 percent year-on-year to Rs8.1 billion, while other income is expected to decline 5 percent to Rs12.6 billion from Rs13.2 billion. Finance costs are forecast to double to Rs5.2 billion from Rs2.6 billion, while profit before tax is projected to increase 2 percent to Rs43 billion. Taxation is expected to rise 4 percent to Rs13.5 billion, taking the effective tax rate to 31.3 percent from 30.8 percent. Net profit is consequently forecast at Rs29.6 billion, compared with Rs29.1 billion in 1QFY26.
On a quarter-on-quarter basis, sector revenue is projected to increase 13 percent from Rs125.1 billion in 4QFY26. Gross profit is expected to rise 4 percent from Rs45.6 billion, while operating expenses are forecast to fall 10 percent to Rs8.1 billion from Rs9 billion. Other income is projected to increase 13 percent to Rs12.6 billion, while finance costs are expected to rise 38 percent to Rs5.2 billion. Profit before tax is forecast to increase 9 percent to Rs43 billion, taxation to rise 25 percent to Rs13.5 billion and net profit to increase 2 percent from Rs28.9 billion in the preceding quarter. The gross margin, however, is projected to decline from 36.4 percent in 4QFY26 to 33.5 percent in 1QFY27.
Among individual companies, AKD expects Maple Leaf Cement Factory Limited (MLCF), Fauji Cement Company Limited (FCCL), D.G. Khan Cement Company Limited (DGKC) and Pioneer Cement Limited (PIOC) to post year-on-year earnings growth. Their earnings per share are forecast at Rs3.0, Rs1.9, Rs5.7 and Rs8.3, respectively, representing increases of 14 percent, 42 percent, 16 percent and 48 percent.
AKD said the expected earnings growth at these companies was primarily driven by higher offtakes and retention prices as manufacturers passed on cost pressures. MLCF, DGKC and PIOC recorded year-on-year offtake increases of 2 percent, 19 percent and 7 percent, respectively, during the quarter. FCCL’s total offtakes, however, declined 3 percent year-on-year because of the absence of exports, although its domestic sales increased.
Looking ahead, AKD projects local cement offtakes to grow approximately 8 percent year-on-year in FY27, supported by the availability of cheaper financing under government schemes, improving income levels, favourable fiscal policy and a possible easing of construction costs if tensions in the Middle East de-escalate. The brokerage said cement manufacturers’ ability to pass on cost increases amid strong demand could support sector margins. However, it identified a prolonged Middle East conflict and elevated oil and coal prices as key risks to demand and profitability.
Copyright Business Recorder, 2026












Comments