



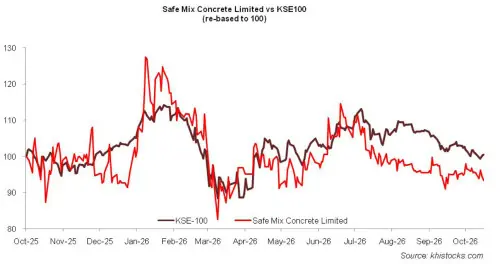
Safe Mix Concrete Limited (PSX: SMCPL) was incorporated in Pakistan as a private limited company in 2005 and was ultimately converted into a public limited company in 2007. The company is engaged in the manufacturing and sale of ready mix concrete, building blocks as well as construction of factories, prefabricated buildings and other construction sites. SMCPL is a company of Arif Habib Group and is the supplier of ready mix concrete for the group’s mega project – Naya Nazimabad.
Pattern of Shareholding
As of June 30, 2026, SMCPL has a total of 25 million shares outstanding which are held by 1068 shareholders. Mr. Abdus Samad Habib, the CEO of SMCPL holds 35.84 percent shares of the company followed by Arif Habib Corporation Limited holding 27.63 percent shares of the company. Local general public also accounts for 27.63 percent shares of SMCPL. The remaining shares are held by other categories of shareholders.
Historical Performance (2021-26)
Over the period under consideration, SMCPL’s topline tumbled only in 2021 and 2024. After posting net losses in 2019 and 2020, SMCPL posted net profit in the subsequent years with the highest net profit registered in 2023. In 2024 and 2025, net profit inched down which greatly recovered in 2026. The margins which were also plunging until 2020 recovered in 2021 and reached their highest level in 2023. In the following years, SMCPL’s margins ticked down. The detailed performance review of the period under consideration is given below.
In 2021, SMCPL’s topline petered out by 45.97 percent year-on-year to clock in at Rs.221.23 million. During 2021, the company not only reduced its production capacity from 1.47 million cubic meters to 0.876 million cubic meters but also utilized only 5.87 percent of the available capacity. Steps were being taken by the government for the promotion of housing sector in the country.
While significant number of projects was launched in the northern wing of the country, the southern region still remained quiet. Cost of sales also shrank by 51.8 percent year-on-year in 2021 mainly on account of the management’s focus on reducing its fixed overhead cost. This resulted in gross profit of Rs.17.63 million in 2021 as against gross loss of Rs. 13 million recorded in the past year. GP margin clocked in at 7.97 percent in 2021. The company didn’t incur any sales commission related to KMC in 2021. Impairment loss of financial assets also considerably tumbled during the year resulting in 99 percent year-on-year drop in distribution expense in 2021. Administrative expense tumbled by 23.78 percent year-on-year in 2021 mainly on account of reduction in payroll expense. Other income dwindled by 42 percent year-on-year in 2021 due to lesser pumping and grout charges, curtailed deferred income and lesser profit on deposit accounts due to low discount rate. This resulted in operating profit of Rs.8.22 million in 2021 with OP margin of 3.71 percent. This was against the operating loss of Rs. 97.07 million recorded in 2020. Although finance cost contracted by 25.88 percent year-on-year in 2021 due to monetary easing, however, it didn’t allow the positive operating profit to cascade down resulting in loss before tax of Rs.1.39 million in 2021. Deferred taxation pushed the bottomline into profit zone in 2021. SMCPL recorded net profit of Rs.6.57 million in 2021. NP margin clocked in at 2.97 percent while EPS stood at Rs.0.26 in 2021. This was against the net loss of Rs.98.78 million and loss per share of Rs.3.95 recorded in 2020.
After two years of lackluster sales, SMCPL’s topline posted a strong rebound of 139.44 percent in 2022 to clock in at Rs. 529.72 million. This was on the back of higher sales volume as well as upward price revision. During the year, the company increased in capacity to 918,000 cubic meters and utilized 10.8 percent of its capacity owing to strong demand. High cost of raw materials, fuel and power charges and Pak Rupee depreciation pushed the cost of sales up by 104.4 percent in 2022. Yet gross profit multiplied by 544 percent in 2022 with GP margin clocking in at 21.44 percent. Higher sales commission as well as travel charges resulted in 350.86 percent hike in distribution expense in 2022. Administrative expense also surged by 83 percent year-on-year in 2022 owing to high inflation and induction of additional human resources during the year. Other income massively increased by 78.56 percent year-on-year in 2022 on account of higher grouting income as well write-off of liabilities no longer payable. Operating profit posted a staggering growth of 987.93 percent in 2022 with OP margin of 16.87 percent. Finance cost grew by 88 percent year-on-year in 2022 due to multiple rounds of monetary tightening during the year and also because the company undertook significant capital expenditure during the year to increase the transit mixers. SMCPL’s net profit enhanced by 607.64 percent in 2022 to clock in at Rs.46.456 million with NP margin of 8.77 percent. EPS climbed to Rs. 1.86 in 2022.
2023 was characterized by tamed construction activities in the country due to low PSDP spending, rise in construction cost and low purchasing power of consumers due to high inflation, unprecedented level of discount rate, political havoc and sluggish economic activity. Despite all the odds, SMCPL’s topline posted a stunning year-on-year growth of 170.34 percent in 2023 to clock in at Rs.1432.03 million. This was due to the fact that the majority of SMCPL’s sales were made to its related parties which included Javedan Corporation Limited. SMCPL achieved capacity utilization of 14.76 percent in 2023 by producing 135,534 cubic meters, up 36.94 percent year-on-year. Cost of sales surged by 166.90 percent year-on-year in 2023, however, high volumetric sales and elevated prices resulted in 182.92 percent year-on-year growth in gross profit with GP margin clocking in at 22.43 percent in 2023. Administrative expense multiplied by 55.53 percent year-on-year in 2023 due to high payroll expense driven by high inflation. Distribution expense escalated by 99.15 percent in 2023 due to elevated sales commission, advertising & promotion budget as well as travelling charges. Other expense considerably grew by 494 percent year-on-year in 2023 due to higher provisioning don for WPPF and ECL.
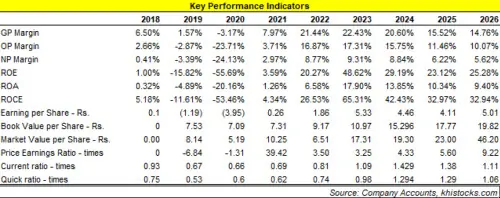
The company also wrote off assets, receivables and advances during the year which also contributed in driving up other expense. Other income slid by 20.83 percent in 2023 due to high-base effect as the company recorded write-back of liabilities, gain on final settlement with CDGK and write off of recovery of receivables in 2022. SMCPL’s operating profit grew by a massive 177.32 percent year-on-year in 2023 while OP margin clocking in at 17.31 percent – the highest level during the period under consideration. Finance cost grew by 126.45 percent year-on-year in 2023 due to high discount rate although the company paid off its entire short-term liabilities during the year and instead obtained loan from related parties. Net profit substantially grew by 187 percent in 2023 to clock in at Rs.133.37 million with EPS of Rs.5.33 and NP margin of 9.31 percent.
In 2024, SMCPL’s net sales declined by 11.84 percent year-on-year to clock in at Rs.1262.48 million. This was on account of slowdown of the ongoing projects due to unprecedented level of discount rate and high cost of raw materials. During the year, the company’s production slid by 22.45 percent to clock in at 105,100 cubic meters. This resulted in capacity utilization of 11.45 percent in 2024. Cost of sales slid by 9.75 percent in 2024. This translated into 19.05 percent lower gross profit recorded by the company in 2024. GP margin also contracted to 20.60 percent in 2024. Administrative expense multiplied by 8.71 percent in 2024 mainly on account of penalties paid for the termination of lease. Distribution expense dipped by 2.82 percent in 2024 due to lower sales commission incurred on the back of petite sales volume achieved during the year. The company also considerably squeezed its advertising & promotion budget in 2024. Other expense dwindled by 47.96 percent in 2024 due to high-base effect as the company wrote off long outstanding advances and receivables in the previous year. Provision for WPPF also slid in 2024 contributing to lower other expense. Other income also ticked down by 8.7 percent in 2024 due to high-base effect as the company wrote back liabilities in 2023. SMCPL’s operating profit slumped by 19.76 percent in 2024 with OP margin falling down to 15.75 percent. Finance cost surged by 27.77 percent in 2024 due to high discount rate. SMCPL’s net profit tumbled by 16.32 percent year-on-year to clock in at Rs.111.606 million in 2024 with EPS of Rs.4.46. NP margin also inched down to 8.84 percent in 2024.
In 2025, SMCPL’s topline multiplied by 30.85 percent to clock in at Rs.1652.01 million. This was on account of recovery witnessed in the macroeconomic indicators which provided impetus to the construction activity in the country. Some of the major customers of SMCPL in terms of revenue are Global Residency Reit, Naya Nazimabad Apartment Reit, Shayan Builders and Directorate (DTE) of Housing. Cost of sales mounted by 39.23 percent in 2025 due to high cost of raw materials and elevated energy tariff. This pushed gross profit down by 1.43 percent in 2025 with GP margin sliding down to 15.52 percent. Administrative expense surged by 17 percent in 2025 due to higher payroll expense incurred during the year. Workforce was expanded from 40 employees in 2024 to 45 employees in 2025. Selling expense escalated by a massive 312 percent in 2025 due to higher sales volume which translated into increased sales commission. Other expense slid by 64.74 percent in 2025 due to lower ECL related provisioning done during the year. Other income also deteriorated by 26.73 percent in 2025 due to thinner profit on saving deposits and no doubtful debts recovered during the year. SMCPL recorded 4.81 percent decline in its operating profit in 2025 with OP margin falling to 11.46 percent. Finance cost diminished by 28.55 percent in 2025 due to lower discount rate. SMCPL recorded net profit of Rs.102.714 million in 2025, down 7.97 percent year-on-year. This translated into EPS of Rs.4.11 and NP margin of 6.22 percent in 2025.
Recent Performance (2026)
In 2026, SMCPL recorded 34.83 percent improvement in its net sales which clocked in at Rs.2227.39 million. This was on account of improvement in the real-estate and construction activities in the country. The company was able to acquire a greater share of the market by offering competitive pricing which was possible through operational efficiency and cost cutting measures. SMCPL has discontinued the hiring of rented Transit Mixers (TMs) from October 2025 which resulted in lower rental and related costs. However, continuous increase in fuel, energy and other raw material costs alongside elevated transportation charges and supply chain impediments due to Middle Eastern crisis took its toll on the gross margin of the company which slid to 14.76 percent in 2026. This was despite 28.25 percent improvement recorded in gross profit in absolute terms in 2026. Administrative expense spiked by 40.84 percent in 2026 due to higher payroll expense which was the result of inflationary pressure and workforce expansion to 56 employees. Greater sales volume translated into elevated sales commission which pushed up the distribution expense by 151.60 percent in 2026. Lesser provisioning done for ECL resulted in 34.62 percent decline in other expense in 2026. Other income also weakened by 32.43 percent in 2026 due to lesser profit on saving accounts and lower rental income. Operating profit improved by 18.45 percent in 2026, however, OP margin slipped to 10 percent. 3 percent uptick in finance cost recorded in 2026 was the result of increased long-term borrowings. Net profit clocked in at Rs.125.27 million in 2026, up 21.96 percent year-on-year. This translated into EPS of Rs.5.01 and a relatively weaker NP margin of 5.62 percent in 2026.
Future Outlook
Relatively higher PSDP disbursement and gradual development see in domestic economy will buttress the industrial and construction activities in the country. This coupled with the company’s religious focus on operational efficiency and adding more transit mixers to its fleet may enable it to offer competitive prices to its customers and grab a greater chunk of the market share. However, geopolitical tensions and the associated increase in fuel and raw material prices and supply chain disruptions pose downside risk to SMCPL.













Comments