


Inflation rebound to keep interest rates honest
Consumer price inflation surged to 11.1% in August, driven by rising fuel and wheat prices. This reinforces a cautious monetary policy stance, making rate cuts unlikely and potentially leading to further hikes.
- Rising fuel and wheat prices.
- Persistent core and food inflation.
- Impact of global energy prices.
- Monetary policy and potential rate hikes.

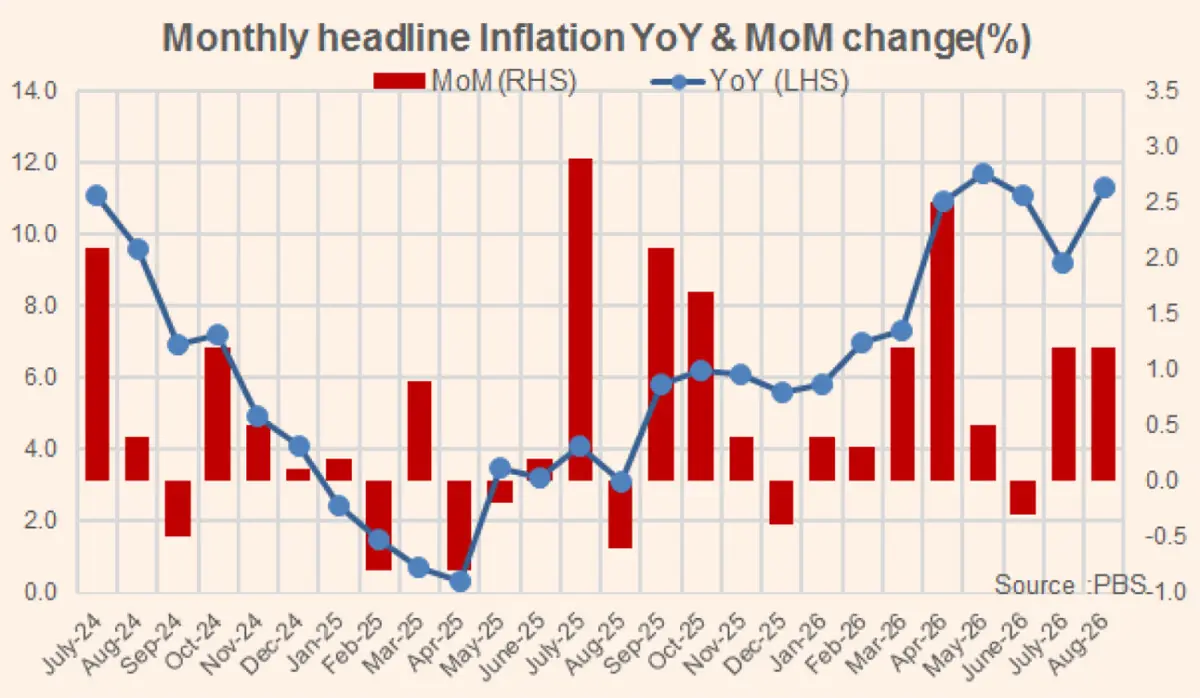
As expected, consumer price inflation is inching up again, driven by rising fuel prices and their indirect impact, alongside a continuous increase in wheat prices. Headline inflation returned to double digits after a gap of one month, clocking in at 11.1 percent in August, compared to 9.2 percent in July.
On a month-on-month basis, inflation remained above 1 percent for the second consecutive month, rising 1.2 percent. This reinforces the SBP’s cautious stance on monetary policy, as inflation is expected to remain above its medium-term target of 5-7 percent during FY27. More importantly, the risks remain skewed to the upside amid the ongoing US-Iran war and elevated international energy prices.
Core inflation also remains sticky, staying within the 8-9 percent range for the fifth consecutive month. It stood at 8.8 percent for urban consumers and 8.5 percent for rural consumers, suggesting that underlying price pressures have yet to meaningfully ease.
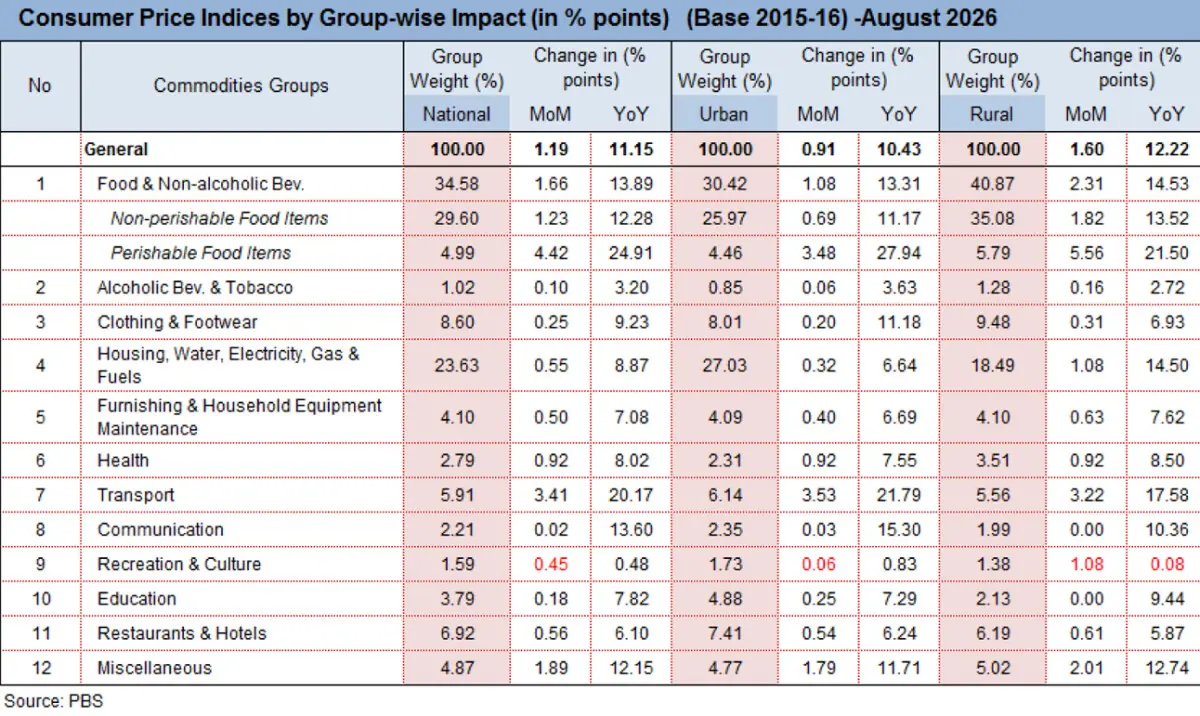
Food inflation rose 1.7 percent MoM, with non-perishable food prices increasing 1.2 percent and perishables jumping 4.4 percent. The pressure was more pronounced in rural areas, where food prices rose 2.3 percent over the previous month. Onion prices increased 48.4 percent, potatoes 10.6 percent and eggs 10.4 percent. Some of this increase is seasonal and could revert towards the mean, while higher transportation costs are also feeding into food prices.
The more persistent concern, however, is wheat. Prices rose 7.7 percent MoM in rural areas and 5.3 percent in urban areas. On a yearly basis, wheat prices are up a staggering 87 percent for urban consumers and 73 percent for rural consumers. Higher international prices, coupled with low government stocks, are keeping wheat prices elevated and are likely to continue dragging on overall food inflation.
Transportation recorded the largest monthly increase, rising 3.4 percent MoM, while the annual increase reached 20.2 percent. Persistently elevated international petroleum prices remain the key culprit. The impact is not fully captured by looking at crude prices alone, as refining crack margins, particularly for HSD, remain elevated. This is keeping domestic petroleum prices high, while the government continues to maintain petroleum levy collections rather than fully passing through any decline in underlying costs.
The concern is that these pressures are gradually changing inflation expectations and feeding into broader-based inflation. The most visible impact is currently on perishables, but pressures are also emerging elsewhere. Water supply charges increased 4.2 percent MoM, while electricity charges rose 1.7 percent as higher fuel costs continued to keep FCA elevated. Oil and gas prices remain the common denominator.
On a yearly basis, LPG prices are up 56 percent, while motor fuel prices have increased 25 percent. If the upward trend in energy prices persists, the impact is likely to broaden further across the inflation basket. Much will depend on the trajectory of the US-Iran conflict, with disruptions around the Strait of Hormuz and alternative supply routes keeping upward pressure on global energy prices.
The external account is also feeling the pressure. Higher import prices are pushing the REER upward, with the index now close to 108, largely reflecting the recent acceleration in domestic inflation. To bring the REER back towards 100, the PKR/USD exchange rate would likely need to cross the 300 mark, assuming other variables remain broadly unchanged.
The government remains reluctant to allow meaningful currency depreciation. By allowing the nominal exchange rate to gradually appreciate instead, the SBP has little room to loosen monetary policy without risking renewed pressure on the external account. At August’s inflation level, the real policy rate is barely 0.4 percent positive. Based on expected FY27 inflation, the real rate is currently around 2-3 percent, and the SBP is unlikely to allow it to fall materially below these levels.
In other words, rate cuts over the next few reviews look increasingly difficult to justify. If inflation and external pressures persist, the risk may instead be tilted towards another rate hike.



















Comments