


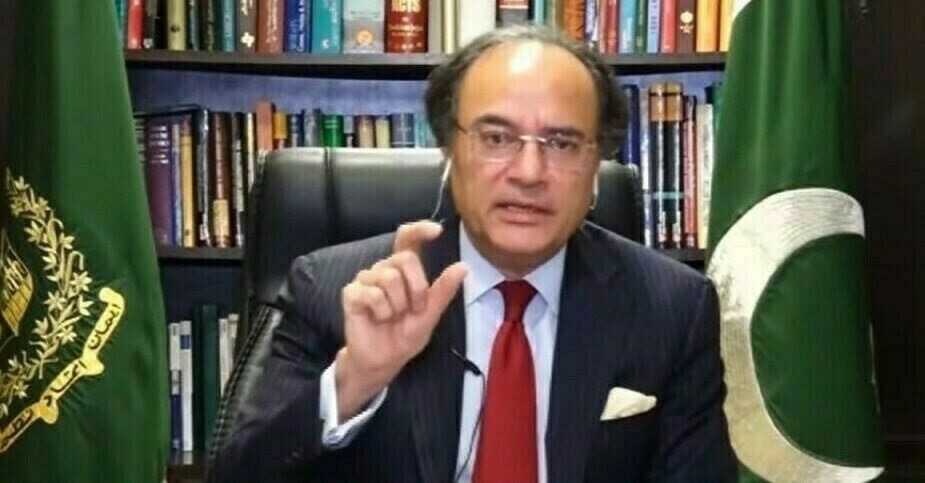
EDITORIAL: According to Federal Finance Minister Muhammad Aurangzeb, the country has embarked on a fundamental shift from reactive policymaking to a forward-looking one: a reform-driven approach to strengthen the economy, restore investor confidence and come up with modalities for sustainable growth.
There is abundant historical evidence that nearly all the country’s economic managers — be they economists, bankers or accountants — dealt with the periodic boom-bust cycles by seeking International Monetary Fund (IMF) programme lending.
Pakistan is currently on the twenty fourth programme, followed by adherence to the agreed politically challenging reforms (unless the Fund threatened suspension) till the balance of payment position improved and then abandon the programme, followed by a reversal of all the reforms.
Past IMF programme loan designs have changed little (in spite of seismic changes as the world moved from uni-polarity to multi-polarity) though as the Pakistan economy became more fragile the conditions are harsher and more upfront than previous programmes; and the incumbent finance minister has agreed to and is implementing the conditions of the ongoing programme loan.
One would have hoped that he had proposed in-house out of the box project design changes that included: (i) the delinking of the discount rate with the objective of controlling inflation as the major borrower of commercial banks is the government (and not the private sector) with the loans used to fund current expenditure that accounts for over 93 to 95 percent of the annual budgetary outlay — a highly inflationary policy; one would urge the finance minister to slash current expenditure by at least two trillion rupees for two years that would require sacrifices from the elite; (ii) the containment of current expenditure this year is on the back of the expectation that the discount rate would be lower than the current 11 percent in spite of the fact that all Fund press releases urge the necessity of “maintaining an appropriately tight and data dependent monetary policy”.
In this context, it is relevant to note that the Finance Minister during a recent parliamentary committee meeting did raise the distinct possibility of a decline in the discount rate by the end of the calendar year; (iii) the focus on raising total revenue rather than structural changes in the tax system, given that 75 to 80 percent of all taxes are indirect in this country whose incidence on the poor is greater than on the rich, which is contributing to inflation.
The gains in the stock market are cited as indicative of the restoration of investor confidence; however, October Monthly Update and Outlook, released by the Finance Division noted a decline of 64.5 percent in total foreign investment — 55.5 percent accounted for by a decline in direct foreign investment and the rest by portfolio investment in spite of the high discount rate in Pakistan compared to regional competitors.
Growth for last fiscal year was higher than originally estimated — 3 percent instead of 2.6 percent — and it was sourced mainly to the services sector (largely comprising wholesale and retail trade or non-productive sectors); while large-scale manufacturing sector’s (LSM’s) growth was on the back of a decline in inventories and in three sub-sectors not likely to be sustained — automobile sales rose due to additional taxes (including the climate tax), the cement exports to Afghanistan (which are likely to taper off this year due to the stalled talks) and food (due to the supply disruption of perishables due to floods).
To conclude, the gains to-date are mostly debt-driven and one would hope that the Finance Minister can convince Fund staff to correct design flaw policies, which would ensure that they are sustained.
Copyright Business Recorder, 2025





















Comments
Comments are closed for this article.