



Engro Polymer & Chemicals Limited (PSX: EPCL) was incorporated in Pakistan in 1997. EPCL is a subsidiary of Engro Corporation which is a subsidiary of Dawood Hercules Corporation Limited. The company is engaged in the manufacturing, marketing and selling of Poly Vinyl Chloride (PVC), Caustic Soda, Vinyl Chloride Monomer (VCM) and related products.
The company also has a captive power plant and water recycling plant in its integrated chemical complex. The surplus power produced by the company is also supplied to Engro Fertilizers Limited.
Pattern of Shareholding
As of December 31, 2025, EPCL has 908.92 million shares outstanding which are held by 32,939 shareholders. Associated companies, undertakings and associated companies have the majority stake of 77.35 percent in the company. Within this category, Engro Corporation Limited took the lead, followed by Mitsubishi Corporation.
Local general public accounts for 15.21 percent of the company’s shares followed by Insurance companies holding 4.45 percent shares. The remaining shares are held by other categories of shareholders.
Financial Performance (2019-2025)
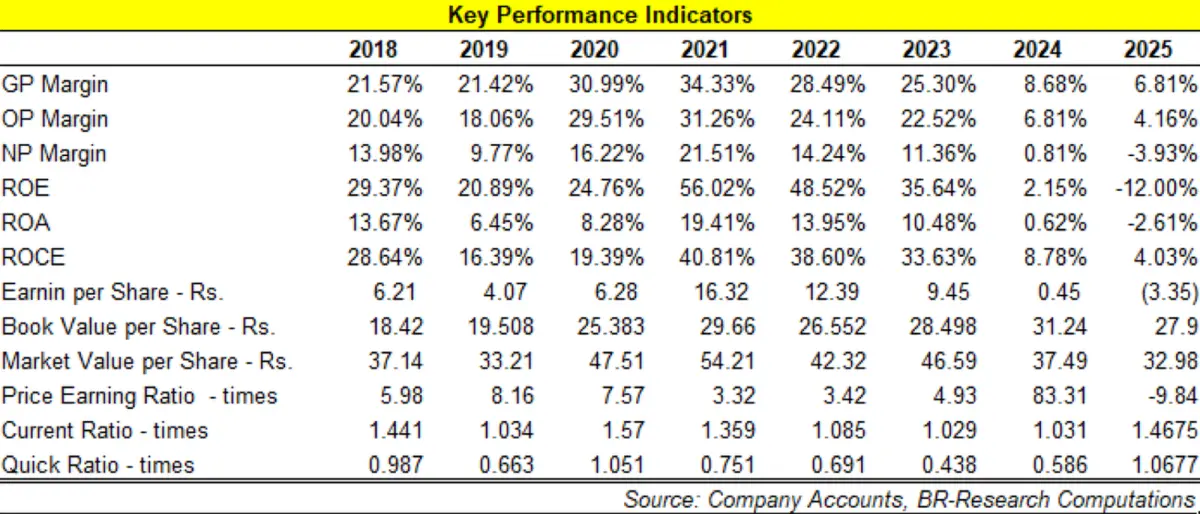
Over the period under consideration, EPCL’s topline posted year-on-year growth in 2019, 2021, 2022 and 2025. Its bottomline posted growth only in 2020 and 2021. EPCL registered net loss in 2025. The company’s margins which dwindled in 2019 posted significant growth for the subsequent two years. This was followed by a drastic fall in margins since 2022. EPCL’s margins hit their lowest ebb in 2025 (see the graph of profitability ratios).
The detailed performance review of the period under consideration is given below.
In 2019, EPCL’s topline posted year-on-year uptick of 7.27 percent to clock in at Rs37,836.63 million. The paltry topline growth was due to a slowdown in the PVC market owing to deteriorated construction activities in the country and the dumping of PVC from other sources.
Chlor Alkali market also declined during the year owing to CNIC requirement, imposition of sales tax on local sales and also because of gas curtailment… During the year, the sales volume of PVC and caustic soda dipped by 6 percent and 4 percent respectively to clock in at 191 KT and 83 KT.
In 2019, caustic flake facility also came online and registered sales volume of 1KT particularly in the export market. Cost of sales grew by 7.47 percent in 2019 due to inflation, Pak Rupee depreciation and higher gas prices.
However, the company’s ability to venture into a high margin export market and implementation of cost control measures resulted in 6.54 percent improvement in gross profit in 2019 with GP margin clocking in at 21.42 percent versus GP margin of 21.57 percent recorded in the previous year.
Distribution expense inched up by 1.78 percent in 2019 due to higher salaries of sales force coupled with increased travelling, conveyance and training charges incurred during the year.
Administrative expense inched down by 1 percent in 2019 due to lower payroll expense despite workforce expansion from 455 employees in 2018 to 508 employees in 2019. Other expense mounted by 49.94 percent in 2019 due to higher exchange loss. Other income dipped by 25.54 percent in 2019 mainly because of high-base effect as the company recorded insurance income recognized in the previous year on account of business interruption.
EPCL recorded 3.34 percent decline in its operating profit in 2019 with OP margin clocking in at 18 percent versus OP margin of 20 percent recorded in the previous year. Finance cost surged by 196.22 percent in 2019 on the back of high discount rate and increase in the utilization of borrowing lines.
Net profit tumbled by 25 percent to clock in at Rs.3696.06 million in 2019 with EPS of Rs.4.07 versus EPS of Rs.6.21 recorded in the previous year. NP margin also dwindled from 13.98 percent in 2018 to 9.77 percent in 2019.
2020 was the year when the company recorded impressive margins, never witnessed before. Moreover, despite 6.62 percent dip in net sales, bottomline grew by over 55 percent year-on-year. Suppressed topline was a result of muted offtake of both PVC and Caustic which dipped year-on-year by 15 percent and 27 percent respectively to clock in at 163 KT and 61 KT.
The impact of low offtake was partially offset by higher PVC prices and cost control measures implemented during the year. EPCL posted an impressive GP margin of 31 percent in 2020 with gross profit multiplying by 35 percent. Distribution expense declined by 24.83 percent in 2020 due to considerably lower sales promotion expense, lesser salaries and curtailed travelling & conveyance charges incurred during the year.
Administrative expense dropped by 3.52 percent in 2020 due to considerable decline in communication, travelling, conveyance and training charges incurred during the year on account of COVID-19. This was partially offset by higher payroll expense incurred during the year as number of employees increased to 563 in 2020. Other expense slumped by 30.77 percent in 2020 due to massive decline in exchange loss.
Other expense was completely offset by 26.80 percent higher other income recorded in 2020. This was due to higher income from financial assets at FVTPL and amortized cost. EPCL’s operating profit improved by 52.56 percent in 2020 with OP margin attaining a new high level of 29.51 percent.
Finance cost escalated by 22.15 percent in 2020 due to an increase in long-term loan on account of utilization of ILTFF to finance its PVC expansion project. EPCL recorded 55 percent growth in its bottomline which stood at Rs.5730.24 million in 2020. This translated into EPS of Rs.6.28 and NP margin of 16.22 percent.
2021 proved to be the most fortunate year for EPCL. Increase in PVC and Caustic volumes coupled with higher PVC prices on account of global supply constraints resulted in 98 percent year-on-year growth in EPCL’s topline which clocked in at Rs.70,021.68 million.
PVC volume increased by 28 percent to clock in at 208 KT in 2021. Similarly, caustic soda and caustic flakes also recorded year-on-year growth of 12 percent and 250 percent respectively to clock in at 68 KT and 7 KT. EPCL recorded 119.52 percent improvement in its gross profit with GP margin attaining its highest level of 34.33 percent in 2021.
Higher sales volume resulted in 37.92 percent escalation in EPCL’s distribution expense mainly because of increased dealer commission, higher salaries of sales force and elevated travelling, conveyance and training charges incurred during the year.
EPCL hired more employees due to completion of its expansionary projects during the year. Workforce stood at 598 employees in 2021. This resulted in higher payroll expense which pushed up the administrative expense by 24.95 percent in 2021. Other expense mounted by 177.21 percent in 2021 due to higher exchange loss and increased provisioning done for WWF and WPPF.
Other income ticked up by 12.48 percent in 2021 due to higher income from investment at fair value. EPCL recorded 109.98 percent higher operating profit in 2021 with OP margin jumping up to 31.26 percent.
Low discount rate coupled with repayment of loans during the year enabled EPCL to lessen its financial cost by 13.13 percent in 2021. The bottomline of the company grew by 162.83 percent year-on-year in 2021 to clock in at Rs. 15.060.51 million. This translated into EPS of Rs.16.32 and NP margin of 21.51 percent.
As against 2021 where the company enjoyed a robust topline and bottomline, 2022 was a rather depressed year for EPCL. During 2022, the company was able to achieve a topline growth of 17.19 percent year-on-year. This was despite low PVC prices due to global economic uncertainty coupled with high volatility in the international energy prices.
Topline growth was the result of Pak Rupee depreciation which magnified the value of its export sales. Moreover, PVC sales volume also increased by 11 percent to clock in at 231 KT in 2022. High cost of sales owing to depreciation of Pak Rupee and high fuel and energy (RLNG) charges resulted in 2.73 percent year-on-year drop in the gross profit with GP margin falling down to 28.49 percent.
Distribution expense escalated by 44.62 percent in 2022 mainly due to higher dealer commission and sales promotion expense incurred during the year. Administrative expense mounted by 47 percent in 2022 due to inflationary pressure and also because of induction of new employees which took the tally to 601 employees in 2022. Other expense multiplied by 46.12 percent in 2022 due to massive exchange loss incurred during the year on account of Pak Rupee depreciation.
Other income grew by 11.62 percent in 2022 due to higher income on bank deposits and income from financial assets at amortized cost. Operating profit slid by 9.61 percent in 2022 with OP margin shrinking to 24.11 percent. Finance cost enlarged by 62.43 percent in 2022 predominantly because of higher discount rate.
Net profit slid by 22.39 percent to clock in at Rs.11,689.12 million in 2022 with EPS of Rs.12.39 and NP margin of 14.24 percent.
In 2023, EPCL’s topline dipped by 1 percent to clock in at Rs.81,224.45 million. This was due to lower prices and sales volume of both PVC and caustic soda on account of turbulence in the local and global macroeconomic backdrop.
Despite thinner topline, cost of sales registered 3.4 percent spike in 2023 on the back of Pak Rupee depreciation and elevated gas prices. This translated into 12.11 percent dip in EPCL’s gross profit in 2023 with GP margin dipping to 25.30 percent.
Distribution expense ticked up by 7.19 percent in 2023 as higher salaries and dealer commission was offset by lower sales promotion expense as well as lesser travelling & conveyance charges incurred during the year. Administrative expense mounted by 60.85 percent in 2023 due to higher payroll expense as well as increased cost of purchased services.
Lower profit related provisioning and exchange loss culminated into 50.78 percent drop in other expense in 2023 which was almost offset by 15.21 percent higher other income recorded during the year.
Higher other income was the result of insurance claim, higher scrap sales, higher profit on bank deposits and income on loan granted to subsidiary companies. Operating profit slid by 9 percent in 2023 with OP margin descending to 22.52 percent.
Finance cost magnified by 35.75 percent in 2023 due to higher discount rate and increased utilization of working capital lines. Net profit tapered off by 23.18 percent to clock in at Rs.9230.66 million in 2023. This translated into EPS of Rs.9.45 and NP margin of 11.36 percent.
In 2024, EPCL’s topline slid by 6.83 percent year-on-year. There was a slight improvement in PVC demand due to gradual revival in economic activity; however, there was a decline in international PVC prices which put downward pressure on the topline.
Overall PVC volumes remained low when compared to the previous year. Caustic soda volumes slightly improved in 2024. Despite topline compression, cost of sales mounted by 13.90 percent in 2024 on the back of higher gas and raw material prices. This resulted in 68 percent contraction in gross profit with GP margin falling down to its lowest level of 8.68 percent in 2024.
Distribution expense inched up by 5.46 percent in 2024 due to higher dealer commission, increased cost of purchased services and elevated training, travelling and conveyance charges incurred during the year.
Administrative expense soared by 27 percent in 2024 due to exorbitant rise in the cost of purchased services. This was partially offset by lower payroll expense as the company streamlined its workforce from 584 employees in 2023 to 540 employees in 2024.
Other expense slumped by 87.95 percent in 2024 as no exchange loss was incurred during the year owing to the stability in the value of local currency. Other income also dwindled by 11.43 percent in 2024 due to considerable decline in the income from investments due to lower cash availability and a drop in discount rate.
EPCL registered 71.82 percent year-on-year fall in its operating profit in 2024 with OP margin descending to 6.81 percent. Finance cost escalated by 79.23 percent due to increased short-term and long-term borrowings which was partially offset by lower discount rate. EPCL’s net profit eroded by 93.39 percent to clock in at Rs.610.34 million in 2024 with EPS of Rs.0.45 and NP margin of 0.81 percent.
In 2025, EPCL’s topline ticked up by 2.28 percent to clock in at Rs.77,405.67 million. While local demand improved during the year owing to recovery in macroeconomic situation and flood related rehabilitation drives undergoing during the year, domestic PVC prices were significantly reduced in line with declining international prices.
Export sales to Afghanistan and the Middle East also shrank during the year due to geopolitical crisis. The demand for caustic soda remained stable during the year. The company also commissioned Rs.11.7 billion Hydrogen peroxide plant during the year.
Higher energy cost due to escalating gas prices and downward revision in PVC prices resulted in 19.72 percent deterioration in gross profit in 2025. GP margin recorded its lowest value of 6.81 percent in 2025.
Distribution expense surged by 5.85 percent in 2025 due to higher dealer commission incurred during the year. Conversely, administrative expense shrank by 19.53 percent in 2025 due to lesser purchased services. 206 percent spike in other expense in 2025 was the consequence of exchange loss emanating from the translation of FOREX denominated lease liabilities.
Other income diminished by 38.24 percent in 2025, however, was huge enough to absorb the other expense. The decline in other income was the consequence of lower income on bank deposits, investments and loans granted to subsidiary companies on account of monetary easing.
EPCL’s operating profit diluted by 37.56 percent in 2025 with OP margin falling down to 4.16 percent. Finance cost tapered off by 24.16 percent in 2025 due to monetary easing. This was despite massive spike in long-term borrowings during the year as the company invested in Hydrogen peroxide plant.
Excessive borrowings culminated into gearing ratio of 68 percent in 2025 versus 52 percent in 2024. Regardless of decline, EPCL’s finance cost was huge enough to turn its operating profit into net loss of Rs.3043.128 million in 2025. This translated into loss per share of Rs.3.35 in 2025.
Recent Performance (9MCY26)
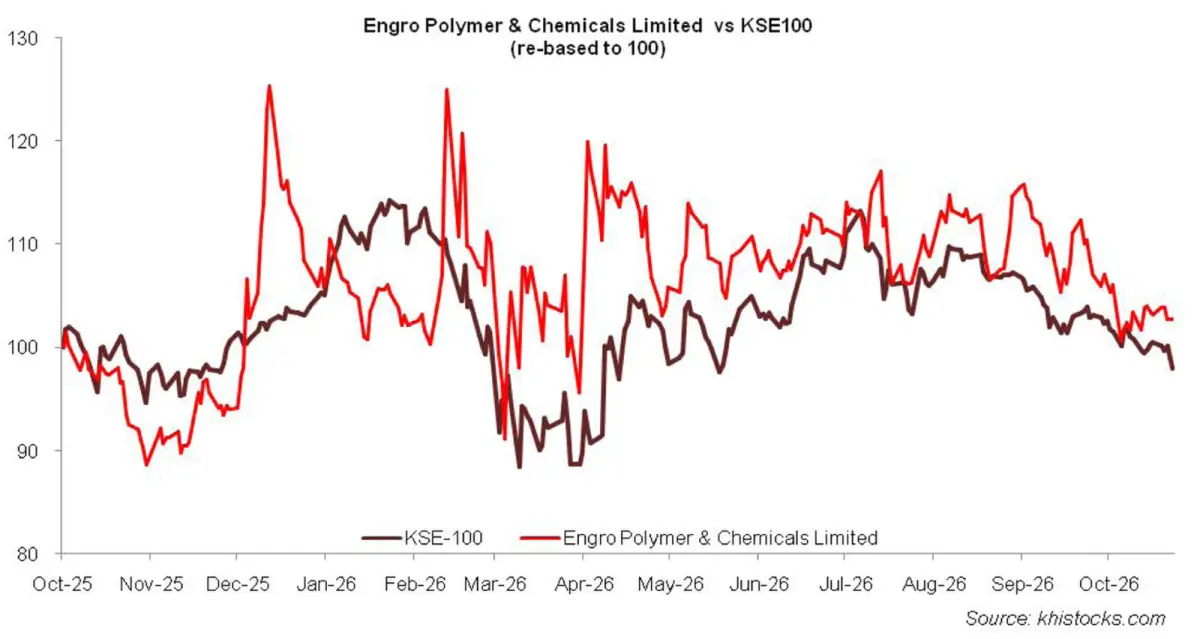
During 9MFY26, EPCL’s topline ticked up by 12 percent to clock in at Rs.63,943.89 million. This came on the back of higher sales volume, increased PVC prices and greater revenue from hydrogen peroxide. Reduction in applicable gas levy due to revision of levy formula greatly supported the gross profit which strengthened by 30.19 percent in 9MCY26 with GP margin clocking in at 7.92 percent versus 6.82 percent in 9MCY25.
In March 2026, Government of Pakistan revised the gas levy formula which resulted in levy reduction from Rs. 1,406/MMBtu in Jan to PKR 341/MMBtu in May. However, levy has increased after that. The company also commissioned 2MW solar power project in August 2026. Distribution expense surged by 6.42 percent in 9MCY26 due to steady sales volume and heightened freight charges.
Conversely, administrative expense ticked down by 1.48 percent in 9MCY26 likely due to lesser purchased services. 65 percent thinner other expense recorded during the period appears to be the result of lesser exchange loss due to high-base effect as the company had translated its FOREX denominated lease liabilities in the previous year.
Other income enhanced by 377.93 percent in 9MCY26 due to higher income from short-term investments. It is to be noted that the company purchased short-term investments (TDRs, T-Bills and Mutual Funds) worth Rs.67,176.357 million during the period under review.
Moreover, the company also recognized income worth Rs. 69,939.201 million from the sale/maturity of its short-term investments during the period. Re-measurement gain on SIDC also buttressed other income in 9MCY26.
Other income conveniently offset other expense in 9MCY26, resulting in net other income of Rs.2456.04 million in 9MCY26 versus net other expense of Rs.183.91 million recorded in 9MCY25. Operating profit heightened by 210.33 in 9MCY26 with OP margin clocking in at 8.78 percent versus 3.17 percent registered in 9MCY25.
Finance cost surged by 27.58 percent in 9MCY26 due to increase in long- term borrowings. EPCL posted net profit of Rs.399.055 million with EPS of Rs.0.44 in 9MCY26. This was against the net loss of Rs.2833.478 million and loss per share of Rs.3.12 recorded in 9MCY25.
Future Outlook
The company’s margins are expected to shrink due to stable PVC prices, range-bound ethylene prices and high energy cost. The company highly relies on imported raw materials (ethylene and ethylene dichloride) particularly from Middle, US and Europe. With the ongoing tensions in the Middle Eastern region and obstruction of major trade routes, the company might face supply chain impediments.
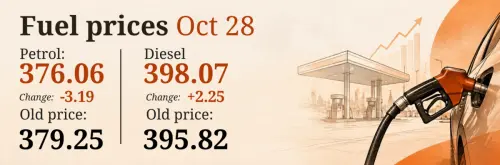
Moreover, spike in the international petroleum prices will take its toll on the energy cost and Pak Rupee stability, creating a double whammy for EPCL.
On the positive front, Hydrogen peroxide plant and high-temperature direct chlorination plant could improve operational efficiency and diversify the revenue sources as capacity utilization increases.
Moreover, Lotte Chemical Pakistan’s proposed acquisition of 56.19 percent stake of EPCL could result in operational synergies and cost efficiency.
Copyright Business Recorder, 2026



Comments