


Suspension, blacklisting of exporters undermining towel exports, says TMA
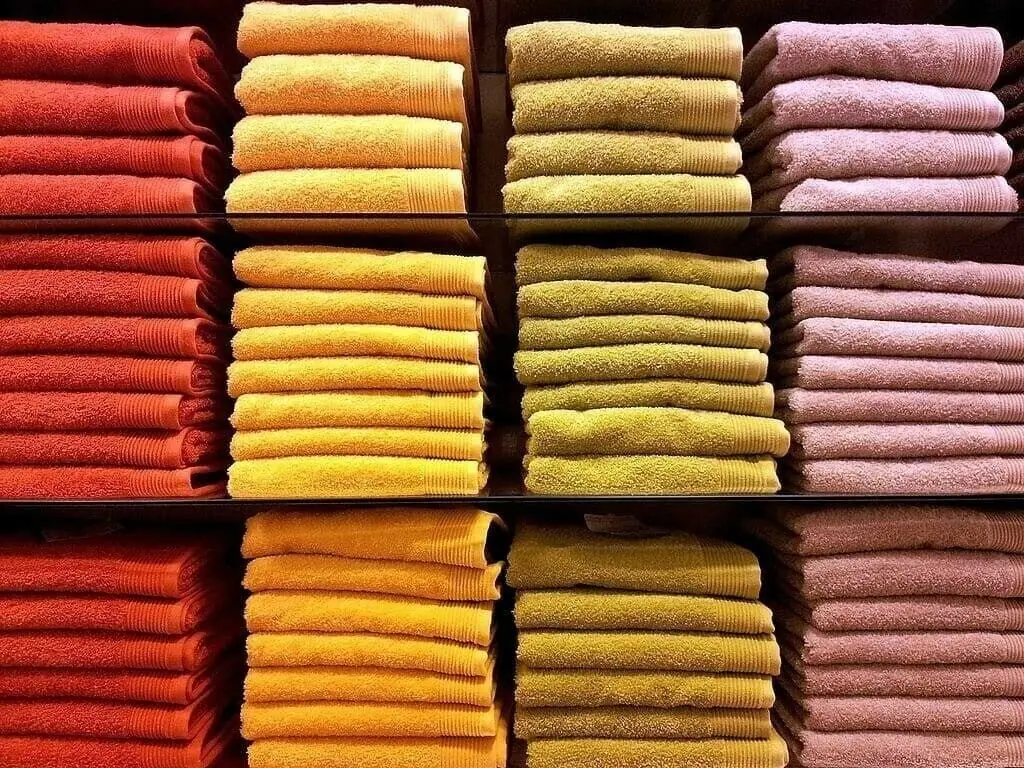
KARACHI: The Towel Manufacturers Association of Pakistan (TMA) has expressed serious concern over the Federal Board of Revenue’s (FBR) issuance of notices and initiation of proceedings for the suspension and blacklisting of exporters under Section 21(2) of the Sales Tax Act, 1990.
The Association has warned that such actions, particularly where exporters are not provided proper prior notice or a fair opportunity to respond, are disrupting business operations, jeopardizing export orders, and undermining Pakistan’s towel exports.
Established in the 1970s, the Towel Manufacturers Association of Pakistan (TMA) is one of Pakistan’s oldest export-oriented trade associations and the sole representative body of the country’s towel industry.
Representing more than 200 member companies nationwide, TMA serves the 100 percent export-oriented towel and home textile sector, which supplies international markets with quality products, particularly towels.
The sector contributes approximately USD2.2 billion annually in foreign exchange earnings, while supporting industrial activity, employment generation, and Pakistan’s economic growth.
TMA has warned that the continued suspension and blacklisting of exporters is placing the towel industry under severe pressure. Suspension of sales tax registrations can disrupt the procurement of raw materials, interrupt production, delay shipments, and prevent exporters from fulfilling their contractual obligations to international buyers.
These disruptions threaten Pakistan’s export performance, risk the loss of valuable foreign exchange, and weaken the country’s competitiveness in international markets. At a time when Pakistan urgently needs to increase exports, such measures are undermining the growth and stability of a sector that makes a significant contribution to the national economy.
Rehan Mehtab Chawla, Chairman of TMA, stated that exporters who purchased raw materials two to three years ago from suppliers registered as active taxpayers, made payments through crossed cheques, and duly paid sales tax are now facing adverse consequences because their suppliers have subsequently been blacklisted. These exporters fulfilled the applicable legal requirements, manufactured and exported their products, and claimed input tax refunds against documented transactions.
He emphasised that exporters cannot reasonably be held responsible for the subsequent status or alleged non-compliance of suppliers who were registered and recognized as active taxpayers by the FBR at the time of the transactions.
The responsibility for monitoring registered taxpayers and taking timely action against non-compliant entities rests with the relevant tax authorities, he said. Exporters cannot guarantee that a supplier, duly registered and compliant at the time of a transaction, will never be blacklisted in the future. Retrospective action against bona fide exporters, without establishing their involvement in any wrongdoing, creates serious uncertainty and undermines confidence in Pakistan’s tax administration.
Referring to the legal position, Chawla cited the order of the Honourable Supreme Court of Pakistan dated May 18, 2018, in Civil Petition No. 682 of 2017, concerning the admissibility of input tax claims where transactions involve registered persons and the supplier’s suspension or blacklisting status.
He stressed that the relevant facts, transaction dates, and applicable legal requirements must be examined before any adverse action is taken against an exporter.
He further questioned the fairness of suspending exporters’ sales tax registrations years after genuine commercial transactions have been completed, particularly where documentary evidence, including invoices, banking records, and proof of payments, is available. Such measures expose compliant businesses to financial losses and operational disruption for circumstances beyond their reasonable control.
Highlighting the economic consequences, he explained that suspension of a company’s sales tax registration can severely impede its ability to procure raw materials, conduct business, and dispatch export shipments. Production delays and missed delivery deadlines can jeopardize international contracts, damage buyers’ confidence, and divert orders to competing countries. Ultimately, these disruptions threaten the performance of Pakistan’s towel export sector and the foreign exchange earnings it generates, he said.
He observed that the government’s repeated calls for increasing exports must be supported by policies that facilitate production, trade, and investment. Persistent sales tax refund delays, high energy costs, and regulatory uncertainty are already placing exporters under considerable financial pressure. Suspension and blacklisting proceedings under Section 21 (2) of the Sales Tax Act, 1990, when pursued without adequate consideration of the facts and the exporter’s right to a fair hearing, further aggravate these challenges.
Chawla expressed serious concern over the continued accumulation of deferred sales tax refunds, which is creating a severe financial crunch for exporters. Despite fulfilling their tax obligations and export commitments, businesses are being deprived of timely access to their legitimate refund amounts, resulting in an increasingly acute liquidity crisis.
Exporters are consequently facing difficulties in financing working capital, purchasing raw materials, meeting operational expenses, and maintaining uninterrupted production, he said. The prolonged withholding of refunds locks up essential working capital, increases reliance on costly borrowing, and further weakens exporters’ international competitiveness.
He urged the FBR to expedite the clearance and payment of all outstanding deferred refunds to provide immediate financial relief and prevent further damage to Pakistan’s towel exports.
TMA reiterated its demand for the restoration of the “no payment, no refund” sales tax mechanism for export-oriented sectors and urged the government to restore SRO 1125 (I)/ 2011 in its original form, subject to the applicable legal and policy framework. Such a mechanism would help prevent the accumulation of sales tax costs on export inputs, improve exporters’ liquidity, and enable businesses to concentrate on production, timely shipments, and international market development.
The Association has appealed to the Prime Minister, the Federal Minister for Commerce, the country’s economic managers, and the Chairman FBR to intervene urgently.
TMA has called for an immediate review of suspension and blacklisting proceedings, the withdrawal of unjustified actions against bona fide exporters, and the provision of a fair opportunity for exporters to establish the genuineness of their transactions. Where suppliers are found to have violated tax laws, the authorities should pursue recovery and appropriate legal action against the responsible parties in accordance with the law, without automatically penalizing compliant purchasers. The Association has also urged the immediate settlement of outstanding deferred sales tax refunds to restore liquidity and support uninterrupted export operations.
Chawla concluded that Pakistan cannot achieve sustainable export growth by disrupting the operations of bona fide exporters for the subsequent conduct of their registered suppliers or by withholding refunds essential to their business operations.
He urged the government and the FBR to adopt a fair, transparent, and business-friendly approach that protects compliant exporters, prevents unnecessary disruption of towel production and shipments, and safeguards Pakistan’s foreign exchange earnings. Protecting genuine exporters from unjustified suspension and blacklisting, while ensuring the timely payment of outstanding sales tax refunds, is essential to sustaining Pakistan’s towel exports, preserving international market confidence, and achieving the country’s export growth objectives.
Copyright Business Recorder, 2026








Comments