


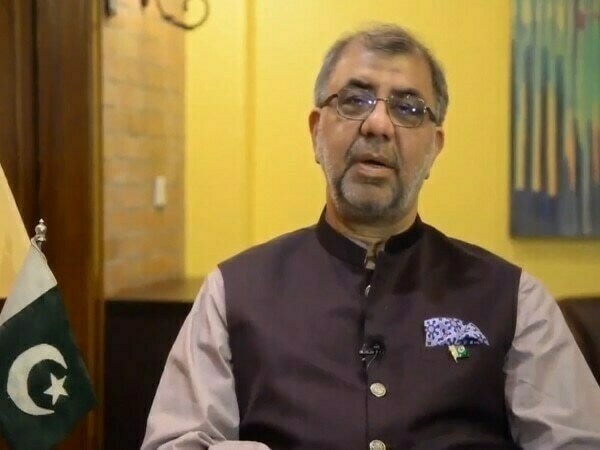

LAHORE: Taxonomist Ashfaq Yousuf Tola has suggested introduction of Minimum Asset Tax (MAT) via Capital Value Tax (CVT) and modernization of the definition of “Resident Individual” for tax purposes to broaden the tax base and ensure equity within the tax system.
To ensure high-net-worth individuals contribute a fair share to national revenue, he has proposed to introduce MAT by expanding the scope of Capital Value Tax CVT. He said the MAT would apply to resident individuals whose domestic assets exceed PKR 100 million and the tax would be charged at 1% of the fair market value of the assets exceeding this threshold.
According to him, MAT would be adjustable against the individual’s income tax liability, serving as a minimum threshold for direct taxation rather than imposing an extra tax burden.
Regarding modernization of the definition of “Resident Individual” for tax purposes, he said the current residency definition under Section 82 of the Income Tax Ordinance. 2001, which classifies a resident as someone spending 183 days or more in Pakistan, is outdated and lacks alignment with more nuanced residency rules in other jurisdictions.
Tola has proposed a revised framework, saying that a more appropriate definition of residency would classify individuals as a “resident” if they stay in Pakistan for 182 days or more during a financial year.
For individuals who stay between 120 and 181 days, he said, their residency status should depend on both citizenship and income.
Specifically, Tola pointed out, a Pakistani citizen (as defined under the Pakistan Citizenship Act, 1951) or a person holding a Pakistan Origin Card (POC) who earns income exceeding a prescribed threshold (excluding foreign-sourced income), and has no tax liability in any other country, should be treated as a Resident but Not Ordinarily Resident (RNOR).
Those who do not meet these criteria should be classified as non-residents, he stressed.
Also, he said, individuals who spend less than 120 days in Pakistan during the financial year should be treated as Non-Residents, regardless of their income or nationality.
Copyright Business Recorder, 2025























Comments
Comments are closed for this article.