


Beco Steel Limited: performance and outlook
Beco Steel Limited navigated a volatile financial landscape from 2020-2026, transitioning to steel production and achieving record sales and profit in 2026, with strategic future plans.
- Company's transformation from textile to integrated steel producer.
- Fluctuating financial performance, including record 2026 sales and profit.
- Strategic future plans: rebar plant, solar power, and market diversification.
- Key factors influencing margins, like commodity prices and FBR litigation.

Beco Steel Limited (PSX: BECO) was formerly known as Ravi Textile Mills and is incorporated in Pakistan as a public limited company. BECO is an integrated steel producer with products ranging from scrap to billet to various end products including specialty steel.
Pattern of Shareholding
As of June 30, 2026, BECO has a total of 1249.625 million shares outstanding which are held by 16,195 shareholders. 47.52 percent of BECO’s shares are held by its directors and sponsors followed by local general public holding 29.43 percent shares. Chaudhry Steel Re-rolling Mills (Private) Limited has a stake of 21.94 percent in the company. The remaining shares are held by other categories of shareholders.
Historical Performance (2020-26)
After 2016, BECO didn’t record any sales for the four successive years. However, it has been posting sales since 2021. Despite no sales, BECO posted net profit in 2020 on the back of its other income.
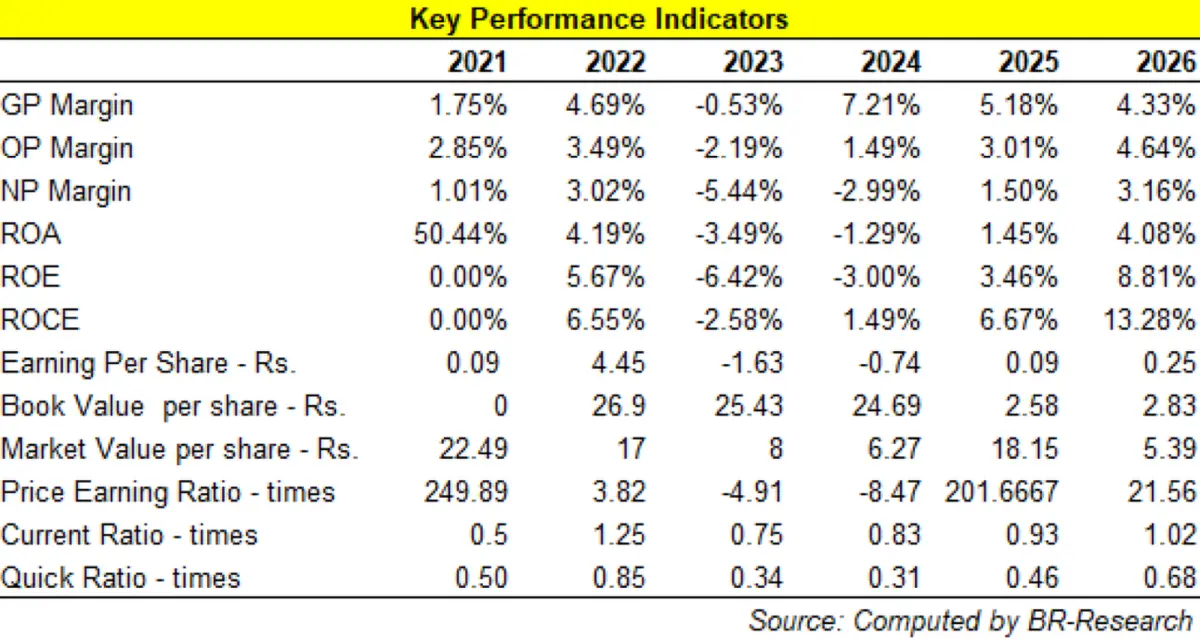
The company’s net profit drastically fell in 2021 only to post a staggering growth in 2022. In 2023 and 2024, BECO posted net losses followed by net profit in 2025 and 2026. The company posted the highest ever net sales and net profit in 2026. BECO’s margins greatly improved in 2021 and 2022.
In 2023, the company posted negative margins. In 2024, gross and operating margins were in the positive zone; however net margin stayed in the negative zone. In 2025 and 2026, gross margin deteriorated, however, operating and net margins strengthened. The detailed performance review of the period under consideration is given below.
In March, 2020, 51 percent of the company’s shares along with its management control was acquired by Ch. Muhammad Shafique and Muhammad Ahmed Raza who were also the major shareholders of Chaudhary Steel Re-rolling Mills Limited and Beco Steel Re-rolling (Private) Limited respectively.
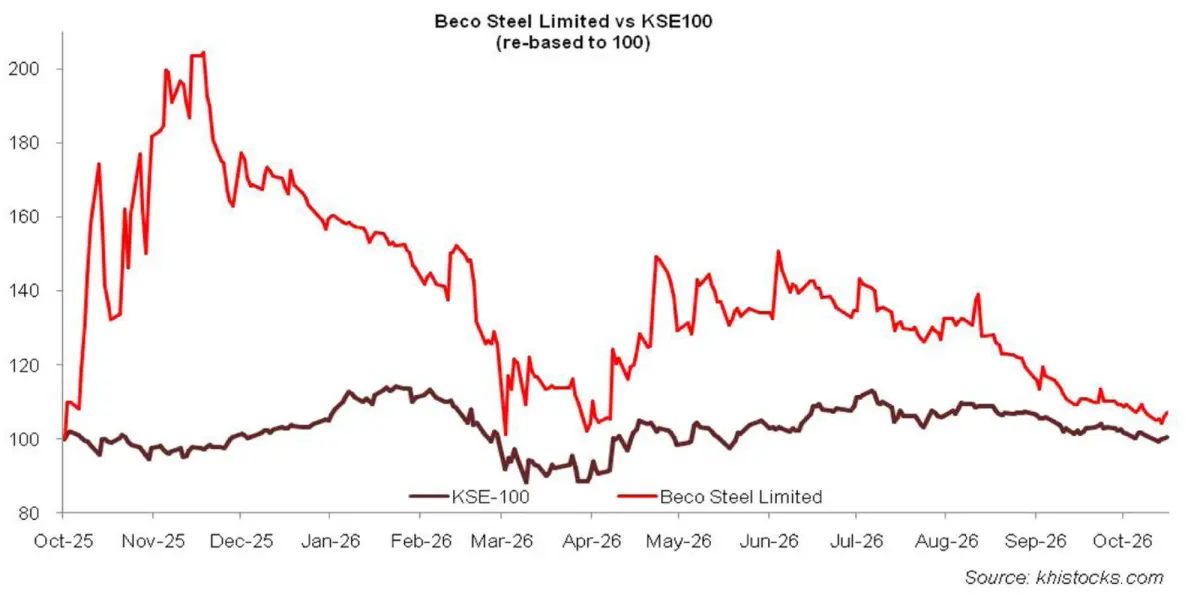
The new shareholders having rich experience in the steel sector changed the company’s line of business from textile to steel. However, the company couldn’t record any sales in 2020. Administrative expense dropped by another 36.71 percent year-on-year in 2020 as the number of employees was reduced from 17 in 2019 to just 4 in 2020.
Other expense ticked down by 65 percent in 2020 due to reduction in provisioning done for WPPF and no loss incurred on the sale of store, spares and loose tools in 2020. While the company made significant profit on saving accounts and also wrote back loan from the ex-director.
However, high base provided by the gain on the disposal of fixed assets in 2019 resulted in a drop of 63.19 percent in other income in 2020. Operating profit dropped by 66.45 percent year-on-year in 2020 to clock in at Rs.31.658 million. Finance cost grew by 41 percent year-on-year to clock in at Rs.1.04 million in 2020 on account of interest charges on WPPF. Net profit dropped by 70.38 percent year-on-year in 2020 to clock in at Rs.30.197 million with EPS of Rs.1.21.
The company started its steel business in July 2021 on toll manufacturing basis and posted net sales of Rs.230.77 million. Cost of sales clocked in at Rs. 226.74 million which mainly comprised of raw materials consumed during the year. Gross profit was recorded at Rs. 4.03 million in 2021, resulting in GP margin of 1.75 percent. Administrative expense mounted by 99.42 percent mainly on the back of fee & subscription charges incurred during the year.
The company also hired two new resources during the year resulting in a workforce of 6 employees in 2021. BECO also incurred distribution expense of Rs.1.84 million in 2021. During the year, the company considerably reduced its profit related provisioning, however allowance for ECL booked during the year resulted in 10.50 percent uptick in other expense in 2021.
Other income shrank by 46.51 percent in 2021 due to high-base effect as the company wrote back directors’ loan worth Rs.25.20 million in the previous year. The write-back of directors’ loan was the main reason which had enabled BECO to record a positive bottomline in 2020. In the previous year, the company also recorded operating profit of Rs.31.658 million which shrank by 79.22 percent in 2021.
OP margin clocked in at 2.85 percent in 2021. Finance cost plunged by 71.38 percent in 2021 due to lower interest charges incurred on WPPF. Net profit deteriorated by 92.30 percent to clock in at Rs.2.32 million in 2021. This translated into EPS of Rs.0.09 and NP margin of 1.01 percent in 2021.
In 2022, BECO’s topline multiplied by 2634.46 percent to clock in at Rs. 6310.32 million. During the year, the company achieved major milestones i.e. the addition of plant and machinery and start of commercial operations on its own manufacturing plant during the last two months of 2022. Before that, the company operated on toll manufacturing facility. For a massive capital investment, the company issued 99.96 million ordinary shares at a premium of Rs.20 per share for a total value of Rs.2,998.975 million in 2022.
High cost of sales due to commodity super cycle in the international market coupled with Pak Rupee depreciation pushed the cost of sales up by 2552.51 percent in 2022. Yet the company was able to record 7247.39 percent higher gross profit in 2022 with GP margin jumping up to 4.70 percent. Administrative expense grew by 187.27 percent in 2022 due to staggering growth in payroll expense as the number of employees grew from 6 in 2021 to 160 in 2022. Other factors that pushed up the administrative expense were higher rent, rates and taxes as well as higher legal and professional charges incurred during the year.
Distribution expense grew by 755.31 percent year-on-year in 2022 due to carriage and transport charges. Other expense also grew by 516.50 percent in 2022 due to higher provisioning done for WWF and WPPF. Conversely, other income shrank by around 99.57 percent in 2022 due to lower profit on saving account.
Operating profit grew by 3246.16 percent in 2022 with OP margin climbing up to 3.50 percent. Finance cost slid by 50.90 percent year-on-year in 2022 due to lower interest incurred on WPPF. Net profit grew by 8097.54 percent in 2022 to clock in at Rs.190.52 million. This translated into EPS of Rs.4.45 and NP margin of 3 percent in 2022.
In 2023, BECO’s net sales dwindled by 40.54 percent to clock in at Rs.3752.11 million due to lower sales volume on the back of poor economic and political condition of the country which greatly reduced the construction and infrastructure development activities in the country.
High international steel and petroleum prices due to commodity super cycle in the global market was further exacerbated by Pak Rupee depreciation and high indigenous inflation. As a consequence, BECO recorded gross loss of Rs.20.03 million in 2023. While the company streamlined its workforce from 160 employees in 2022 to 34 employees in 2023 resulting in a downtick recorded in payroll expense, whopping spike in travel & conveyance charges drove administrative expense by 17.66 percent in 2023.
Distribution expense tumbled by 91.77 percent in 2023 as no carriage & transport charges were incurred coupled with a decline in the salaries of sales force. No provisioning done for WWF and WPPF resulted in 42.66 percent lower other expense in 2023. Other income grew by 83 percent in 2023 due to increased profit on saving accounts, however, wasn’t significant enough to produce any positive impact on the company’s financial performance.
BECO posted operating loss of Rs.82.12 million in 2023. Finance cost escalated by 2146.46 percent due to massive interest charges incurred on WPPF on account of monetary tightening. Net loss clocked in at Rs.204.12 million in 2023. This culminated into loss per share of Rs.1.63 in 2023.
In 2024, BECO’s net sales further plummeted by 17.43 percent to clock in at Rs.3098.02 million. Inferior politico-economic conditions continued to take its toll on the sales of the company. However, decline in the international commodity prices and stability of Pak Rupee towards the end of the year enabled the company to record gross profit of Rs.223.36 million in 2024. This translated into GP margin of 7.21 percent in 2024.
Administrative expense mounted by 435.43 percent in 2024. The main reason behind this massive rise in administrative expense was due to provision of Rs.224.174 million booked against the litigation charge raised by FBR. BECO also expanded its workforce to 46 employees in 2024, resulting in higher payroll expense. Distribution expense surged by 155.51 percent in 2024 due to depreciation recorded on right-of-use assets.
Decline in miscellaneous charges resulted in 23 percent lower other expense recorded in 2024. Liabilities worth Rs.110.079 million written back during the year resulted in 64507.50 percent higher other income in 2024.
BECO posted an operating profit of Rs.49.22 million with OP margin of 1.59 percent in 2024. Finance cost surged by 111.96 percent in 2024 due to greater bank charges & commission, higher interest charges on WWF and WPPF and greater lease liabilities. BECO recorded 55.50 percent thinner net loss to the tune of Rs.90.826 million in 2024. This translated into loss per share of Rs.0.73 in 2024.
In 2025, BECO’s topline posted a staggering year-on-year growth of 140.52 percent to clock in at Rs.7451.49 million. In the previous years, the company navigated through a testing macroeconomic backdrop. However, improvement in the same enabled the company to realize its potential and strike important deals both within and outside the country.
Cost of sales surged by 145.78 percent in 2025 due to elevated energy charges, repair & maintenance charges and cost of other raw materials. Gross profit strengthened by 72.93 percent in 2025, however, GP margin dipped to 5.18 percent. Administrative expense dropped by 56.97 percent in 2025 due to high-base effect as the company did provisioning against litigation in the previous year.
Absence of litigation charges in 2025 overshadowed the impact of higher payroll expense, fee & subscription charges as well as repair & maintenance charges incurred during the year.
Distribution expense mounted by 469.69 percent in 2025 due to excessive carriage, loading and advertisement expense incurred during the year. Higher profit related provisioning and exchange loss were the causes of 284.39 percent hike in other expense in 2025.
Conversely, other income slid by 99.66 percent during 2025 as no liabilities were written back and no exchange gain was recorded in 2025. Operating profit strengthened by 355.24 percent in 2025 with OP margin climbing up to 3 percent. Finance cost dropped by 16.45 percent in 2025 due to monetary easing, lesser bank charges and interest free short-term loan worth Rs.4.9 million obtained from the sponsors.
BECO recorded net profit of Rs.111.48 million in 2025. This translated into EPS of Rs.0.09 and NP margin of 1.50 percent in 2025.
Recent Performance (2026)
In 2026, BECO’s net sales registered a decent 32.33 percent growth to clock in at Rs.9860.50 million. This was due to improvement in both local and export sales during the year. Hong Kong was the major export market of BECO.
Cost of sales escalated by 33.52 percent in 2026 due to higher fuel and power charges and scrap cost particularly after the onset of tensions in the Middle East. Gross profit ticked up by 10.54 percent in 2026, however, GP margin dropped to 4.33 percent.
Higher payroll expense pushed up administrative expense by 17.21 percent in 2026. This was despite the fact that the workforce was streamlined from 48 employees in 2025 to 46 employees in 2026. Distribution expense also multiplied by 24.54 percent in 2026 due to higher loading charges, advertisement expense and depreciation recorded on right-of-use assets. Greater provisioning done for WWF and WPPF pushed up other expense by 33.41 percent in 2026.
However, it was conveniently offset by other income of Rs.226.30 million recorded in 2026, up 58394.33 percent year-on-year. This was due to reversal of provision against litigation booked earlier as the tax demand of Rs.224.174 million raised by the Federal Board of Revenue was decided in favor of the company. This greatly supported the company’s operational performance.
Operating profit strengthened by 103.97 percent in 2026 with OP margin attaining its optimum level of 4.64 percent.
Finance cost mounted by 156 percent in 2026. Besides higher interest cost on WWF, WPPF and lease liabilities, a notional interest of Rs.5.005 million charged to finance cost under godown lease agreement played a major role in inflating finance cost in 2026. Net profit improved by 179.39 percent to clock in at Rs.311.47 million in 2026. This translated into EPS of Rs.0.25 and NP margin of 3.16 percent in 2026.
2026 was a phenomenal year for BECO as its shareholders’ equity increased by 9.7% to Rs 3,537.2 million, entirely on account of profit for the year. The accumulated loss of Rs 305.3 million at 30 June 2025 turned into accumulated profit of Rs 6.2 million. Moreover, net current liabilities of Rs 284.2 million became net current assets of Rs 79.4 million. Current ratio also improved to 1.02 in 2026 from 0.93 in the previous year.
Future Outlook
Significant increase in PSDP allocation will boost the reconstruction and rehabilitation activities in the areas affected by the Monsoon floods. BECO is also eyeing international markets to diversify its sales mix.
The planned rebar plant with an annual capacity of 72000 tons is expected to broaden the product portfolio and sales mix while the 5 MW solar power project will help control energy cost once operational. Copper exports also offer great diversification and growth potential to the company.
On the flipside, higher scrap and energy cost can take its toll on the margins and profitability of the company.


Comments