


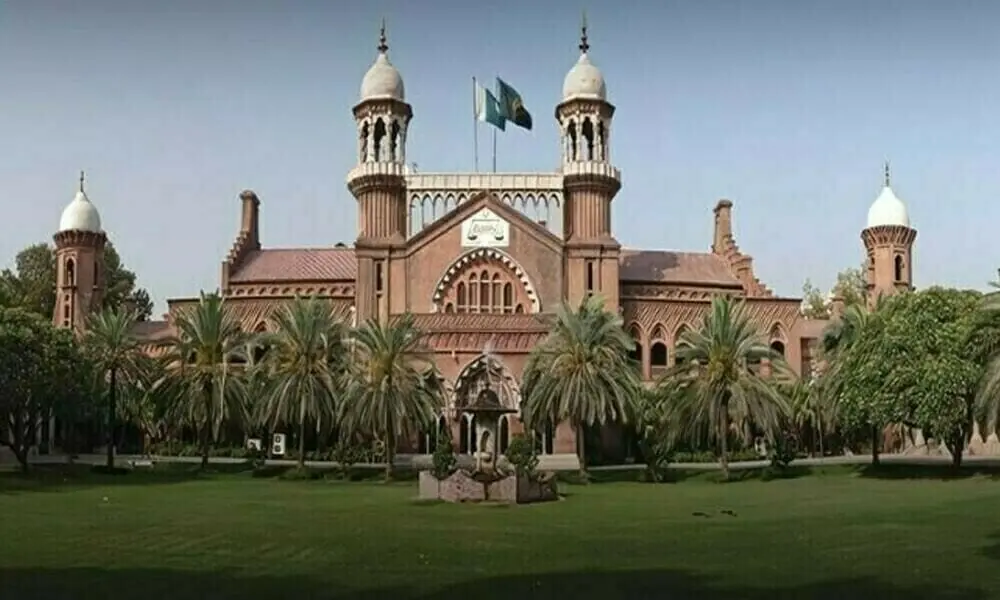
LAHORE: The Lahore High Court has ruled that the demand for property tax on buildings used by the Lahore University of Management Sciences (LUMS) for educational purposes cannot be sustained for the period preceding the 2003 amendment to the Cantonment Act.
The court held that recovery proceedings based on the impugned demand could not be pursued and declared the challenged orders of the Cantonment Board, along with any consequential demand raised on their basis, to be without lawful authority and of no legal effect.
The court passed the order on a petition filed by LUMS challenging the Cantonment Board’s refusal to grant exemption from property tax on buildings used for educational purposes.
The court observed that the impugned orders and determinations related to the pre-amendment legal regime. It noted that while the subsequent amendment was relevant to identifying the change in law and the scope of the court’s determination, liability for earlier periods had to be decided under the provisions in force at the relevant time.
Regarding the post-amendment period, the court held that amended Section 99(2)(b) of the Cantonment Act could not, by itself, be construed as imposing property tax liability on LUMS. Any determination for a subsequent assessment period, it said, must be made through a reasoned order based on an individualised assessment and relevant evidence.
The court observed that merely charging tuition fees was insufficient to establish that income was derived from the buildings in question. The Cantonment Board was required to examine the actual use of each building, the nature and source of receipts attributed to it, arrangements for public access, and the institution’s governing instruments and accounts. The court noted that the Board had failed to undertake such an assessment and had relied on the charging of fees as the basis for denying the exemption.
It further observed that the Cantonment Board had not been vested with unbridled discretion in deciding exemption claims. Instead, its decision was governed by two conditions: that the property be open to the public and that no income be derived from it.
In the instant case, the court concluded, neither had any evidence been considered while dismissing LUMS’s appeal and revision nor had any material been produced to suggest that the fees collected by the institution were channelled to its promoters.
Copyright Business Recorder, 2026



Comments