


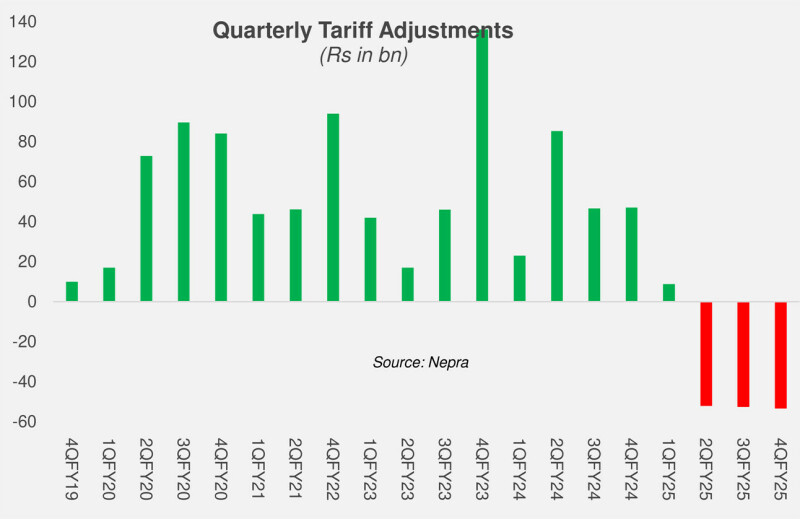
As widely anticipated, the periodic adjustment under the Quarterly Tariff Adjustment (QTA) mechanism for 4QFY25 has come in at a negative Rs53 billion—marking the sharpest single-quarter negative adjustment on record. This also makes it the third consecutive quarter of negative QTA, each exceeding Rs50 billion.
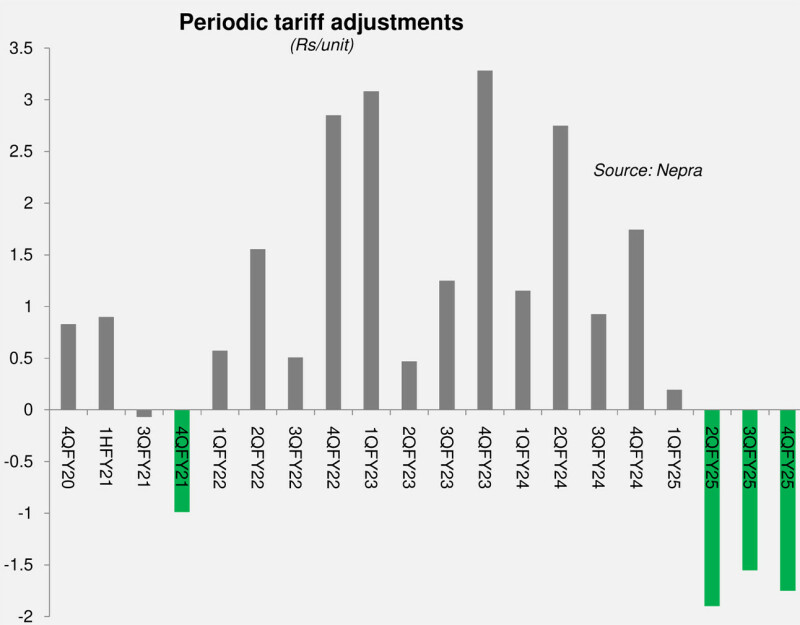
The QTA currently in effect pertains to 3QFY25, with a negative adjustment of Rs1.55/unit, set to expire in July 2025.
The upcoming replacement, applicable from August for three months, is expected to be in a similar range (Rs1.4–1.5/unit). Given muted monthly fuel cost adjustments, the net impact on monthly consumer bills is likely to be marginal.
However, the (highly likely) discontinuation of the Rs1.71/unit subsidy, despite earlier IMF endorsement, will nudge effective tariffs higher going forward.
Notably, the entire Rs53 billion negative adjustment for 4QFY25 stems from a reduction in capacity charges. A significant portion of this saving can be traced to the termination of five power plants and renegotiated terms with several IPPs.
Additionally, the shutdown of the Neelum Jhelum hydropower plant, while reducing capacity payments, is a net negative for the power system, as it subtracts from available generation and shifts the reference mix unfavorably for the next annual rebasing.
All told, QTA-related relief in FY25 has amounted to Rs149 billion, playing a key role in softening end-user tariffs. But that relief may be short-lived.
The outlook for FY26 suggests a return to normalcy. The capacity purchase price (CPP) component—responsible for driving QTA into the negative—is now being built on more realistic assumptions.
The mid-year IPP negotiations, which were outside the scope of FY25’s original CPP estimates and triggered hefty downward adjustments, are now baked into the FY26 numbers. Add to that the Neelum Jhelum shutdown, and CPP for FY26 stands Rs229 billion lower than FY25.
Given this more grounded cost structure, periodic adjustments are expected to remain minimal in FY26. The era of hefty negative QTAs—powered by outdated or inflated capacity charge assumptions—may well be over.





















Comments
Comments are closed for this article.