


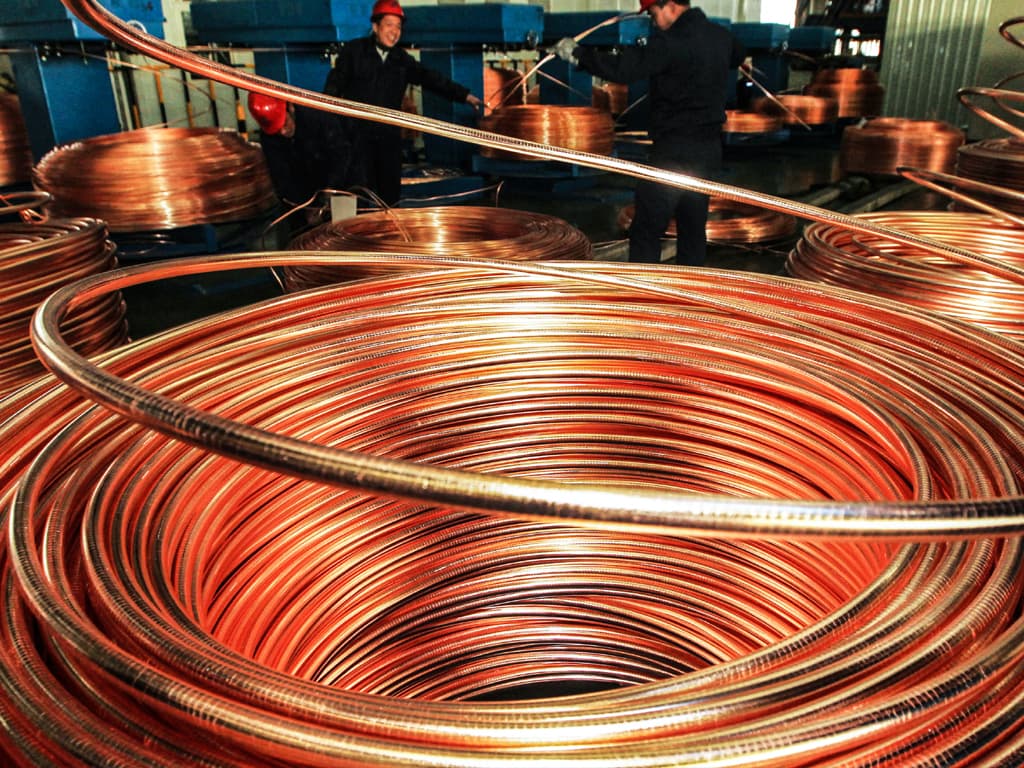

LONDON: Funds continue to reduce their long exposure to the copper market even as the bull clamour for higher prices grows ever louder.
Goldman Sachs last week doubled down on its supercycle shout, forecasting copper would average $15,000 per tonne in 2025 in a headline-grabbing April 13 research note titled “Copper is the new oil”.
Citi is also firmly in the bull camp with a short-term target of $10,500. “We highlight that the ‘super’ part of the supercycle is now” with the market facing the largest supply deficit since 2003-2004, the bank said. (“Metals Weekly”, April 19, 2021)
Copper is bubbling away just below February’s decade high of $9,617 per tonne, London Metal Exchange (LME) three-month metal last trading at $9,400.
Investors appear to remain highly wary, however, and perhaps for good reason. While a supercycle may be coming, copper is right now still heavily reliant on the Chinese cycle.
And the world’s largest buyer is making it very clear that it doesn’t want raw material prices to rise any further.
The fund positioning landscape on the CME’s copper contract has shifted significantly over the last couple of months.
The big net long that built as copper rallied strongly off last year’s early COVID-19 lows has more than halved since February. The stampede to cut outright long positions has abated although collective bull positioning has slipped further to 76,167 contracts, the lowest collective holding since July last year, according to the latest Commitments of Traders Report (COTR). Short positions, meanwhile, have been creeping steadily higher. At a current 37,894 contracts, bear bets are by no means large by historical standards but are still the heaviest they’ve been since June last year.
There has been a similar bull retreat on the London market, albeit less pronounced than that on the CME.
Investment funds have reduced their net LME copper long positioning from a February peak of 47,897 contracts to a current 35,950.
Investment money flowing through the “other financials” category of the LME’s COTR - a mix of insurance and index players - has been reducing its long exposure since August last year, albeit with signs the retreat may be coming to end.























Comments
Comments are closed for this article.