


Automotive half-life-II
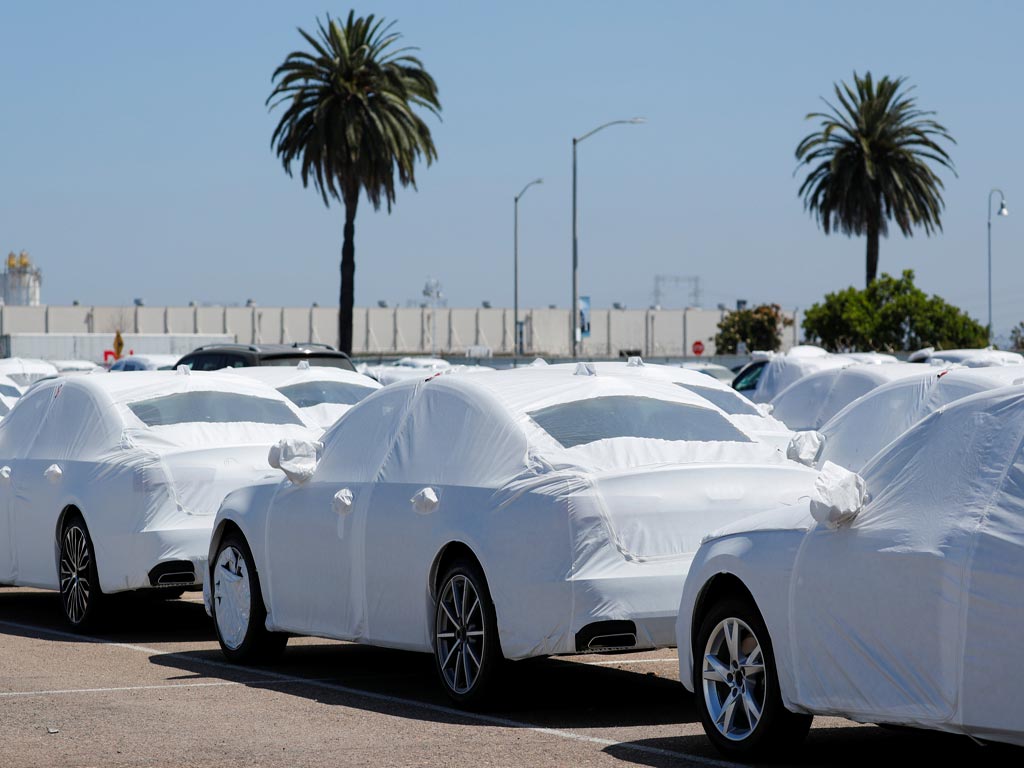
Automakers in India are doling out some of the highest discounts ever recorded to consumers across the country with offers going between 5 and 15 percent on the given price tags for some variants. Consumption demand in the country, similar to Pakistan, has been sluggish, and passenger cars are naturally taking a hit. Much like automakers in Pakistan, Indian car manufacturers have had to steeply raise prices as well over the last year. But unlike, their Pakistani counterparts, Indian automakers are being proactive.
The automotive industry in the neighboring country is going through a pivotal transition. Soon it will be implementing Euro-VI emissions standards across the value chain along with new safety regulations. This will eventually lead to automakers hiking up prices to meet the added cost. It will also boost competitiveness. Realizing this, and confronted with dismal demands trends, the manufacturers are providing discounts to get the piling inventories out into the market.
A transition is also taking place in Pakistan, though not as aspirational as the Indian market. Several new players are entering the market after the auto-development policy 2016-21 proved successful in piquing interest of a number of global automotive giants. This would increase the market size and may even spur competition in an economy which will only just start recovering over the next six months after facing a debilitating twin deficit crisis. Demand has so far been plummeting. Passenger cars and jeeps in 5MFY20 have dropped by 44 percent year on year. Honda City and Civic dropped 70 percent; Toyota Corolla 59 percent.
With shrinking demand, automakers have had to close shop for days at end. Even this December, Honda won’t be operating for the greater part of the month as inventories are piling up. But the strategy going forward is business-as-usual. It is to let demand fall, and wait it out. As earlier opined: “If past is prologue, the IMF bail-out, monetary policy tightening and other short-term prescriptive measures would eventually stave off the crisis from worsening and demand would start rising back up. The piled inventories would be sold off later, and everybody would be none the wiser” (read: “Automotive half-life”, Dec 13, 2019).
However, plant shut downs do affect workers at the bottom of the chain, and SMEs that are highly sensitive to demand changes, many having to lay-off laborers and staff when slowdown hits. But is business-as-usual the only way? Like, Indian automakers, Pakistani automakers could use this opportunity to expand their reach. Some discounts or deals could allow inventories to be consumed faster.
More importantly, the industry needs to contemplate and re-strategize. Its heavy dependence on imported units while also not having any diversification in terms of markets means each time the economy at large is down, automakers have no contingency plan. Their costs go up, they raise prices, and ultimately demand gets affected. When this happens in a slowing down economy, consumers are already facing inflationary pressures across goods while policy tightening starts moving money out of consumption into savings.
Automakers as well as autoparts manufacturers need to invest in the industry substantially more to explore more exporting markets. They could be thinking about integrating into global or even regional value chains to expand their market reach, and grow technologically as well. The government on the other hand needs to create policies that push these companies to do better—environmentally and otherwise, as they offer sweet concessions to these assemblers.
Let’s not forget that the sector still heavily enjoys protection from imports without being a nascent or infant industry. What excuse does the industry have to continue with its outdated and complacent business model? Companies have been able to build profits doing the bare minimum over the years (Read: “Calling a spade a shovel!” Sep 24, 2019) waiting out each storm quietly without any urgency. But if the low-cost laborer is not the industry’s concern, is shutting down plants serving shareholder primacy to the best of their abilities? Automotive industry needs a longer half-life (read part I here). It needs to keep its plants running, and for that, it needs a massive change of plans.




















Comments
Comments are closed for this article.