


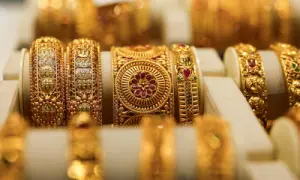
NEW YORK: Gold edged up on Tuesday as concerns over a fresh coronavirus outbreak in China countered pressure from a surge in Wall Street driven by a record rise in US retail sales and optimism over a Covid-19 drug.
Spot gold rose 0.2% to $1,727.21 per ounce by 1:28 p.m. ET (1728 GMT). US gold futures gained 0.5% to $1,735.90.
Raising concerns over the pandemic, Beijing's city government raised its COVID-19 emergency response level to II from III, according to state media.
"Gold is gaining after Beijing suddenly tightened the measures, with schools shut and people advised not to leave the city unless necessary," said Alex Turro, market strategist at RJO Futures.
Gold shook off some slight declines from earlier, which was driven by a surge in Wall Street after data showed overall retail receipts rose 17.7% last month, the biggest advance on record.
Equities also found support from data showing reduced Covid-19 death rates in a trial of a generic steroid drug.
"Every time the (gold) price falls, it seems that investors are seeing it as a buying opportunity," ActivTrades chief analyst Carlo Alberto De Casa said in a note.
Gold's fundamentals are strong, given the low interest rates environment and uncertainty over the pandemic, RJO Futures' Bob Haberkorn said.
The Bank of Japan said it expected to pump around 110 trillion yen ($1 trillion) into the economy.
Lower interest rates reduce the opportunity cost of holding non-yielding bullion.
Investors also kept a close eye on escalating tensions globally, as Indian and Chinese troops clashed at their disputed border, while North Korea blew up an inter-Korean liaison office set up in a border town.
Palladium gained 1.0% to $1,927.06 per ounce, having earlier hit its highest since June 10 at $1,965.21, while platinum rose 1.6% to $824.50. Silver was up 0.2% at $17.47. -Reuters









Comments
Comments are closed for this article.